Vegan Food Market (2025-2032)
The Vegan Food Market was valued at $42.6 billion in 2024. This market is expected to reach $109.4 billion by 2032 from an estimated $48.2 billion in 2025, at a CAGR of 12.4% during the forecast period from 2025 to 2032. Vegan Food Market Size & Forecast The market's growth can be attributed to several
- Published
- Aug 2024
- Pages
- 320
- Format
- PDF + Excel
- Report ID
- MRFB - 1041105
- Base year
- 2024
- 2024 · BASELINE
- $42.60B
- 2032
- $109.4B
- CAGR 2025–2032
- 12.4%
2024 baseline · 2025–2032 forecast at 12.4% CAGR · hover a bar for the value
Key highlights
The Vegan Food Market was valued at $42.6 billion in 2024.
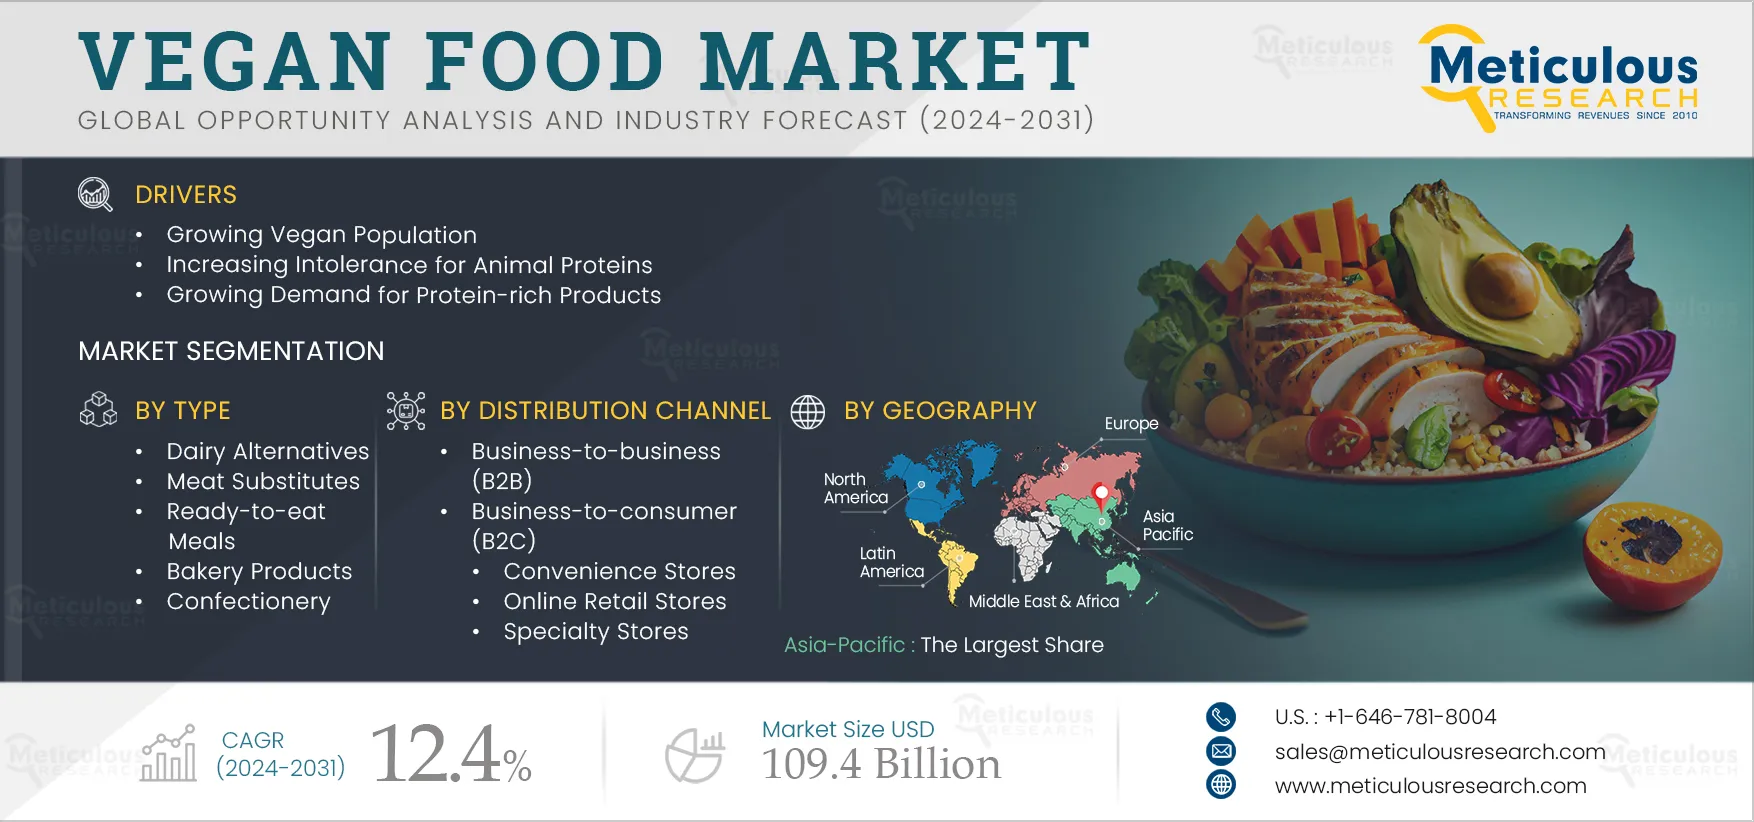
This market is expected to reach $109.4 billion by 2032 from an estimated $48.2 billion in 2025, at a CAGR of 12.4% during the forecast period from 2025 to 2032.
The dairy alternatives segment is expected to account for the largest share of 65.6% of this market.
The business-to-consumer segment is expected to account for the largest share of 67.9% of this market.
In 2025, the Asia-Pacific region is anticipated to register the largest share of the market at 44.6%, followed by North America and Europe.
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | ~320 |
| Format | |
| Forecast Period | 2025–2032 |
| Base Year | 2024 |
| CAGR (Value) | 12.4% |
| Market Size (Value) | USD 109.4 Billion by 2032 |
| Segments Covered | By Type · Dairy Alternatives · Yogurt · Milk · Ice Cream · Cheese · Butter · Other Dairy Alternatives · Meat Substitutes · Tofu · Sausages · Ground Meat · Meatballs · Nuggets · Other Meat Substitutes · Ready-to-eat Meals · Bakery Products · Confectionery · Protein Bars & Snacks · Other Vegan Foods · By Distribution Channel · Business-to-business (B2B) · Business-to-consumer (B2C) · Modern Groceries (Supermarkets & Hypermarkets) · Convenience Stores · Online Retail Stores · Specialty Stores · Other B2C Distribution Channels |
| Countries Covered | Asia-Pacific (China, India, Japan, Australia, South Korea, Thailand, and Rest of Asia-Pacific), North America (U.S., Canada), Europe (Germany, U.K., Spain, Italy, France, Netherlands, Belgium, Austria, Poland, Portugal, and Rest of Europe), Latin America (Brazil, Mexico, Argentina, and Rest of Latin America), and Middle East & Africa |
| Key Companies | The Archer Daniels Midland Company (U.S.), Hain Celestial Group, Inc. (U.S.), SunOpta, Inc. (Canada), Danone S.A. (France), Conagra Brands, Inc. (U.S.), Axiom Foods, Inc. (U.S.), Daiya Foods Inc. (Canada), Kellogg Company (U.S.), Beyond Meat, Inc. (U.S.), Impossible Foods, Inc. (U.S.), Tofutti Brands, Inc. (U.S.), Amy's Kitchen, Inc. (U.S.), Taifun-Tofu GmbH (Germany), Atlantic Natural Foods, LLC (Part of Aft Holdings, Inc.) (U.S.), VBites Food, Ltd. (U.K.), and Nutrisoy Pty, Ltd. (Australia) |
Report overview
Segments covered: type, distribution channel. Regions: Asia-Pacific, North America, Europe, Latin America.
The market's growth can be attributed to several key factors, including the expanding vegan population, increasing intolerance to animal proteins, rising R&D activities, significant investments, advancements in food technology, and heightened demand for protein-rich products. However, growth is moderated by a strong preference for animal-based products and consumer demand for soy and gluten-free alternatives.
On the other hand, the increasing adoption of vegan food in emerging markets and the rising interest in alternative proteins are likely to create growth opportunities for players operating in this market. Nonetheless, the relatively high cost of vegan food presents a substantial challenge to market growth.
Furthermore, a prominent trend in the sector is the growing frequency of mergers and acquisitions within the vegan food industry.
Report infographic
Market dynamics
4 factors across 3 forcesGrowing Vegan Population
Shifts in global health and wellness concerns, ethical considerations, sustainability issues, and evolving dietary patterns are driving significant change. Over 1.5 billion people worldwide are now vegetarians (Source: Great Green Wall organization). Additionally, The World Animal Foundation (WAF) reports approximately 88 million vegans globally. In Europe, the number of vegans has surged from 1.3 million in 2016 to 2.6 million in 2020, according to the European Vegetarian Union, accounting for 3.2% of the total European population.
This rapid increase in the vegetarian population, combined with changing lifestyles, heightened industrialization, economic development, and growing health and wellness trends, has created substantial growth opportunities for vegan food manufacturers. Rising consumer awareness of the long-term health concerns associated with animal-sourced foods further supports this market GROWTH.
According to a 2022 survey by the Vegetarian Resource Group, approximately 6% of Americans abstain from meat and fish entirely, with this group evenly divided between vegetarians and vegans. Additionally, 12% of Americans typically consume vegetarian or vegan meals, while a larger segment, 45%, incorporate vegetarian or vegan options into their diet occasionally.
The following vegan growth statistics provide compelling evidence of the rising global demand for vegan food:
- In 2022, 629,000 people worldwide signed up for Veganuary, an annual challenge run by a UK nonprofit organization that promotes and educates about veganism by encouraging people to follow a vegan lifestyle for the month of January (Source: The Guardian; Veganuary).
- In 2022, the distribution of the vegan population globally was as follows: India 13%, China 6%, the U.S. 4%, Germany 3%, Brazil 2%, and Mexico 2% (Source: World Animal Foundation).
Planned vegetarian and vegan diets can be nutritionally adequate for all life stages, including pregnant women, children, and athletes. The Academy of Nutrition and Dietetics confirms that well-planned vegetarian and vegan diets are healthful and nutritionally sufficient. These diets are associated with a reduced risk of several health conditions, including ischemic heart disease, type 2 diabetes, hypertension, certain types of cancer, and obesity.
Amidst growing food security challenges, the vegan food trend is gaining traction and is expected to continue attracting interest in the coming years. As food demand rises, it will likely increase proportionally or even exceed current levels due to evolving food behaviors. Additionally, F&B manufacturers across various countries are innovating with plant-based ingredients, creating new product categories and transforming existing ones. Many countries are at different stages of nutritional transition. Consequently, the expanding vegan population and the health benefits associated with these products are driving increased demand in the vegan food market.
Increasing Intolerance for Animal Proteins
Protein intolerance is a disorder caused by reactions to ingested food proteins arising from immunological, non-immunological, metabolic, genetic, and pharmacological mechanisms. It is frequently associated with gastrointestinal symptoms. While any protein has the potential to act as an allergen, the allergenic potential of animal food proteins depends on their evolutionary distance from human proteins.
According to the National Institute of Allergy and Infectious Diseases, 90% of food allergies are attributable to eggs, milk, fish, red meat, soy, and nuts. Additionally, a bite from the Lone Star tick can trigger an allergy to red meat, including beef and pork. This tick, which is primarily found in the Southeast U.S., from Texas to Iowa and extending into New England, has been linked to the development of red meat allergies. In infants, common allergens include cow's milk and hen's eggs, while fish and seafood are prevalent allergens in adults.
As of 2021, lactose tolerance is notably high in Northern European countries, with Sweden and Finland reporting tolerance levels of 74% and 82%, respectively. According to the European Federation of Allergy and Airways Diseases Patients Associations (EFA), 17 million Europeans experienced food reactions in 2020, including 3.5 million individuals under the age of 25. The most common allergens include cow’s milk, eggs, fish, and shellfish. Due to the prevalence of animal protein allergies, many meat consumers are increasingly turning to meat substitutes made from vegan proteins, which is driving growth in the vegan food market.
Table of contents
10 chapters · 131 sections · 320 pages · click to expandSegmental analysis
| Segment | Largest share (2025) | Fastest growth (2025–2032) |
|---|---|---|
| By Type | Dairy Alternatives | — |
| By Distribution Channel | Business-to-Consumer | Significant market share of this |
By Type
- The dairy alternatives segment is expected to account for the largest share of 65.6% of this market.
- The major share of this segment can be attributed to several factors, such as the rising prevalence of lactose intolerance, growing consumer preference for vegan diets, the nutritional benefits provided by plant-based dairy products, increasing investments in dairy alternatives, and the expanding vegan and vegetarian population.
By Distribution Channel
- The business-to-consumer segment is expected to account for the largest share of 67.9% of this market.
- The significant market share of this segment is due to the rapid growth in vegan food sales at established supermarkets and hypermarket chains, increasing urbanization, rising per capita disposable income, consumers' preference for shopping at brick-and-mortar stores, and the growing consumer preference for vegan food products.
Geographic analysis
Asia-Pacific
Largest shareIn 2025, the Asia-Pacific region is anticipated to register the largest share of the market at 44.6%, followed by North America and Europe. The vegan food market in Asia-Pacific is projected to reach $21.74 billion in 2025. This large market share is driven by the growing awareness of the benefits of a plant-based diet, increased consumer concerns about the health risks associated with contaminated meat, rising health and wellness trends, higher investments in the vegan food sector, and substantial demand for a diverse range of food products from a large population base. Moreover, this region is poised to register the highest CAGR during the forecast period. The rapid growth of this region is primarily due to accelerated urbanization, an increasing vegetarian population, the growing presence of both local and international manufacturers, and rising government support for the food industry.
Competitive landscape
- April 2025
Alpine Bio (formerly Nobell Foods, Inc.) was granted a new U.S. patent for its vegan food product containing plant-expressed recombinant casein proteins.
- February 2025
Heura Foods (Spain) secured EUR 40 million in Series B funding. This investment will support the company's efforts to enhance profitability and facilitate expansion into the U.K., France, and Italy.
- September 2022
The Better Food Foundation (U.S.) introduced its canned vegan meat in the U.S., along with other products, including cold cuts, patties, and meatballs.
- Archer Daniels Midland Company (U.S.)
- Hain Celestial Group, Inc. (U.S.)
- SunOpta, Inc. · Canada
- Danone S.A. · France
- Conagra Brands, Inc. (U.S.)
- Axiom Foods, Inc. (U.S.)
- Daiya Foods Inc. · Canada
- Kellogg Company (U.S.)
- Beyond Meat, Inc. (U.S.)
- Impossible Foods, Inc. (U.S.)
- Tofutti Brands, Inc. (U.S.)
- Amy's Kitchen, Inc. (U.S.)
- Taifun-Tofu GmbH · Germany
- VBites Food, Ltd. (U.K.)
- Nutrisoy Pty, Ltd. · Australia
Frequently asked questions
Vegan food coverage in the report refers to plant-based food that does not contain meat, dairy, eggs, or any other animal-derived ingredients. This food is mainly prepared from plant sources, including vegetables, fruits, grains, legumes, nuts, and seeds. The different vegan food products include dairy alternatives, meat substitutes, ready-to-eat meals, bakery products, confectionery, and protein bars & snacks.
The vegan food market study provides valuable insights, market sizes, and forecasts in terms of value by type, distribution channel, and geography.
Cite this report
Meticulous Research. (2024). Vegan Food Market - Global Opportunity Analysis and Industry Forecast (2025-2032) (Report No. MRFB - 1041105). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/vegan-food-market-5788