Food Packaging Market (2024-2031)
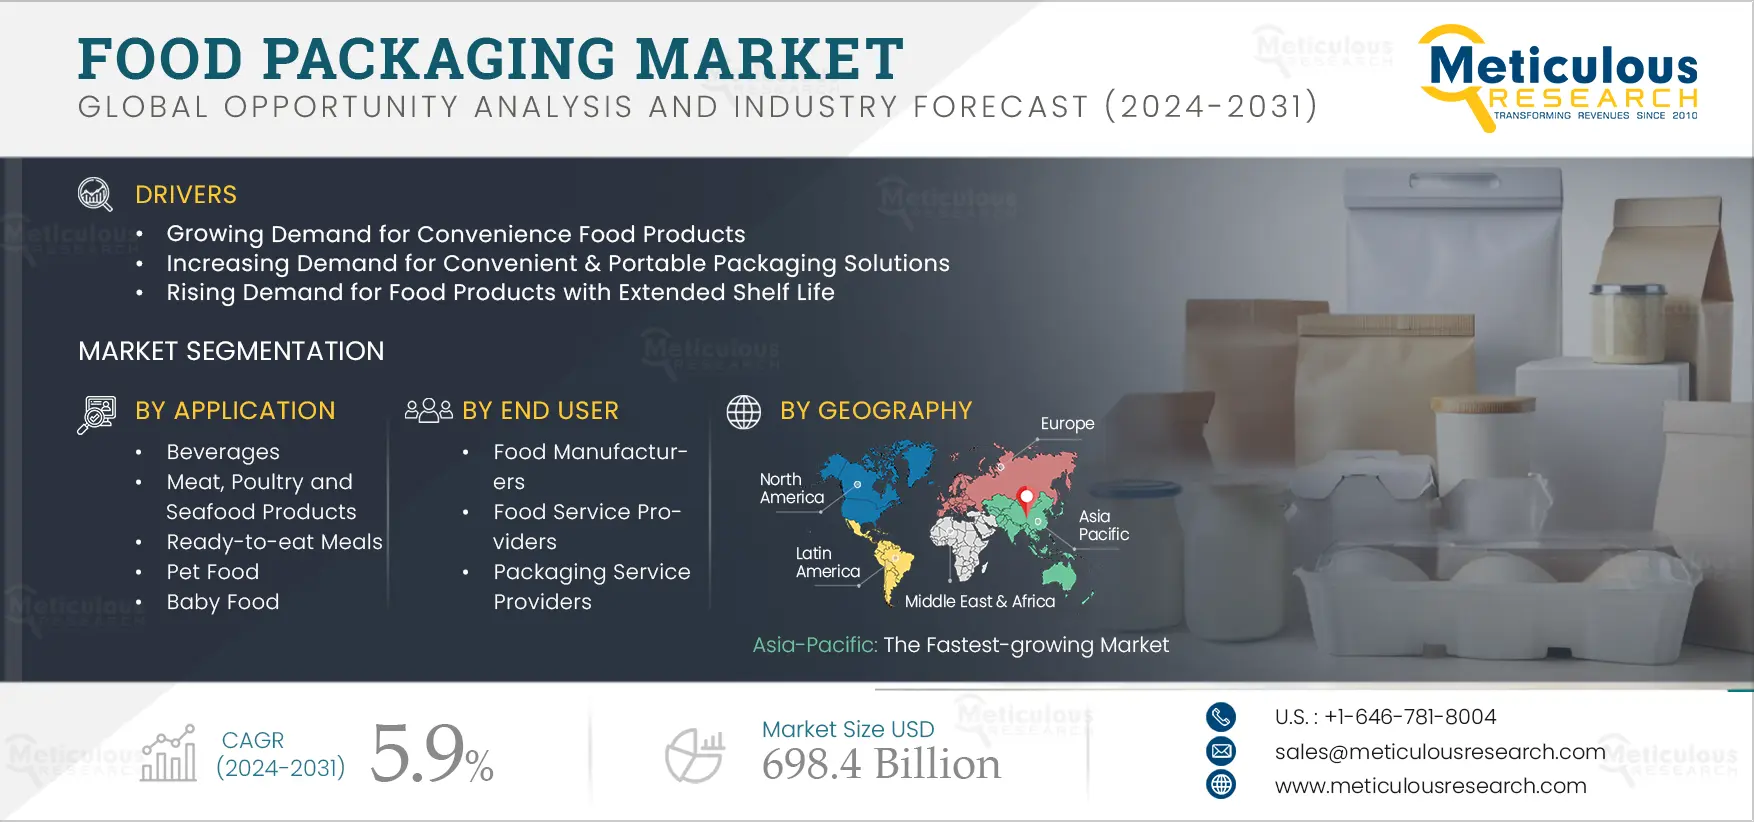
The Food Packaging Market was valued at $444.4 billion in 2023. This market is expected to reach $698.4 billion by 2031 from an estimated $468.1 billion in 2024, at a CAGR of 5.9% during the forecast period 2024-2031. Food Packaging Market Size & Forecast The growth of this market is driven by the
- Published
- Nov 2024
- Pages
- 345
- Format
- PDF + Excel
- Report ID
- MRFB - 1041289
- Base year
- 2023
- 2023 · BASELINE
- $444.4B
- 2031
- $698.4B
- CAGR 2024–2031
- 5.9%
2023 baseline · 2024–2031 forecast at 5.9% CAGR · hover a bar for the value
Key highlights
By Material: The Plastic Segment to Dominate the Food Packaging Market in 2024
By Packaging Type: The Flexible Segment to Dominate the Food Packaging Market in 2024
By Product Type: The Bags & Pouches Segment Dominate the Food Packaging Market in 2024
By Application: The Beverages Segment to Dominate the Food Packaging Market in 2024
By End User: The Food Manufacturers Segment to Dominate the Food Packaging Market in 2024
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 345 |
| Format | |
| Forecast Period | 2024–2031 |
| Base Year | 2023 |
| CAGR (Value) | 5.9% |
| Market Size (Value) | $698.4 Billion by 2031 |
| Segments Covered | By Material · Plastics · Non-biodegradable Plastic Packaging · Low-density Polyethylene (LDPE) Packaging · High-density Polyethylene (HDPE) Packaging · Polyethylene Terephthalate (PET) Packaging · Polyvinyl Chloride (PVC) Packaging · Polystyrene (PS) Packaging · Polypropylene (PP) Packaging · Other Non-biodegradable Plastic Packaging · Biodegradable Plastic Packaging · Starch-based Plastic Packaging · Polylactic Acid (PLA) Packaging · Cellulose-based Plastic Packaging · Poly-3-Hydroxybutyrate (PHB) Packaging · Polyhydroxyalkanoates (PHA) Packaging · Other Biodegradable Plastic Packaging · Paper & Paper-based Packaging · Metal Packaging · Glass Packaging · Other Packaging Materials · By Packaging Type · Flexible · Rigid · Semi-rigid · By Product Type · Bags & Pouches · Bottles & Jars · Films & Wraps · Boxes & Cartons · Trays · Cans · Stick Packs & Sachets · Other Product Types · By Application · Beverages · Bakery Products · Dairy Products · Confectionery Products · Snacks · Meat, Poultry and Seafood Products · Ready-to-eat Meals · Pet Food · Baby Food · Other Applications · By End User · Food Manufacturers · Food Service Providers · Packaging Service Providers · Other End Users |
| Countries Covered | North America (U.S., Canada), Europe (Germany, France, U.K., Italy, Spain, Netherlands, Rest of Europe), Asia-Pacific (China, Japan, India, Australia, Rest of Asia-Pacific), Latin America (Brazil, Mexico, Argentina, Rest of Latin America), and the Middle East & Africa (United Arab Emirates, Saudi Arabia, South Africa, Rest of Middle East & Africa) |
| Key Companies Profiled | Amcor plc (Australia), Smurfit Westrock plc (Ireland), Mondi plc (U.K.), Berry Global Group, Inc. (U.S.), Sealed Air Corporation (U.S.), Ball Corporation (U.S.), Tetra Pak International SA (Switzerland), Schur International Holding A/S (Denmark), Anchor Packaging LLC (U.S.), Crown Holdings, Inc. (U.S.), International Paper Company (U.S.), Graham Packaging Company Inc. (U.S.), Borealis AG (Austria), and B.C. Jindal Group (India) |
Report overview
Segments covered: material, packaging type, product type, application. Regions: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa.
The growth of this market is driven by the growing demand for convenience food products, the increasing demand for convenient & portable packaging solutions, the rising demand for food products with extended shelf life, and high growth in the retail sector. However, food packaging materials’ susceptibility to degradation and fluctuations in raw material prices restrain market growth.
Furthermore, the growing emphasis on eco-friendly packaging & recyclability and innovation in packaging technology are expected to generate growth opportunities for market stakeholders. However, stringent regulatory requirements are a major challenge for the players operating in the food packaging market.
Additionally, the rise of E-commerce and edible packaging are prominent trends in the food packaging market.
Report infographic
Market dynamics
4 factors across 3 forcesGrowing Demand for Convenience Food Products
Consumer demand for convenience foods has grown substantially over the last decade. Convenience foods (ready-to-eat/ready-to-cook meals and snacks) have gained popularity as they take less time and effort to prepare than cooking food from scratch. Factors such as hectic lifestyles, growing urbanization, and evolving consumer preferences are driving the demand for convenience food products. According to a survey conducted by the International Food Information Council in April 2023, seven in 10 Americans (72% of the total population) snack at least once a day on ready-to-eat products, with dairy, bakery, confectionery, and savory products accounting for 70% of the consumption. Moreover, according to a survey on consumer perceptions regarding food conducted by Agriculture and Agri-Food Canada, in 2023, Canadian consumers’ spending on convenience foods increased by 54% compared to 2019. Further, according to Agriculture and Agri-Food Canada, in 2021, the European snacks market was valued at $138.2 billion, and total retail sales in this market are expected to reach $173.2 billion by 2026. In addition, according to Bio Springer AM Corporation (France), the retail value of savory convenience foods in Asia during 2019-2023 totaled $378 billion.
Furthermore, more than half of the world’s population lives in urban areas, and virtually all countries are becoming increasingly urbanized. According to the United Nations World Urbanization Prospects, in 2023, almost 56.9% of the world’s population lived in urban areas, and this number is further expected to increase to 68% by 2050. Urbanization significantly contributes to improved living standards and rising incomes, influencing the affordability of convenience foods. Thus, rapid urbanization and increasing consumer preference for RTC/RTE foods contribute to the growth of the convenience foods market.
The increasing consumption of convenience foods is driving the demand for food packaging materials as packaging helps convenience food manufacturers maintain freshness, ensure quality, and improve the portability of their products. Packaging allows for the easy storage and consumption of ready-to-eat meals on the go. Thus, the growing demand for convenience foods is increasing the utilization of food packaging solutions, driving the growth of this market.
Rising Demand for Food Products with Extended Shelf Life
In recent years, there has been a notable shift in consumer behavior toward products that offer convenience, longevity, and safety. The demand for products with extended shelf life is primarily driven by the increasing need for convenience in modern lifestyles. With busy schedules and a growing preference for ready-to-eat and pre-packaged foods, consumers are seeking products that can be stored for longer periods without compromising their quality. Proper packaging ensures that food products remain fresh, nutritious, and safe for consumption over a more extended period, reducing the frequency of shopping trips and minimizing food waste. This shift toward products with extended shelf life is driving the demand for advanced food packaging solutions. The food packaging industry is focusing on technological advancements to meet the rising demand for products with extended shelf life. These advancements are aimed at improving the protective qualities of packaging materials to preserve the freshness and safety of food products over extended periods.
Thus, the increasing demand for food products with extended shelf life is boosting the development and utilization of food packaging technologies, driving the growth of this market.
Table of contents
13 chapters · 153 sections · 345 pages · click to expandSegmental analysis
| Segment | Largest share (2024) | Fastest growth (2024–2031) |
|---|---|---|
| By Material | Plastic | Plastic |
| By Packaging Type | Flexible | Flexible |
| By Product Type | Bags & Pouches | Films & wraps |
| By Application | Beverages | Snacks |
| By End User | Food Manufacturers | Food service providers |
By Material
- The Plastic Segment to Dominate the Food Packaging Market in 2024
- The plastic segment is expected to account for the largest share of 43.3% of the food packaging market.
- The large market share of this segment can be attributed to the wide range of applications and the versatile, functional properties of plastic.
- In addition, technological advancements, including the development of biodegradable plastics and the increasing demand for lightweight packaging, contribute to the segment’s large share.
- Moreover, the plastic segment is projected to register the highest growth rate of 6.6% during the forecast period 2024–2031 due to the increasing demand for biodegradable plastic packaging solutions.
By Packaging Type
- The Flexible Segment to Dominate the Food Packaging Market in 2024
- The flexible segment is expected to account for the largest share of 46.6% of the food packaging market.
- The large market share of this segment is attributed to the increasing adoption of flexible packaging due to its advantages, including convenience, sustainability, cost-effectiveness, extended shelf life, and versatility.
- Moreover, the flexible segment is also projected to register the highest CAGR of 6.5% during the forecast period 2024–2031 due to growth in E-commerce and the enhanced branding and consumer appeal offered by flexible packaging.
By Product Type
- The Bags & Pouches Segment Dominate the Food Packaging Market in 2024
- The bags & pouches segment is expected to account for the largest share of 28.6% of the food packaging market.
- This segment’s large market share is mainly attributed to continuous innovation in material & design, increased consumer demand for foods packed in bags & pouches due to the convenience offered, and the growing focus on sustainable packaging solutions.
- However, the films & wraps segment is projected to register the highest CAGR of 7.1% during the forecast period 2024–2031 due to the growing consumption of convenience foods, growth of the food service and food & grocery delivery sectors, and a shift from rigid to flexible packaging.
By Application
- The Beverages Segment to Dominate the Food Packaging Market in 2024
- The beverages segment is expected to account for the largest share of 24.3% of the food packaging market.
- This segment’s large market share can be attributed to several factors, including the growing demand for ready-to-drink beverages, the increasing focus of beverage manufacturers on brand identity, continuous innovation & new product development, and the demand for attractive and premium packaging solutions.
- However, the snacks segment is projected to register the highest CAGR of 6.2% during the forecast period, mainly due to the growing consumption of snacks, growing urban populations, the increasing number of nuclear families, the increasing number of working women, media penetration leading to an attraction for novel foods, and rising disposable incomes.
By End User
- The food manufacturers segment is expected to account for the largest share of 66% of the food packaging market.
- This segment’s large market share is attributed to the high demand for processed foods and the growing number of food processing units.
- However, the food service providers segment is projected to register the highest CAGR of 7.1% during the forecast period.
- This segment’s growth is primarily driven by the increasing number of food service outlets, the rising consumption of ready-to-eat meals and fast food, and the increasing penetration of e-commerce.
Geographic analysis
Asia-Pacific
Largest shareIn 2024, Asia-Pacific is expected to account for the largest share of 41.5% of the food packaging market, followed by Europe and North America. The Asia-Pacific food packaging market is estimated to reach $1,96.6 billion in 2024. The large share of this regional market is mainly attributed to the increased demand for processed food products, robust growth in the food & beverage industry, and rising disposable incomes. Additionally, this APAC is expected to register the highest CAGR of 6.5% during the forecast period due to growing government support for the food processing sector and food & beverage product manufacturers’ increasing focus on the development of innovative products.
Competitive landscape
- July 2024
Smurfit Kappa (Ireland) acquired WestRock Company (U.S.), a company that manufactures and distributes containerboard and paperboard packaging solutions.
- July 2024
Mondi Group (U.K.) launched Flexibag Reinforced, a range of mono-PE-based, recyclable packaging materials with improved mechanical properties.
- February 2024
Mondi Group (U.K.) acquired Hinton Pulp (Canada) from West Fraser Timber Co. Ltd. for $5 million to increase its production capacity.
- May 2024
Amcor plc (Australia) opened the Amcor Innovation Center Europe (AICE) in Ghent, Belgium. This state-of-the-art packaging innovation hub collaborates with brands and retailers to develop packaging solutions that enhance outcomes for both consumers and the environment.
- Amcor plc · Australia
- Smurfit Westrock plc · Ireland
- Mondi plc (U.K.)
- Berry Global Group, Inc. (U.S.)
- Sealed Air Corporation (U.S.)
- Ball Corporation (U.S.)
- Tetra Pak International SA · Switzerland
- Schur International Holding A/S · Denmark
- Anchor Packaging LLC (U.S.)
- Crown Holdings, Inc. (U.S.)
- International Paper Company (U.S.)
- Graham Packaging Company Inc. (U.S.)
- Borealis AG · Austria
- B.C. Jindal Group · India
Frequently asked questions
The food packaging market study covers the revenue generated from packaging products such as bags & pouches, films & wraps, stick packs & sachets, bottles & jars, boxes & cartons, trays, cans, and other packaging solutions manufactured using various materials. The food packaging market study provides valuable information, including market sizes, forecasts, and related insights based on product type, material, packaging type, application, end user, and geography.
Each segment provides the market sizes & forecasts for five key geographies (North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa), including key countries in each region.
Cite this report
Meticulous Research. (2024). Food Packaging Market - Global Opportunity Analysis and Industry Forecast (2024-2031) (Report No. MRFB - 1041289). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/food-packaging-market-5972