U.S. Point-of-Care Diagnostics Market (2025-2032)
The U.S. Point-of-Care Diagnostics Market is expected to reach $13.16 billion by 2032, at a CAGR of 4.3% during the forecast period 2025–2032.
- Published
- Jan 2025
- Pages
- 200
- Format
- PDF + Excel
- Report ID
- MRHC - 1041047
- Base year
- 2022
- 2032 · FORECAST
- $13.16B
- 2032
- $13.16B
- CAGR 2025–2032
- 4.3%
2022–2024 baseline · 2025–2032 forecast at 4.3% CAGR · hover a bar for the value
Key highlights
The Consumables Segment is Expected to Dominate the U.S. Point-of-Care Diagnostics Market in 2025
The Molecular Diagnostics Platform Segment is Expected to Register the Highest CAGR During the Forecast Period
The Blood Glucose Monitoring Segment is Expected to Dominate the U.S. Point-of-Care Diagnostics Market in 2025
The Blood Sample Type Segment is Expected to Dominate the U.S. Point-of-Care Diagnostics Market in 2025
The Home Care/Self-Testing Segment is Expected to Account for the Largest Share of the U.S. Point-of-Care Diagnostics Market
Report summary
| Particulars | Details |
|---|---|
| Page No | 200 |
| Format | |
| Forecast Period | 2025-2032 |
| Base Year | 2022 |
| CAGR | 4.3% |
| Market Size (Value) | $13.16 billion |
| Market Size (Volume) | Units |
| Segments Covered | Offering, Platform, Technique, Sample Type, and End User |
| Countries Covered | U.S. |
| Key Companies | Abbott Laboratories (U.S.), Siemens Healthineers AG (Germany), F. Hoffmann-La Roche Ltd (Switzerland), Danaher Corporation (U.S.), Becton, Dickinson and Company (U.S.), Thermo Fisher Scientific Inc. (U.S.), bioMérieux S.A. (France), QuidelOrtho Corporation (U.S.), Sekisui Diagnostics, LLC. (U.S.), Chembio Diagnostics, Inc. (U.S.), EKF Diagnostics Holdings plc (U.K.), Trinity Biotech plc (Ireland), Werfen (Spain), and Nova Biomedical (U.S.). |
Report overview
Segments covered: application, platform, sample, end user.
Point-of-care diagnostics, or bedside tests, are diagnostic tests performed on-site by healthcare professionals. These tests provide quick and accurate results without requiring samples to be sent to a laboratory. Point-of-care diagnostics products quickly determine a marker responsible for a certain disease. These tests can be used in various point-of-care settings such as physician offices, urgent care facilities, long-term care facilities, and nursing homes. Also, these devices can be categorized as handheld, transportable, and portable based on format.
The U.S. point-of-care diagnostics market is growing due to innovation in POC tests, growing commercialization of CLIA-waived POC tests, increasing funding for research and development, rising awareness regarding early disease diagnosis, and increasing prevalence of chronic and infectious diseases. However, stringent regulatory policies and pricing pressure due to fluctuations in reimbursements are restraining the growth of this market. Furthermore, growing investments in healthcare infrastructure and healthcare professionals' increasing preference for POC tests over other lab tests across the U.S. are expected to offer significant growth opportunities in the market. In addition, a lack of awareness regarding the use of POC devices is a major challenge to the market’s growth.
In efforts to deliver effective diagnostic products, key market players are focused on simplifying and automating disease diagnosis and detection steps, revolutionizing disease diagnosis processes. For instance, manufacturers have started developing automated platforms that require minimal hands-on time by trained laboratory personnel; this has driven a shift in diagnostic testing from centralized laboratories to near-patient settings, such as hospital labs, physicians’ offices, hospital outpatient departments, and home healthcare facilities. CLIA-waived tests enable testing in point-of-care settings. These tests are simple procedures with an insignificant risk of erroneous results. Such tests can be used in several settings, including pharmacy-based clinics, urgent care centers, and hospitals. Waived tests that can be performed in physician offices include streptococcus testing, HIV testing, INR (coagulation) testing for Coumadin, and pregnancy testing. CLIA-waived tests speed up diagnosis and treatment, improving patients’ clinical outcomes.
Furthermore, CLIA-waived PoC tests bring high diagnostic sensitivity and specificity to point-of-care testing. If a test is CLIA-waived, the site or facility performing the assay does not need to document personnel qualifications and training, perform quality control procedures (unless specified in the test instructions), or conduct proficiency testing or routine quality assessment related to that assay. Thus, by securing CLIA grants, vendors can help customers by reducing the documentation burden.
Many healthcare professionals in hospitals and clinical laboratories prefer using point-of-care diagnostics to diagnose several health conditions promptly. Healthcare professionals are replacing established diagnostic methods (microscopy, pathogen culturing, biochemical testing, conventional polymerase chain reaction (PCR), enzyme-linked immunoassay (ELISA), and other time-consuming diagnostic methods) with new point-of-care diagnostic techniques that provide higher levels of efficiency and reproducibility. The advantages of point-of-care diagnostics include faster turnaround times, convenience, cost-effectiveness, improved patient outcomes, and patient satisfaction. Point-of-care diagnostic tests deliver rapid results, whereas traditional lab tests can take days to provide results. This speed can be crucial for time-sensitive medical conditions, allowing healthcare providers to make timely decisions about patient care.
Further, PoC tests are performed on-site, eliminating the need to send samples to a laboratory. This saves time and resources and can be particularly useful for patients who live in remote or rural areas. These tests are less expensive than traditional lab tests, requiring less equipment and personnel, making them a more affordable option for healthcare providers, particularly in resource-constrained settings. PoC tests help healthcare providers make faster and more accurate diagnoses, which can lead to improved patient outcomes. For example, PoC tests for infectious diseases can help healthcare providers quickly identify and treat patients, preventing the spread of diseases. Thus, the inclination towards point-of-care methods and medical practices among physicians drives the growth of the U.S. point-of-care diagnostics market.
Report infographic
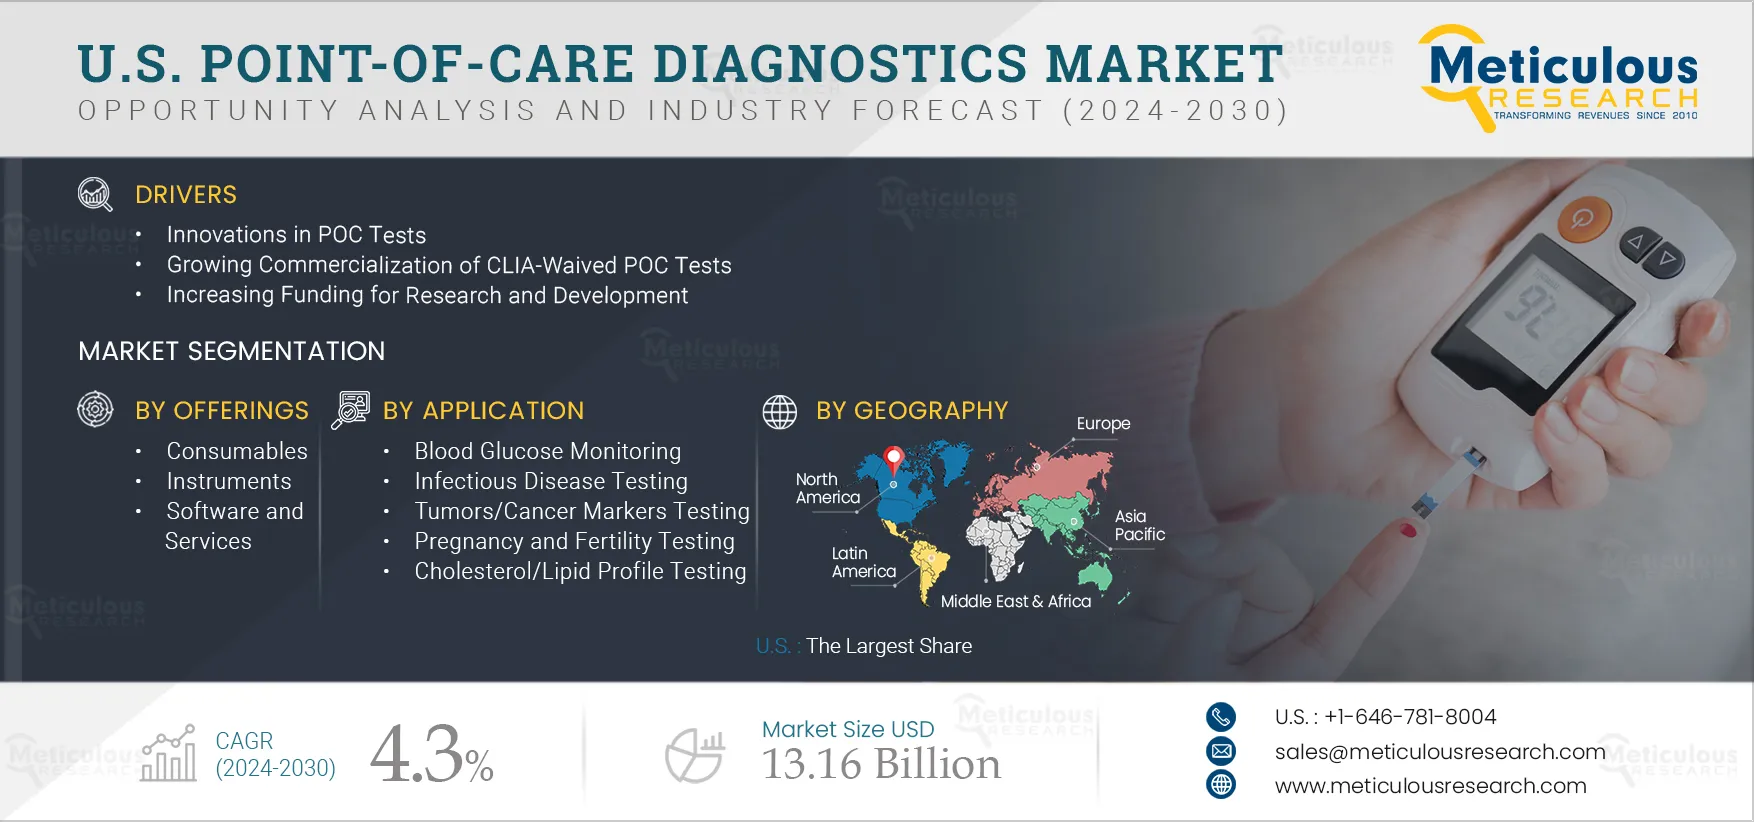
Table of contents
12 chapters · 110 sections · 200 pages · click to expandSegmental analysis
| Segment | Largest share (2025) | Fastest growth (2025–2032) |
|---|---|---|
| By All the Offering | Consumables | — |
| By All the Platform | — | Molecular diagnostics |
| By All the Application | Blood Glucose Monitoring | — |
| By All the Sample Type | Blood Sample Type | — |
| By All the end User | Home Care/Self-Testing | — |
By All the Offering
- The consumables segment is expected to account for the largest share of the market.
- Factors such as the growing demand for rapid diagnosis, the commercial availability of a diverse range of consumables, several product launches and approvals from the key players, increasing demand for POC diagnostics kits owing to their benefits such as ease of use, portability, and accuracy are contributing to the large share of this segment.
- PoC diagnostic kits are pre-packaged sets of materials and reagents for performing tests.
- These diagnostic kits are user-friendly, with clear instructions for use, and require minimal training, making them ideal for use in settings with limited access to trained laboratory personnel, such as rural or remote areas.
By All the Platform
- The Molecular Diagnostics Platform Segment is Expected to Register the Highest CAGR During the Forecast Period
- The molecular diagnostics segment is projected to register the highest CAGR during the forecast period.
- Molecular diagnostics is a sensitive method that enables the detection of lower amounts of infectious agents.
- Molecular tests are designed to detect the genetic material of a virus, bacteria, or other pathogens in a patient's sample, such as blood or saliva.
- Factors such as relative ease of use, high sensitivity, specificity, and accuracy of molecular tests, ability to perform rapid analysis, the widening applications of molecular detection tests in various fields, and high popularity and awareness regarding RT-PCR diagnostics tests are driving the segment’s growth.
By All the Application
- The blood glucose monitoring segment is expected to account for the largest share of the market.
- The large market share of this segment is mainly attributed to the increased prevalence of diabetes and the need for glucose monitoring devices.
- For instance, as per data from the International Diabetes Federation’s (IDF) Diabetes Atlas, nearly 32,215.3 adults in the U.S. survived with diabetes in 2021.
- This number is expected to reach 34, 755.3 by 2032 and 36,289.9 by 2045.
By All the Sample Type
- The blood sample type segment is expected to account for the largest share of the market.
- The large share of this segment is attributed to the availability of a wide range of tests that can be conducted using blood samples and an increasing awareness among consumers about the importance of self-monitoring.
- Blood samples are ideal for multiple point-of-care testing for diagnosing chronic diseases.
- Owing to the increasing prevalence of chronic and infectious diseases, early diagnosis is critical for successful treatment and prevention.
- For instance, in 2021, an estimated 32,100 new HIV infections occurred in the U.S.
By All the end User
- The home care/self-testing segment is expected to account for the largest share of the U.S. point-of-care diagnostics market.
- The largest share of the segment is attributed to the increasing prevalence of chronic diseases requiring long-term care and frequent monitoring, increasing home healthcare spending, growing awareness about home care, and the increasing availability of user-friendly and advanced POC diagnostic products.
- Also, the elderly population is more likely to have comorbidities and prefer staying in their home surroundings, leading to increasing demand for home care settings across the U.S.
Geographic analysis
North America
Other Platforms (Note: Other platforms include coagulation tests, dipsticks, cholesterol and glucose monitoring systems, and other point-of-care diagnostic platforms). E. U.S. Point-of-Care Diagnostics Market Assessment, by Offering Consumables Instruments Software and Services Lateral Flow Assays Molecular Diagnostics Blood Glucose Monitoring Infectious Disease Testing Parasitic Infection Testing Blood-borne Infection Testing Hepatitis HIV Other Blood-borne Infections Influenza Pneumonia Tuberculosis (TB) COVID-19 Testing Other Respiratory Infections Testing Salmonellosis Coli Infections Other GI Infections Pregnancy Testing Fertility Testing Prothrombin Time (PT/INR) Testing Activated Clotting Time (ACT/APTT) Testing Other Coagulation Testing Blood Sample Nasopharyngeal Swab Urine Sample Saliva Sample Other Sample Types (Note: Other sample types of segment include stool, cervical swab, buccal swab, hair, vaginal swab, and semen) Hospitals Home care/self-testing Physician Offices & Ambulatory Care Settings Diagnostics Laboratories Other End Users (Note: Other end users include nursing homes, long-term care centers, pharmacies, urgent care facilities, schools, airports, hotels, and workplaces.)
Competitive landscape
- Abbott Laboratories (U.S.)
- Siemens Healthineers AG · Germany
- F. Hoffmann-La Roche Ltd · Switzerland
- Danaher Corporation (U.S.)
- Becton
- Dickinson and Company (U.S.)
- Thermo Fisher Scientific Inc. (U.S.)
- QuidelOrtho Corporation (U.S.)
- Sekisui Diagnostics, LLC. (U.S.)
- Chembio Diagnostics, Inc. (U.S.)
- EKF Diagnostics Holdings plc (U.K.)
- Trinity Biotech plc · Ireland
- Werfen · Spain
- Nova Biomedical (U.S.)
Frequently asked questions
The U.S. point-of-care diagnostics market study covers the market sizes & forecasts for various point-of-care diagnostics products used in the healthcare sector. The report involves the value analysis of various segments and subsegments of the point-of-care diagnostics market at the country level.
Cite this report
Meticulous Research. (2025). U.S. Point-of-Care Diagnostics Market - Opportunity Analysis and Industry Forecast (2025-2032) (Report No. MRHC - 1041047). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/us-point-of-care-diagnostics-market-5730