Europe Point-of-Care Diagnostics Market (2025-2032)
Europe Point-of-Care Diagnostics Market is expected to reach $12.98 billion by 2032, at a CAGR of 4.1% during the forecast period 2025–2032.
- Published
- Jan 2025
- Pages
- 160
- Format
- PDF + Excel
- Report ID
- MRHC - 104967
- Base year
- 2024
- 2032 · FORECAST
- $12.98B
- 2032
- $12.98B
- CAGR 2025–2032
- 4.1%
2024 baseline · 2025–2032 forecast at 4.1% CAGR · hover a bar for the value
Key highlights
The Consumables Segment is Expected to Dominate the Europe Point-of-Care Diagnostics Market in 2025
The Molecular Diagnostics Platform Segment is Expected to Register the Highest CAGR During the Forecast Period
Based on Application, the Blood Glucose Monitoring Segment is Expected to Dominate the Europe Point-of-Care Diagnostics Market in 2025
The Blood Sample Type Segment is Expected to Register the Highest CAGR During the Forecast Period
The Home Care/Self-Testing Segment is Expected to Account for the Largest Share of the Europe Point-of-Care Diagnostics Market
Report summary
| Particulars | Details |
|---|---|
| Base Year | 2024 |
| Estimated Year | 2025 |
| Forecast Period | 2025–2032 |
| Market Size (2032) | USD 12.98 billion |
| CAGR (2025–2032) | 4.1% |
| Format | PDF, Excel & Cloud Portal · 160 pages |
| Segments Covered | By Offering: Consumables, Instruments, Software and Services · By Platform: Lateral Flow Assays, Molecular Diagnostics · By Technique: Blood Glucose Monitoring, Infectious Disease Testing Parasitic Infection Testing, Blood-borne Infection Testing Hepatitis, HIV, Other Blood-borne Infections, Influenza, Pneumonia, Tuberculosis (TB), COVID-19 Testing, Other Respiratory Infections Testing, Salmonellosis, E. Coli Infections, Other GI Infections, Pregnancy Testing · By Sample Type: Blood Sample, Nasopharyngeal Swab, Urine Sample, Saliva Sample, Other Sample Types · By End User: Hospitals, Home care/self-testing, Physician Offices & Ambulatory Care Settings, Diagnostics Laboratories, Other End Use |
| Countries Covered | Europe (Germany, France, U.K., Italy, Spain, Switzerland, Austria, Netherlands, Rest of Europe) |
| Key Companies | Abbott Laboratories (U.S.), Siemens Healthineers AG, F. Hoffmann-La Roche Ltd, Danaher Corporation (U.S.), Becton, Dickinson and Company (U.S.), Thermo Fisher Scientific Inc. (U.S.), QuidelOrtho Corporation (U.S.), Sekisui Diagnostics, LLC. (U.S.), Chembio Diagnostics, Inc. (U.S.), EKF Diagnostics Holdings plc (U.K.), Trinity Biotech plc, Werfen, Nova Biomedical (U.S.) |
Report overview
Segments covered: offering, platform, technique, sample type, end user. Regions: Europe.
Point-of-care diagnostics, or bedside tests, are diagnostic tests performed on-site by healthcare professionals. These tests provide quick and accurate results without requiring samples to be sent to a laboratory. Point-of-care diagnostics products quickly determine a marker responsible for a certain disease. These tests can be used in various point-of-care settings such as physician offices, urgent care facilities, long-term care facilities, and nursing homes. Also, these devices can be categorized as handheld, transportable, and portable based on format.
The increasing prevalence of infectious and chronic diseases, rising adoption of technical advancements to enhance the quality of point-of-care diagnostics, development of CLIA-waived POC tests, and a growing number of in-house hospital laboratories opting for PoC diagnostics are the key factors driving the Europe point of care diagnostics market. Furthermore, healthcare professionals’ increasing preference for POC tests over other lab tests and growing advanced healthcare infrastructure across European countries are expected to offer significant growth opportunities in the market. However, limited reimbursement policies and cost constraints are expected to restrain the growth of this market to some extent. In addition, low awareness regarding using PoC devices is the major challenge to the market’s growth.
In efforts to deliver effective diagnostic products, key market players are focused on simplifying and automating disease diagnosis and detection steps, revolutionizing disease diagnosis processes. For instance, manufacturers have started developing automated platforms that require minimal hands-on time by trained laboratory personnel; this has driven a shift in diagnostic testing from centralized laboratories to near-patient settings, such as hospital labs, physicians’ offices, hospital outpatient departments, and home healthcare facilities. CLIA-waived tests enable testing in point-of-care settings. These tests are simple procedures with an insignificant risk of erroneous results. Such tests can be used in several settings, including pharmacy-based clinics, urgent care centers, and hospitals. Waived tests that can be performed in physician offices include streptococcus testing, HIV testing, INR (coagulation) testing for Coumadin, and pregnancy testing. CLIA-waived tests speed up diagnosis and treatment, improving patients’ clinical outcomes.
Furthermore, CLIA-waived PoC tests bring high diagnostic sensitivity and specificity to point-of-care testing. If a test is CLIA-waived, the site or facility performing the assay does not need to document personnel qualifications and training, perform quality control procedures (unless specified in the test instructions), or conduct proficiency testing or routine quality assessment related to that assay. Thus, by securing CLIA grants, vendors can help customers by reducing the documentation burden.
Many healthcare professionals in hospitals and clinical laboratories prefer using point-of-care diagnostics to diagnose several health conditions promptly. Healthcare professionals are replacing established diagnostic methods (microscopy, pathogen culturing, biochemical testing, conventional polymerase chain reaction (PCR), enzyme-linked immunoassay (ELISA), and other time-consuming diagnostic methods) with new point-of-care diagnostic techniques that provide higher levels of efficiency and reproducibility. The advantages of point-of-care diagnostics include faster turnaround times, convenience, cost-effectiveness, improved patient outcomes, and patient satisfaction. Point-of-care diagnostic tests deliver results in minutes or hours, whereas traditional lab tests can take days to provide results. This speed can be crucial for time-sensitive medical conditions, allowing healthcare providers to make timely decisions about patient care.
Further, PoC tests are performed on-site, eliminating the need to send samples to a laboratory. This saves time and resources and can be particularly useful for patients who live in remote or rural areas. These tests are less expensive than traditional lab tests, requiring less equipment and personnel, making them a more affordable option for healthcare providers, particularly in resource-constrained settings. PoC tests help healthcare providers make faster and more accurate diagnoses, which can lead to improved patient outcomes. For example, PoC tests for infectious diseases can help healthcare providers quickly identify and treat patients, preventing the spread of diseases. Thus, the inclination toward point-of-care methods and practices among physicians drives the growth of the Europe point-of-care diagnostics market.
Report infographic
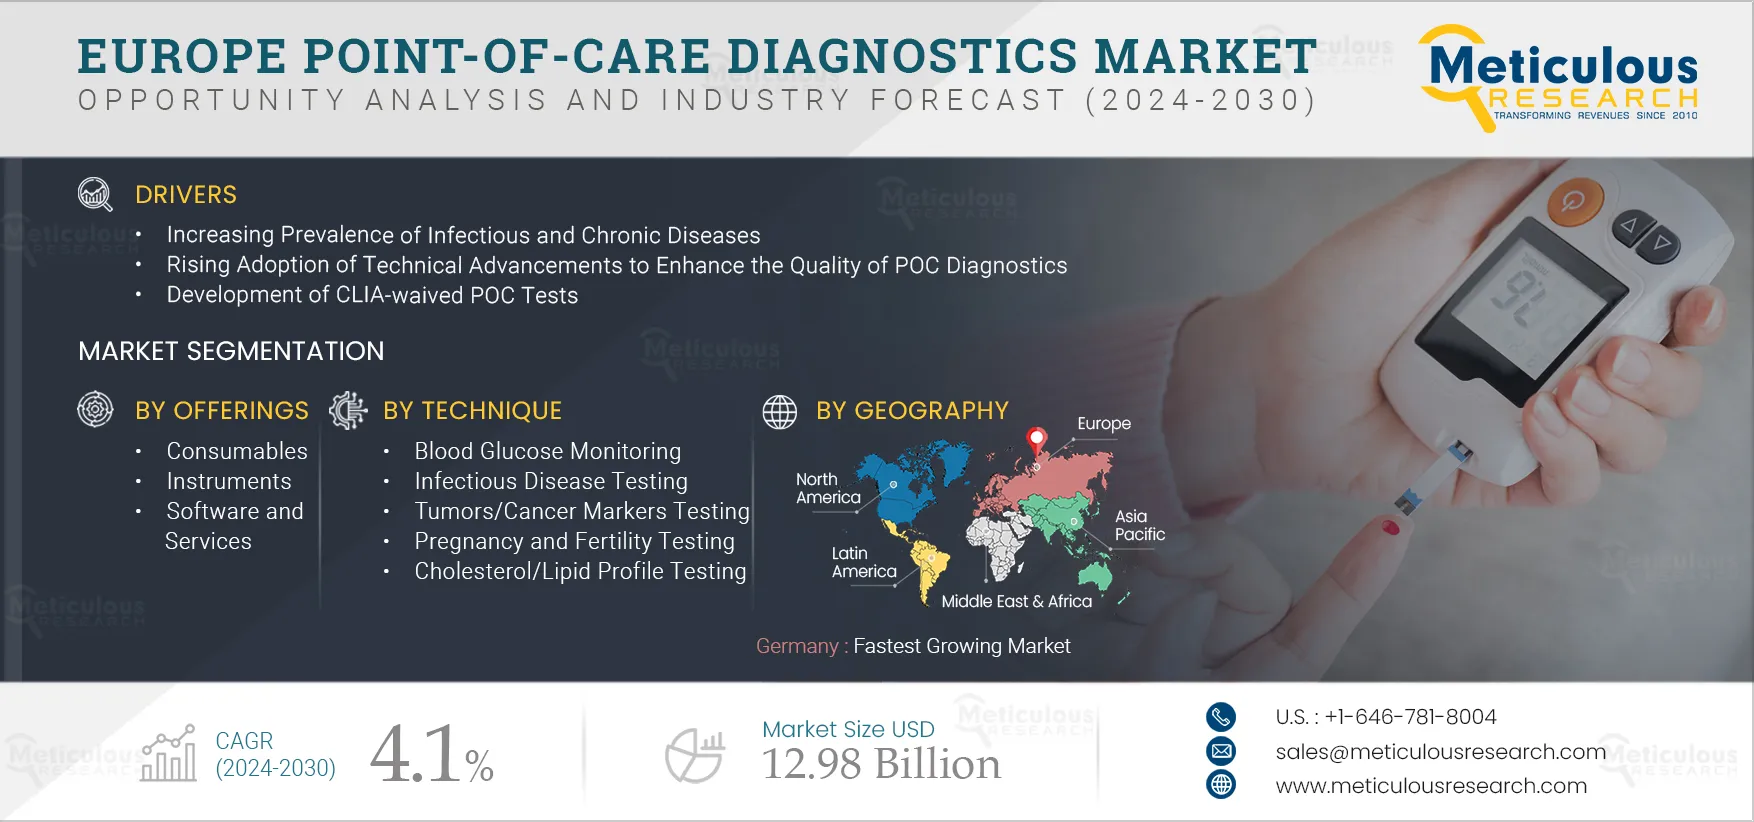
Table of contents
13 chapters · 123 sections · 160 pages · click to expandSegmental analysis
| Segment | Largest share (2025) | Fastest growth (2025–2032) |
|---|---|---|
| By Offering | Consumables | — |
| By Platform Segment | Molecular diagnostics | — |
| By Application | Blood Glucose Monitoring | — |
| By Sample Type | — | Blood sample type |
| By End User | Home Care/Self-Testing | — |
By Offering
- The consumables segment is expected to account for the largest share of the market.
- Factors such as the benefits offered by point-of-care diagnostics kits, such as ease of use, portability, and accuracy.
- PoC diagnostic kits are pre-packaged sets of materials and reagents for performing tests.
- These diagnostic kits are user-friendly, with clear instructions for use, and require minimal training, making them ideal for use in settings with limited access to trained laboratory personnel, such as rural or remote areas, which are driving the growth of this segment.
By Platform Segment
- The Molecular Diagnostics Platform Segment is Expected to Register the Highest CAGR During the Forecast Period
- The molecular diagnostics segment is expected to account for the largest share of the market.
- This segment’s large share is mainly attributed to the high sensitivity and accuracy of these tests, the growing need for advanced diagnostic techniques, and the widening applications of molecular detection tests in various fields.
By Application
- The blood glucose monitoring segment is expected to account for the largest share of the market.
- The large market share of this segment is mainly attributed to the increased prevalence of diabetes and the need for glucose-monitoring devices.
- For instance, As per data from the International Diabetes Federation’s (IDF) Diabetes Atlas, nearly 61 million adults in Europe live with Diabetes.
- This number is expected to reach 67 million by 2032 and 69 million by 2045.
By Sample Type
- The blood sample type segment is expected to grow at the highest CAGR during the forecast period.
- The growth of this segment is driven by the availability of a wide range of tests that can be conducted using blood samples, the growing prevalence of chronic diseases, and an increasing awareness among consumers about the importance of self-monitoring.
By End User
- The home care/self-testing segment is expected to account for the largest share of the Europe point-of-care diagnostics market.
- The fast growth of the home care/self-testing segment is primarily attributed to the increasing prevalence of chronic diseases requiring long-term care and frequent monitoring, increasing home healthcare spending, growing awareness about home care, and the increasing availability of user-friendly and advanced POC diagnostic products.
Geographic analysis
Europe
Fastest growthGermany is expected to account for the largest share of the Europe point-of-care diagnostics market in 2025. The large market share of the segment is attributed to the high geriatric population coupled with the growing prevalence of infectious and chronic diseases such as ischemic heart disease, stroke, chronic obstructive pulmonary disease (COPD), and cancer cases, government funding and initiatives to promote cancer screenings and the presence of key players in the country. Germany: Fastest Growing Market
Competitive landscape
- Abbott Laboratories (U.S.)
- Siemens Healthineers AG · Germany
- F. Hoffmann-La Roche Ltd · Switzerland
- Danaher Corporation (U.S.)
- Becton
- Dickinson and Company (U.S.)
- Thermo Fisher Scientific Inc. (U.S.)
- QuidelOrtho Corporation (U.S.)
- Sekisui Diagnostics, LLC. (U.S.)
- Chembio Diagnostics, Inc. (U.S.)
- EKF Diagnostics Holdings plc (U.K.)
- Trinity Biotech plc · Ireland
- Werfen · Spain
- Nova Biomedical (U.S.)
Frequently asked questions
The Europe point-of-care diagnostics market study covers the market sizes & forecasts for various point-of-care diagnostics products used in the healthcare sector. The report involves the value analysis of various segments and subsegments of the point-of-care diagnostics market at the country level.
Cite this report
Meticulous Research. (2025). Europe Point-of-Care Diagnostics Market - Opportunity Analysis And Industry Forecast (2025-2032) (Report No. MRHC - 104967). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/europe-point-of-care-diagnostics-market-5650