IVD Reagents Market (2024-2031)
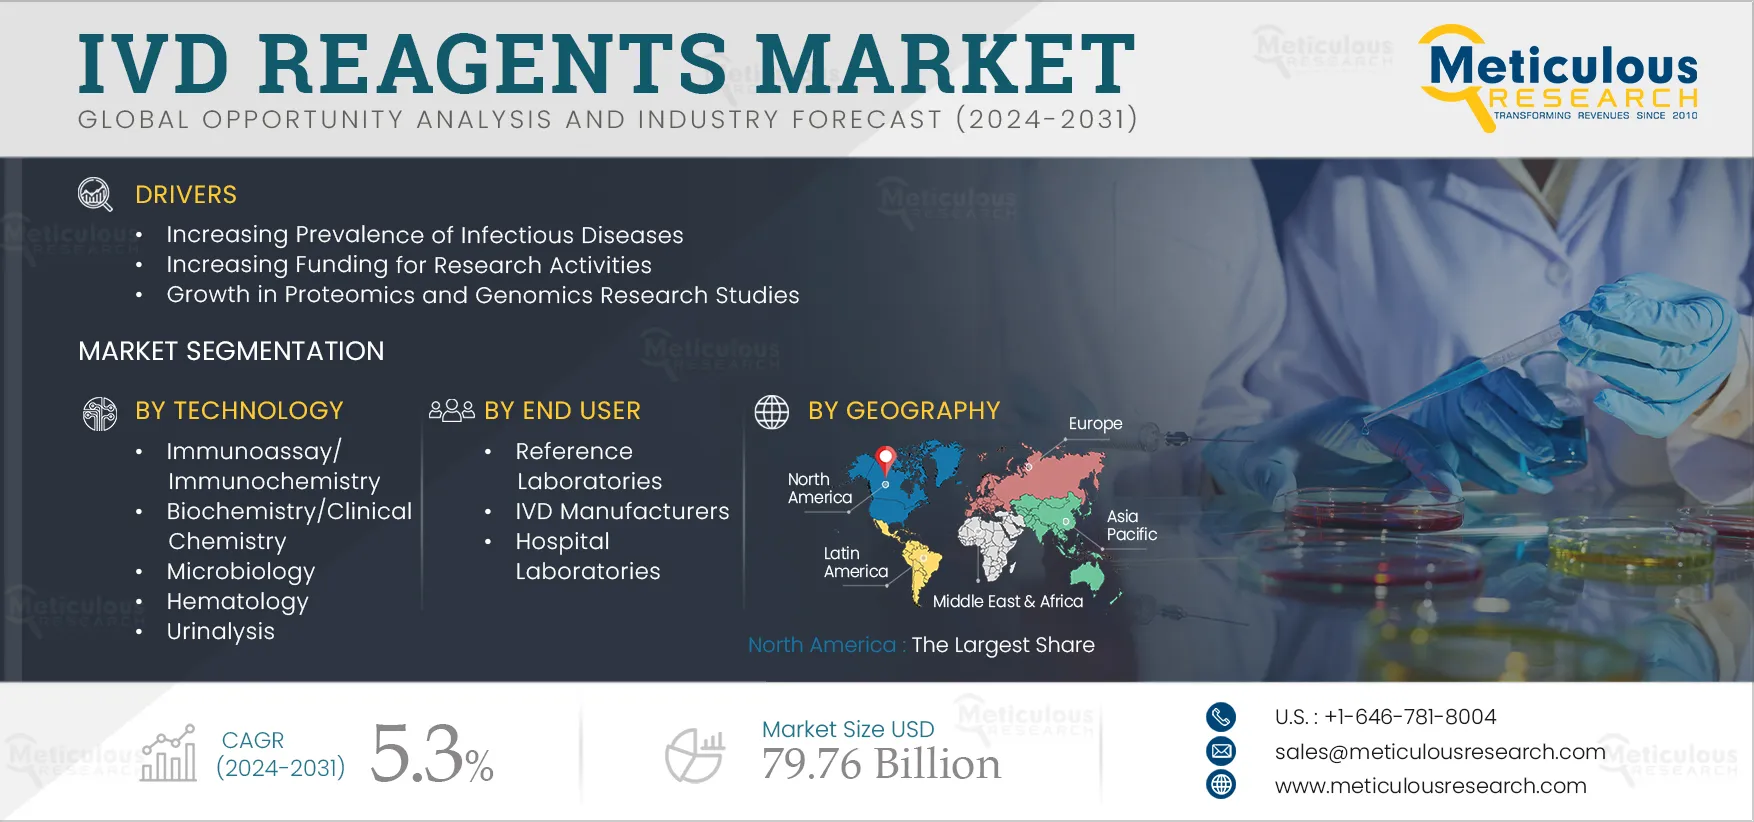
The IVD Reagents Market is expected to reach $79.76 billion by 2031, at a CAGR of 5.3% from 2024 to 2031.
- Published
- Jul 2024
- Pages
- 389
- Format
- PDF + Excel
- Report ID
- MRHC - 104414
- Base year
- 2023
- 2031 · FORECAST
- $79.76B
- 2031
- $79.76B
- CAGR 2024–2031
- 5.3%
2023 baseline · 2024–2031 forecast at 5.3% CAGR · hover a bar for the value
Key highlights
By Type: In 2024, the Antibodies Segment to Dominate the IVD Reagents Market
By Technology: In 2024, the Immunoassay/Immunochemistry Segment to Dominate the IVD Reagents Market
By Use: In 2024, the Clinical Use Segment to Dominate the IVD Reagents Market
By End User: the IVD Manufacturers Segment to Dominate the IVD Reagents Market
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 389 |
| Format | |
| Forecast Period | 2024–2031 |
| Base Year | 2023 |
| CAGR (Value) | 5.3% |
| Market Size (Value) | USD 79.76 Billion by 2031 |
| Segments Covered | By Type · Antibodies · Antibodies Market, By Type · Monoclonal Antibodies · Polyclonal Antibodies · Antibodies Market, By Target · Cluster of Differentiation (CD) · T-cell Receptor (TCR) · Epidermal Growth Factor Receptor (EGFR) · Other Targets · Purified Proteins and Peptides · Oligonucleotides · Nucleic Acid Probes · Other Reagents · (Note 1: Other targets include Nucleic BCMA, DLL/Notch, EpCAM, HER2, PDGFRα, Claudin 18.2, SLAMF7, and DKK1. B-cell maturation antigen (BCMA).) · (Note 2: Other reagents include blocking agents, detergents, surfactants, wetting agents, buffers, stabilizers, purified water, dyes, standards and controls, enzymes, cell culture reagents, and anti-coagulants.) · By Technology · Immunoassay/Immunochemistry · Enzyme-linked Immunosorbent Assays (ELISA) and Enzyme-linked Immunospot Assays (ELISpot) · Lateral Flow Assays (LFA)/Rapid Tests · Western Blotting (WB) · Immunofluorescence (IF) · Functional Assays · Immunoprecipitation (IP) · Other Immunoassay Technologies · (Note: Other technologies include virus neutralization tests, agar gel immunodiffusion, and radioimmunoassay.) · Biochemistry/Clinical Chemistry · Molecular Diagnostics · Polymerase Chain Reaction (PCR) · Hybridization · Isothermal Nucleic Acid Amplification Technology · DNA Sequencing & Next-generation Sequencing · Microarray · Other Molecular Diagnostic Technologies · (Note: Other molecular diagnostic technologies include electrophoresis, ligase chain reaction (LCR), northern blot, and southern blot.) · Microbiology · Hematology · Coagulation/Hemostasis · Urinalysis · Other IVD Technologies · (Note: Other IVD technologies include anatomical pathology, histochemistry, and whole blood glucose monitoring.) · By Use · Clinical Use · Research Use Only (RUO) · Analyte-specific Reagents (ASR) · By End User · Reference Laboratories · IVD Manufacturers · Academic Institutes and Research Laboratories · Hospital Laboratories |
| Countries Covered | North America (U.S., Canada), Europe (Germany, France, U.K., Italy, Spain, Switzerland, Ireland, Denmark, Belgium, Rest of Europe), Asia-Pacific (China, Japan, India, South Korea, and Rest of Asia-Pacific), Latin America (Brazil, Mexico, and Rest of Latin America), and Middle East & Africa |
| Key Companies | Thermo Fisher Scientific (U.S.), Becton, Dickinson and Company (U.S.), Merck KGaA (Germany), Bio-Rad Laboratories, Inc. (U.S.), Agilent Technologies, Inc. (U.S.), Abcam plc (U.K.), Hologic Inc. (U.S.), InBios International, Inc. (U.S.), SDIX, LLC (U.S.), BioTechne Corporation (U.S.), Bio-Synthesis Inc. (U.S.), RayBiotech, Inc. (U.S.), Sino Biological Inc. (China), Oy Medix Biochemica Ab (Finland), QIAGEN N.V. (Netherlands), and Beckman Coulter, Inc. (U.S.) |
Report overview
Segments covered: type, antibody, monoclonal antibody, polyclonal antibody, target, other target, purified protein, peptide, oligonucleotide, nucleic acid probe, other reagent, technology, immunoassay/immunochemistry, functional assay, other immunoassay technology, biochemistry/clinical chemistry, molecular diagnostic, hybridization, dna sequencing & next-generation sequencing, microarray, other molecular diagnostic technology, microbiology, hematology, coagulation/hemostasis, urinalysis, other ivd technology, use, clinical use, end user, reference laboratory, ivd manufacturer, academic institute, research laboratory, hospital laboratory. Regions: North America, Europe, Asia-Pacific, Latin America.
The growth of the IVD reagents market can be attributed to several factors, including the increasing prevalence of infectious diseases, increasing funding for research activities, the rising adoption of advanced diagnostic technologies, the growth in proteomics & genomics research studies, and the growing number of clinical laboratories offering advanced diagnostic testing menus. Moreover, emerging economies and the growing demand for protein therapeutics & personalized medicines are expected to offer growth opportunities for the players operating in this market.
Report infographic
Market dynamics
5 factors across 3 forcesIncreasing Prevalence of Infectious Diseases
Infectious diseases are mainly caused by organisms such as bacteria, viruses, fungi, and parasites. Some infectious diseases get transmitted from person to person or through bites from insects or animals. The burden of infectious diseases has increased globally, driving the demand for safe and effective diagnostic assays. Hence, the demand for IVD reagents is expected to grow with the increased utilization of diagnostic assays. The following statistics indicate the increased prevalence of infectious diseases:
- In 2021, 39 million people had HIV globally, of which 1.5 million were children. There were 20.8 million (53%) people with HIV in eastern and southern Africa, 5 million (13%) in western and central Africa, 6.5 million (15%) in Asia and the Pacific, and 2.3 million (5%) in Western and Central Europe and North America.
- According to an article published in the United Nations digital magazine Africa Renewal in July 2022, the risk of outbreaks caused by zoonotic pathogens such as the Ebola & monkeypox viruses that originate in animals and infect humans is rising. There has been a 63.0% increase in the number of zoonotic disease outbreaks in Africa from 2012–2022 compared to 2001– 2011 (Source: WHO).
- According to the WHO, about 1.6 million people died from tuberculosis in 2021. The disease was the 13th leading cause of death globally. In 2021, there were 10.6 million new cases of tuberculosis, of which 3.4 million were women and 1.2 million were children. The burden of drug-resistant TB (DR-TB) increased by 3% between 2020 and 2021, with 450,000 new cases of rifampicin-resistant TB (RR-TB) recorded in 2021.
Thus, the increasing prevalence of infectious diseases is expected to boost the need for diagnosis, driving the demand for IVD reagents.
Increase in Proteomics and Genomics Research Studies
In recent years, there has been a significant increase in proteomics and genomics-based research studies driven by technological advancements and the need to understand the genetic and molecular bases of various diseases. Proteomics and genomics are employed to identify proteins and genes, their structures, functions, and modifications across various research areas, particularly in medical research, drug discovery, and diagnostics. Researchers are currently utilizing multiple antibodies, including polyclonal, monoclonal, recombinant, and mono-specific antibodies, due to their high target specificity and strong affinity for target molecules.
Traditionally, proteomics and genomics studies were conducted using conventional Sanger sequencing technology, which sequenced and analyzed single genes, amplicon targets, genomic fragments, and short tandem repeats. However, according to the National Human Genome Research Institute, Sanger sequencing can produce inaccurate results, offer low throughput, and be time-consuming. Consequently, it has recently been largely replaced by Next-Generation Sequencing (NGS).
NGS can analyze 100 genes simultaneously, requires a lower amount of input material, and is cost-effective. Sanger sequencing costs about USD 500 per 1,000 bases, while NGS costs around USD 0.50 per 1,000 bases. This significant cost difference has prompted researchers to adopt more sophisticated and specific techniques. Advanced genomics and proteomics methods leverage antibody-based research for biomarker identification and drug development. For instance, the monoclonal antibody inhibitor trastuzumab (ErbB2, HER-2) has been used as a monotherapy in women with HER-2 overexpressing metastatic breast cancer.
Thus, the transition to new genomics and proteomics techniques is enhancing the precision and efficiency of research, supporting advances in biomarker identification and drug development.
Table of contents
12 chapters · 145 sections · 389 pages · click to expandSegmental analysis
| Segment | Largest share (2024) | Fastest growth (2024–2031) |
|---|---|---|
| By Type | Antibodies | — |
| By Technology | Immunoassay/Immunochemistry | — |
| By Use | Clinical Use | — |
| By End User | IVD Manufacturers | — |
By Type
- The Antibodies Segment to Dominate the IVD Reagents Market
- The antibodies segment is expected to account for the largest share of 22.1% of the IVD reagents market.
- Antibodies are glycoproteins produced by plasma cells in response to an antigen stimulus.
- These antibodies are highly specific to target molecules.
- Antibodies are necessary reagents for research and in vitro diagnostic (IVD) applications and specifically bind to a specific biomolecule or a protein of interest.
- The large share of the segment is attributed to factors such as inherent specificity, high throughput, high sensitivity, and low cost, which drive the growth of this technology segment.
- Further, the increasing use of immunoassays in POC & infectious disease testing, the development of novel tests, and the rising demand for immunoassay-based tests also contribute to the large share.
By Technology
- The immunoassay/immunochemistry segment is expected to account for the largest share of 30.8% of the IVD reagents market.
- Immunoassay/immunochemistry is a bioanalytical method in which the quantitation of the analyte depends on the reaction of an antigen and antibody.
- The large share of the segment is attributed to factors such as the increasing use of immunoassays in POC and infectious disease testing, the development of novel tests, the increasing usage of miniaturized devices, and the rising demand for immunoassay-based tests.
By Use
- The Clinical Use Segment to Dominate the IVD Reagents Market
- The clinical use segment is expected to account for the largest share of the IVD reagents market.
- IVD reagents are critical components in clinical laboratories.
- Without these reagents, these laboratories cannot generate the information required for patient diagnosis, monitoring, and treatment.
- Chemical, biochemical, and immunochemical reagents are the types of reagents used in clinical applications.
- Initiatives by manufacturers for developing advanced IVD clinical applications, ongoing clinical trials, and exemption from the investigational device (IDE) requirements are the factors contributing to the largest share of this segment.
By End User
- The IVD manufacturers segment is expected to account for the largest share of 35% of the IVD reagents market.
- In-vitro diagnostic (IVD) reagents are critical components in clinical and special chemistry testing laboratories.
- These labs generate the information required for patient diagnosis, monitoring, and treatment using IVD reagents.
- The large share of the segment is attributed to factors such as increasing demand for innovative products, growing incidence of chronic diseases, increasing demand for pharmaceutical & biopharmaceutical products from emerging countries, and initiatives undertaken by IVD manufacturers.
Geographic analysis
North America
Largest shareIn 2024, North America is expected to account for the largest share of 37.7% of the IVD reagents market, followed by Europe, Asia-Pacific, Latin America, and the Middle East & Africa. The largest share of the segment is primarily due to the growing awareness regarding early disease diagnosis, expanding healthcare sector, high prevalence of infectious and chronic diseases, rising funding activities coupled with the development of novel advanced diagnostic technologies, and growing adoption of advanced diagnostic products. By Geography: North America to Dominate the IVD Reagents Market
Asia-Pacific
Fastest growthHowever, Asia-Pacific is slated to register the highest CAGR of 7.8% during the forecast period. This is attributed to factors such as rapid urbanization, increasing investments by healthcare providers towards infrastructure improvement, the presence of key IVD reagent companies in countries like China, India, Singapore, and South Korea, and government investments in research and development activities. Furthermore, the need to manage the growing burden of infectious diseases, growing accessibility to healthcare services & advanced products, growing income levels of the middle-class population, and increasing number of hospitals and clinics contribute to the growth of this market.
Competitive landscape
- April 2023
Beckman Coulter, Inc. received In Vitro Diagnostic Medical Devices Regulation (IVDR) certification to help prepare labs for IVDR.
- April 2022
Becton, Dickinson and Company launched AI-based D Horizon RealYellow 586 Reagents for flow cytometry. These reagents help researchers to increase improved data resolution and larger insights from samples compared to traditional fluorochromes.
- January 2022
Beckman Coulter, Inc. received In Vitro Diagnostic Medical Devices Regulation (IVDR) certification for more than 200 flow cytometry reagents developed and manufactured at their Marseille, France facility.
- Thermo Fisher Scientific (U.S.)
- Becton
- Dickinson and Company (U.S.)
- Merck KGaA · Germany
- Bio-Rad Laboratories, Inc. (U.S.)
- Agilent Technologies, Inc. (U.S.)
- Abcam plc (U.K.)
- Hologic Inc. (U.S.)
- InBios International, Inc. (U.S.)
- SDIX, LLC (U.S.)
- BioTechne Corporation (U.S.)
- Bio-Synthesis Inc. (U.S.)
- RayBiotech, Inc. (U.S.)
- QIAGEN N.V. · Netherlands
- Beckman Coulter, Inc. (U.S.)
Frequently asked questions
This market study covers the market sizes & forecasts of the IVD reagents based on type, technology, use, end user, and geography. It also provides the value analysis of various segments and sub-segments of the global IVD reagents market at country levels.
Cite this report
Meticulous Research. (2024). IVD Reagents Market - Global Opportunity Analysis and Industry Forecast (2024-2031) (Report No. MRHC - 104414). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/ivd-reagents-market-5110