Medical Scheduling Software Market (2026-2036)
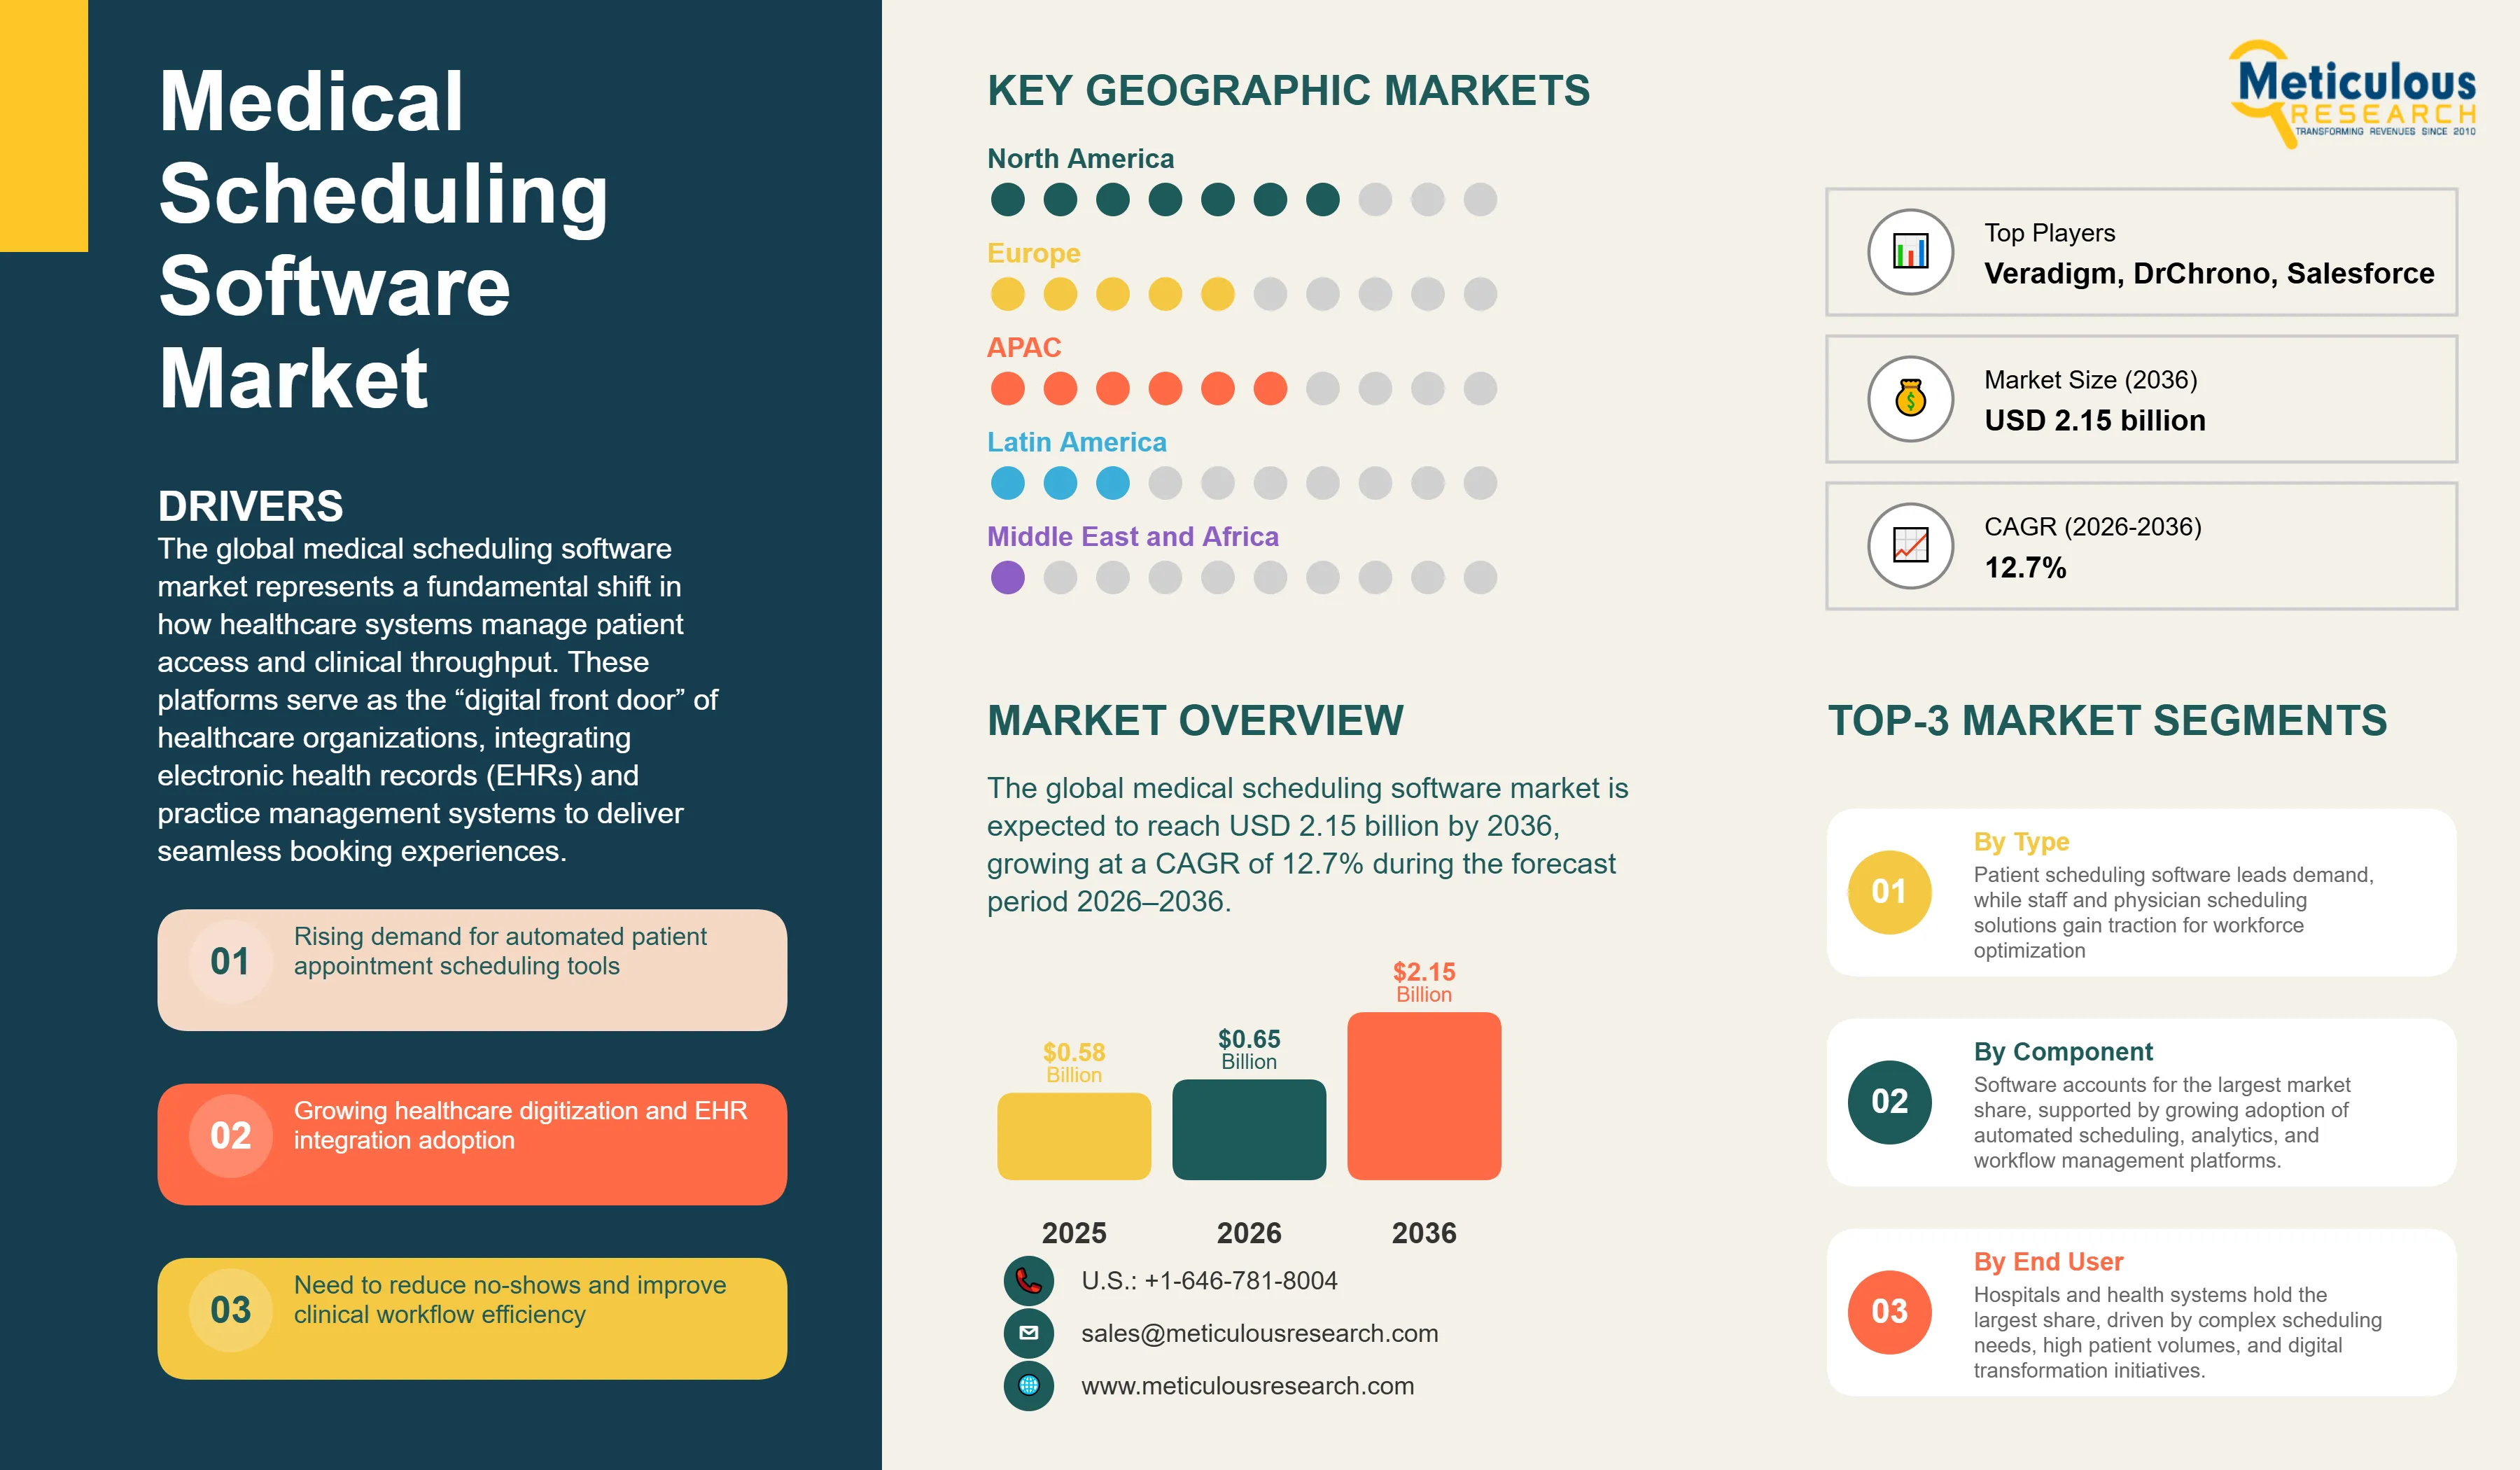
The global medical scheduling software market is estimated to be USD 0.65 billion in 2026. This market is expected to reach USD 2.15 billion by 2036, growing at a CAGR of 12.7% during the forecast period 2026–2036.
- Published
- Jun 2026
- Pages
- 307
- Format
- PDF + Excel
- Report ID
- MRHC - 1042052
- Base year
- 2025
- 2026 · ESTIMATED
- $650.0M
- 2036
- $2.15B
- CAGR 2026–2036
- 12.7%
2025 baseline · 2026–2036 forecast at 12.7% CAGR · hover a bar for the value
Key highlights
The global medical scheduling software market is projected to reach USD 2.15 billion by 2036, growing at a CAGR of 12.7% during the forecast period 2026–2036.
North America is expected to dominate the global medical scheduling software market in 2026, supported by a mature healthcare IT ecosystem, widespread digitization, and increasing efforts to reduce clinician administrative burden. Nearly all U.S. non-federal acute care hospitals have adopted certified EHR technology, providing a strong foundation for advanced scheduling and workflow solutions.
Asia Pacific is projected to witness the fastest growth, fueled by rapid investments in healthcare digitalization and government-led 'Smart Hospital' initiatives across China, India, and Australia.
By component, the software segment is expected to account for the largest share in 2026, driven by growing adoption of advanced scheduling platforms aimed at improving workflow efficiency and reducing appointment no-show rates, which commonly exceed 10% in healthcare settings.
By type, patient scheduling software is expected to account for the largest share in 2026, reflecting the primary focus on patient-centric access and digital self-service capabilities.
By deployment mode, the cloud-based segment is expected to dominate the market in 2026, accounting for approximately 78% of new installations due to superior scalability and support for multi-facility integration.
By end user, the hospitals and health systems segment is expected to account for the largest share in 2026, driven by the need to manage complex scheduling for clinicians who receive an average of 77 EHR inbox messages daily.
Key players operating in the global market include Epic Systems Corporation, Oracle Corporation (Oracle Health/Cerner), McKesson Corporation, Koninklijke Philips N.V., and Allscripts Healthcare, LLC.
Report summary
| Particulars | Details |
|---|---|
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2036 |
| Market Size (2026) | USD 650.0 million |
| Market Size (2036) | USD 2.15 billion |
| CAGR (2026–2036) | 12.7% |
| Format | PDF, Excel & Cloud Portal · 307 pages |
| Segments Covered | By Component · By Type · By Deployment Mode · By End User |
| Key Companies | Epic Systems Corporation (U.S.), Oracle Corporation (Oracle Health) (U.S.), Athenahealth, Inc. (U.S.), eClinicalWorks (U.S.), NextGen Healthcare, Inc. (U.S.), GE HealthCare Technologies Inc. (U.S.), Philips Healthcare, Veradigm Inc. (U.S.), Tebra Technologies, Inc. (U.S.), AdvancedMD, Inc. (U.S.), Greenway Health, LLC (U.S.), DrChrono Inc. (U.S.), Nextech Systems, LLC (U.S.), CureMD Healthcare (U.S.), QGenda, LLC (U.S.), MEDITECH (U.S.), Phreesia, Inc. (U.S.), Zocdoc, Inc. (U.S.), Salesforce, Inc. (U.S.) |
Report overview
Segments covered: component, type, deployment mode, end user.
The global medical scheduling software market represents a fundamental shift in how healthcare systems manage patient access and clinical throughput. These platforms serve as the “digital front door” of healthcare organizations, integrating electronic health records (EHRs) and practice management systems to deliver seamless booking experiences. According to the Office of the National Coordinator for Health IT (ONC), nearly all U.S. non-federal acute care hospitals have adopted certified EHR technology, providing a strong foundation for integrated scheduling solutions. Meanwhile, the CDC estimates that U.S. physicians conduct more than 1 billion ambulatory care visits annually, increasing pressure on providers to streamline appointment workflows and optimize resource utilization. As administrative complexity rises and patient expectations for convenient access continue to grow, healthcare organizations are increasingly transitioning from manual, phone-based scheduling to automated and AI-enabled platforms capable of managing clinician availability and patient preferences in real time.
The growth of the market is being driven by the need to optimize clinical throughput and address persistent appointment no-shows, which studies have shown commonly exceed 10% and can surpass 20% in certain healthcare settings. Missed appointments contribute to revenue leakage and inefficient resource utilization, prompting providers to increasingly deploy automated reminders and digital self-scheduling tools. Simultaneously, the global healthcare workforce shortage—projected by the World Health Organization to reach nearly 10 million health workers by 2030—is accelerating the adoption of AI-enabled scheduling solutions aimed at reducing administrative burden. Industry studies have demonstrated that automated reminders and digital access tools can significantly improve attendance and patient engagement, while growing consumer preference for self-service scheduling is further supporting market expansion.
Despite clear operational benefits, market growth is constrained by integration complexities and the organizational change management required for enterprise-wide deployment. Although nearly all U.S. non-federal acute care hospitals have adopted certified EHR technology, interoperability and data fragmentation remain persistent challenges, limiting the effectiveness of advanced scheduling analytics. The healthcare sector also faces increasing cybersecurity and regulatory pressures under frameworks such as HIPAA and GDPR, requiring substantial investments in data protection and compliance. In addition, the high cost and complexity of implementing integrated scheduling platforms continue to present barriers for smaller practices and resource-constrained healthcare systems.
Emerging opportunities in hospital-at-home models and AI-driven predictive scheduling are creating new growth avenues for the medical scheduling software market. The continued expansion of telehealth and remote care services is increasing demand for platforms capable of coordinating virtual and in-person appointments while managing clinician availability across distributed care settings. AI-enabled scheduling solutions are helping health systems improve capacity utilization and forecast appointment demand, supporting more efficient resource allocation. In parallel, the growth of virtual care hubs and hospital-at-home programs is enabling providers to manage low-acuity patients remotely while preserving in-person capacity for complex cases. These trends are particularly pronounced in North America and Europe, where healthcare organizations are investing heavily in digital front doors and telehealth integration.
Report infographic
Market dynamics
2 factors across 1 forceAddressing Clinician Burnout through Intelligent Rostering
A defining trend in 2026 is the evolution of scheduling platforms from simple booking tools into intelligent clinician orchestration hubs. Advanced solutions increasingly incorporate AI and predictive analytics to optimize staffing and patient throughput amid persistent workforce shortages. According to the World Health Organization, the global healthcare sector could face a shortfall of nearly 10 million health workers by 2030, while studies published in the Journal of the American Medical Informatics Association show physicians receive approximately 70–80 EHR inbox messages daily, contributing to administrative burden. As a result, healthcare organizations are adopting AI-enabled rostering and workflow automation tools to improve schedule efficiency and reduce clinician workload.
Ambient Intelligence for Seamless Patient Journeys
The convergence of ambient intelligence and scheduling is expanding the scope of patient access management. With nearly all U.S. non-federal acute care hospitals having adopted certified EHR technology, according to the Office of the National Coordinator for Health IT (ONC), scheduling platforms are increasingly integrating mobile applications, digital check-in capabilities, and real-time patient flow data. These "virtual front desk" functions help reduce administrative bottlenecks and support more efficient patient throughput, particularly in regions facing staffing constraints. The trend is accelerating as hospitals invest in digital front doors and connected care ecosystems to enhance access and operational performance.
Table of contents
12 chapters · 114 sections · 307 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Component | Software | Services |
| By Type | Patient scheduling software | Staff/physician scheduling |
By Component
- The software segment is expected to hold the largest share in 2026.
- This dominance is driven by the consolidation of healthcare providers into large integrated delivery networks (IDNs) that require a centralized 'source of truth' for patient scheduling.
- However, the services segment is projected to register the highest CAGR during the forecast period.
- This growth is fueled by the expansion of implementation and integration services, where specialized consultants coordinate the deployment of complex platforms across multi-facility networks, thereby increasing system efficiency without physical facility expansion.
By Type
- The patient scheduling software segment is expected to account for the largest share in 2026.
- These platforms are foundational to modern patient access, enabling the 80% of patients who prefer digital booking to engage with providers seamlessly.
- The staff/physician scheduling segment is projected to register the highest CAGR, as health systems increasingly adopt autonomous operational modules to combat the 41.9% physician burnout rate.
- The integration of workforce management technology remains a critical secondary segment, providing the real-time availability data necessary for precise clinical coordination.
Geographic analysis
North America
Largest shareNorth America is expected to dominate the global medical scheduling software market in 2026. The region's dominance is supported by a mature healthcare IT landscape and the widespread adoption of digital front doors by large IDNs. These systems have reported serving thousands of additional patients annually through optimized appointment orchestration. The presence of leading vendors and significant investment in digital health infrastructure—with U.S. hospitals spending over $30 billion annually on technology—continue to drive the market in the U.S. and Canada. North America
Asia-Pacific
Fastest growthThe Asia Pacific region is projected to witness the fastest growth during the forecast period. This is driven by rapid healthcare infrastructure expansion and 'Smart Hospital' initiatives across China, India, and Australia. Major private healthcare providers in the region are standardizing on centralized scheduling models to manage large patient volumes across multi-facility networks. The increasing adoption of cloud-based platforms and the digital transformation of public health agencies in the region are creating substantial opportunities for global technology integrators. Asia Pacific
Competitive landscape
The competitive landscape of the global medical scheduling software market is characterized by intense innovation and strategic acquisitions as vendors seek to provide end-to-end patient access platforms. Leading players are differentiating themselves through the sophistication of their AI engines and their ability to provide demonstrated ROI in terms of no-show reduction and referral capture. Strategic moves, such as the integration of clinical communication and throughput modules into unified ecosystems, are redefining vendor positioning in the June 2026 landscape.
- Epic Systems Corporation (U.S.)
- Oracle Corporation (Oracle Health) (U.S.)
- Athenahealth, Inc. (U.S.)
- eClinicalWorks (U.S.)
- NextGen Healthcare, Inc. (U.S.)
- GE HealthCare Technologies Inc. (U.S.)
- Philips Healthcare · Netherlands
- Veradigm Inc. (U.S.)
- Tebra Technologies, Inc. (U.S.)
- AdvancedMD, Inc. (U.S.)
- Greenway Health, LLC (U.S.)
- DrChrono Inc. (U.S.)
- Nextech Systems, LLC (U.S.)
- CureMD Healthcare (U.S.)
- QGenda, LLC (U.S.)
- MEDITECH (U.S.)
- Phreesia, Inc. (U.S.)
- Zocdoc, Inc. (U.S.)
- Salesforce, Inc. (U.S.)
Frequently asked questions
The market is projected to reach USD 2.15 billion by 2036, growing at a CAGR of 12.7% from 2026 to 2036.
Cite this report
Meticulous Research. (2026). Medical Scheduling Software Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MRHC - 1042052). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/medical-scheduling-software-market-6735