Workflow Automation Market (2025-2035)
workflow automation market was valued at USD 9.38 billion in 2024. This market is expected to reach USD 11.63 billion in 2025, and is projected to reach approximately USD 78.26 billion by 2035, at a CAGR of 21% during the forecast period of 2025 to 2035.
- Published
- Sep 2025
- Pages
- 219
- Format
- PDF + Excel
- Report ID
- MRICT - 1041023
- Base year
- 2024
- 2024 · BASELINE
- $9.38B
- 2035
- $78.26B
- CAGR 2025–2035
- 21%
2024 baseline · 2025–2035 forecast at 21% CAGR · hover a bar for the value
Key highlights
In 2025, the Software Segment is Expected to Dominate the Workflow Automation Market
In 2025, the Business Process Automation Segment is Expected to Dominate the Workflow Automation Market
In 2025, the Cloud-based Deployment Segment Is Expected to Dominate the Workflow Automation Market
In 2025, the Large Enterprises Segment is Expected to Dominate the Workflow Automation Market
In 2025, the Finance Segment is Expected to Dominate the Workflow Automation Market
In 2025, the IT & Telecommunications Segment is Expected to Dominate the Workflow Automation Market
Asia-Pacific to be the Fastest-growing Regional Market
Report summary
| Particulars | Details |
|---|---|
| Base Year | 2024 |
| Estimated Year | 2025 |
| Forecast Period | 2025–2035 |
| Market Size (2024) | USD 9.38 billion |
| Market Size (2025) | USD 11.63 billion |
| Market Size (2035) | USD 78.26 billion |
| CAGR (2025–2035) | 21% |
| Format | PDF, Excel & Cloud Portal · 219 pages |
| Segments Covered | By Offering: Software, Services · By Type: Business Process Automation, Robotic Process Automation · By Deployment Mode: On-premise Deployments, Cloud-based Deployments · By Organization Size: SMEs, Large Enterprises · By Application: Human Resources, Finance, Procurement, IT Service Requests, Sales, Marketing, Other Applications · By Sector: IT & Telecommunications, Automotive, Transportation & Logistics, Healthcare, Energy & Utilities, Manufacturing, Retail, BFSI, Government & Defense, Other Sectors · By Deployment · By Organization |
| Countries Covered | North America (Canada), Europe (Germany, U.K., France, Italy, Spain, Rest of Europe), Asia-Pacific (China, Japan, India, South Korea, Rest of Asia-Pacific) |
| Key Companies | Business Machines Corporation, Software AG, Oracle Corporation, Pegasystems Inc., Appian Corporation, Newgen Software Technologies Limited, Zapier, Inc., Formstack, LLC, Microsoft Corporation, Nintex Global Ltd., ServiceNow, Inc., IPsoft Inc., Amelia LLC, Open Text Corporation, SysAid Technologies Ltd., Jotform Inc., Kissflow Inc., Next Matter GmbH, DocuWare GmbH, Camunda Services GmbH, HeightHQ, Inc., Integrify, Inc., Wrike, Inc., SAP SE, Really Simple Systems Ltd. |
Report overview
Segments covered: offering, type, deployment mode, organization size, application, sector, deployment, organization. Regions: North America, Europe, Asia-Pacific.
The growth of this market is attributed to the rising demand for real-time automation solutions, the increasing adoption of business process automation across various industries, and the growing need for enhanced communication and collaboration within organizations. Additionally, the increasing applications of cloud and IoT technologies in automation processes and the rising adoption of robotic process automation (RPA) are anticipated to create significant market growth opportunities.
However, concerns related to data privacy and security restrain the market's growth. Additionally, issues related to the integration and compatibility of legacy systems pose significant challenges for the players operating in this market. Furthermore, the emergence of automation-as-a-service (AaaS) and the utilization of artificial intelligence and chatbots are prominent trends in the workflow automation market.
Real-time automation solutions provide immediate or deferred responses to business procedures, enabling organizations to optimize their operations by automating various tasks and processes. This results in enhanced efficiency and productivity, as tasks are executed more rapidly and with reduced errors. Workflow automation software plays a pivotal role in numerous real-time automation systems, equipping users with the necessary tools and functionalities for the efficient design, implementation, and management of automated processes. Additionally, it helps reduce human errors, contributing to more accurate data processing.
Real-time automation solutions find applications in various sectors, including IT & telecommunications, defense, aerospace, healthcare, and manufacturing. In the manufacturing sector, real-time automation plays a crucial role in enabling manufacturers to enhance the efficiency of production lines by continuously monitoring and adjusting processes in real time. In the healthcare sector, it aids in the identification of suspicious activities or transactions. In the transportation and logistics industry, real-time automation is instrumental in monitoring inventory levels in real time, resulting in reduced delivery times and lower fuel costs. In the IT & telecommunications sector, these solutions are employed to monitor network performance and optimize bandwidth allocation, leading to improved service quality. These solutions help companies gain a competitive advantage over competitors reliant on manual processes by enabling faster response times, increased accuracy, and enhanced customer service.
Some of the recent developments in the workflow automation market are as follows:
In May 2025, OpenText Corporation introduced Process Automation CE 25.2 featuring AI-powered no-code app building and secure deployment.
In February 2025, Next Matter GmbH announced enterprise-grade AI-powered workflow automation solutions for fund management clients.
In April 2024, Software AG expanded partnership with woolworths for retail workflow automation using webmethods platform.
Report infographic
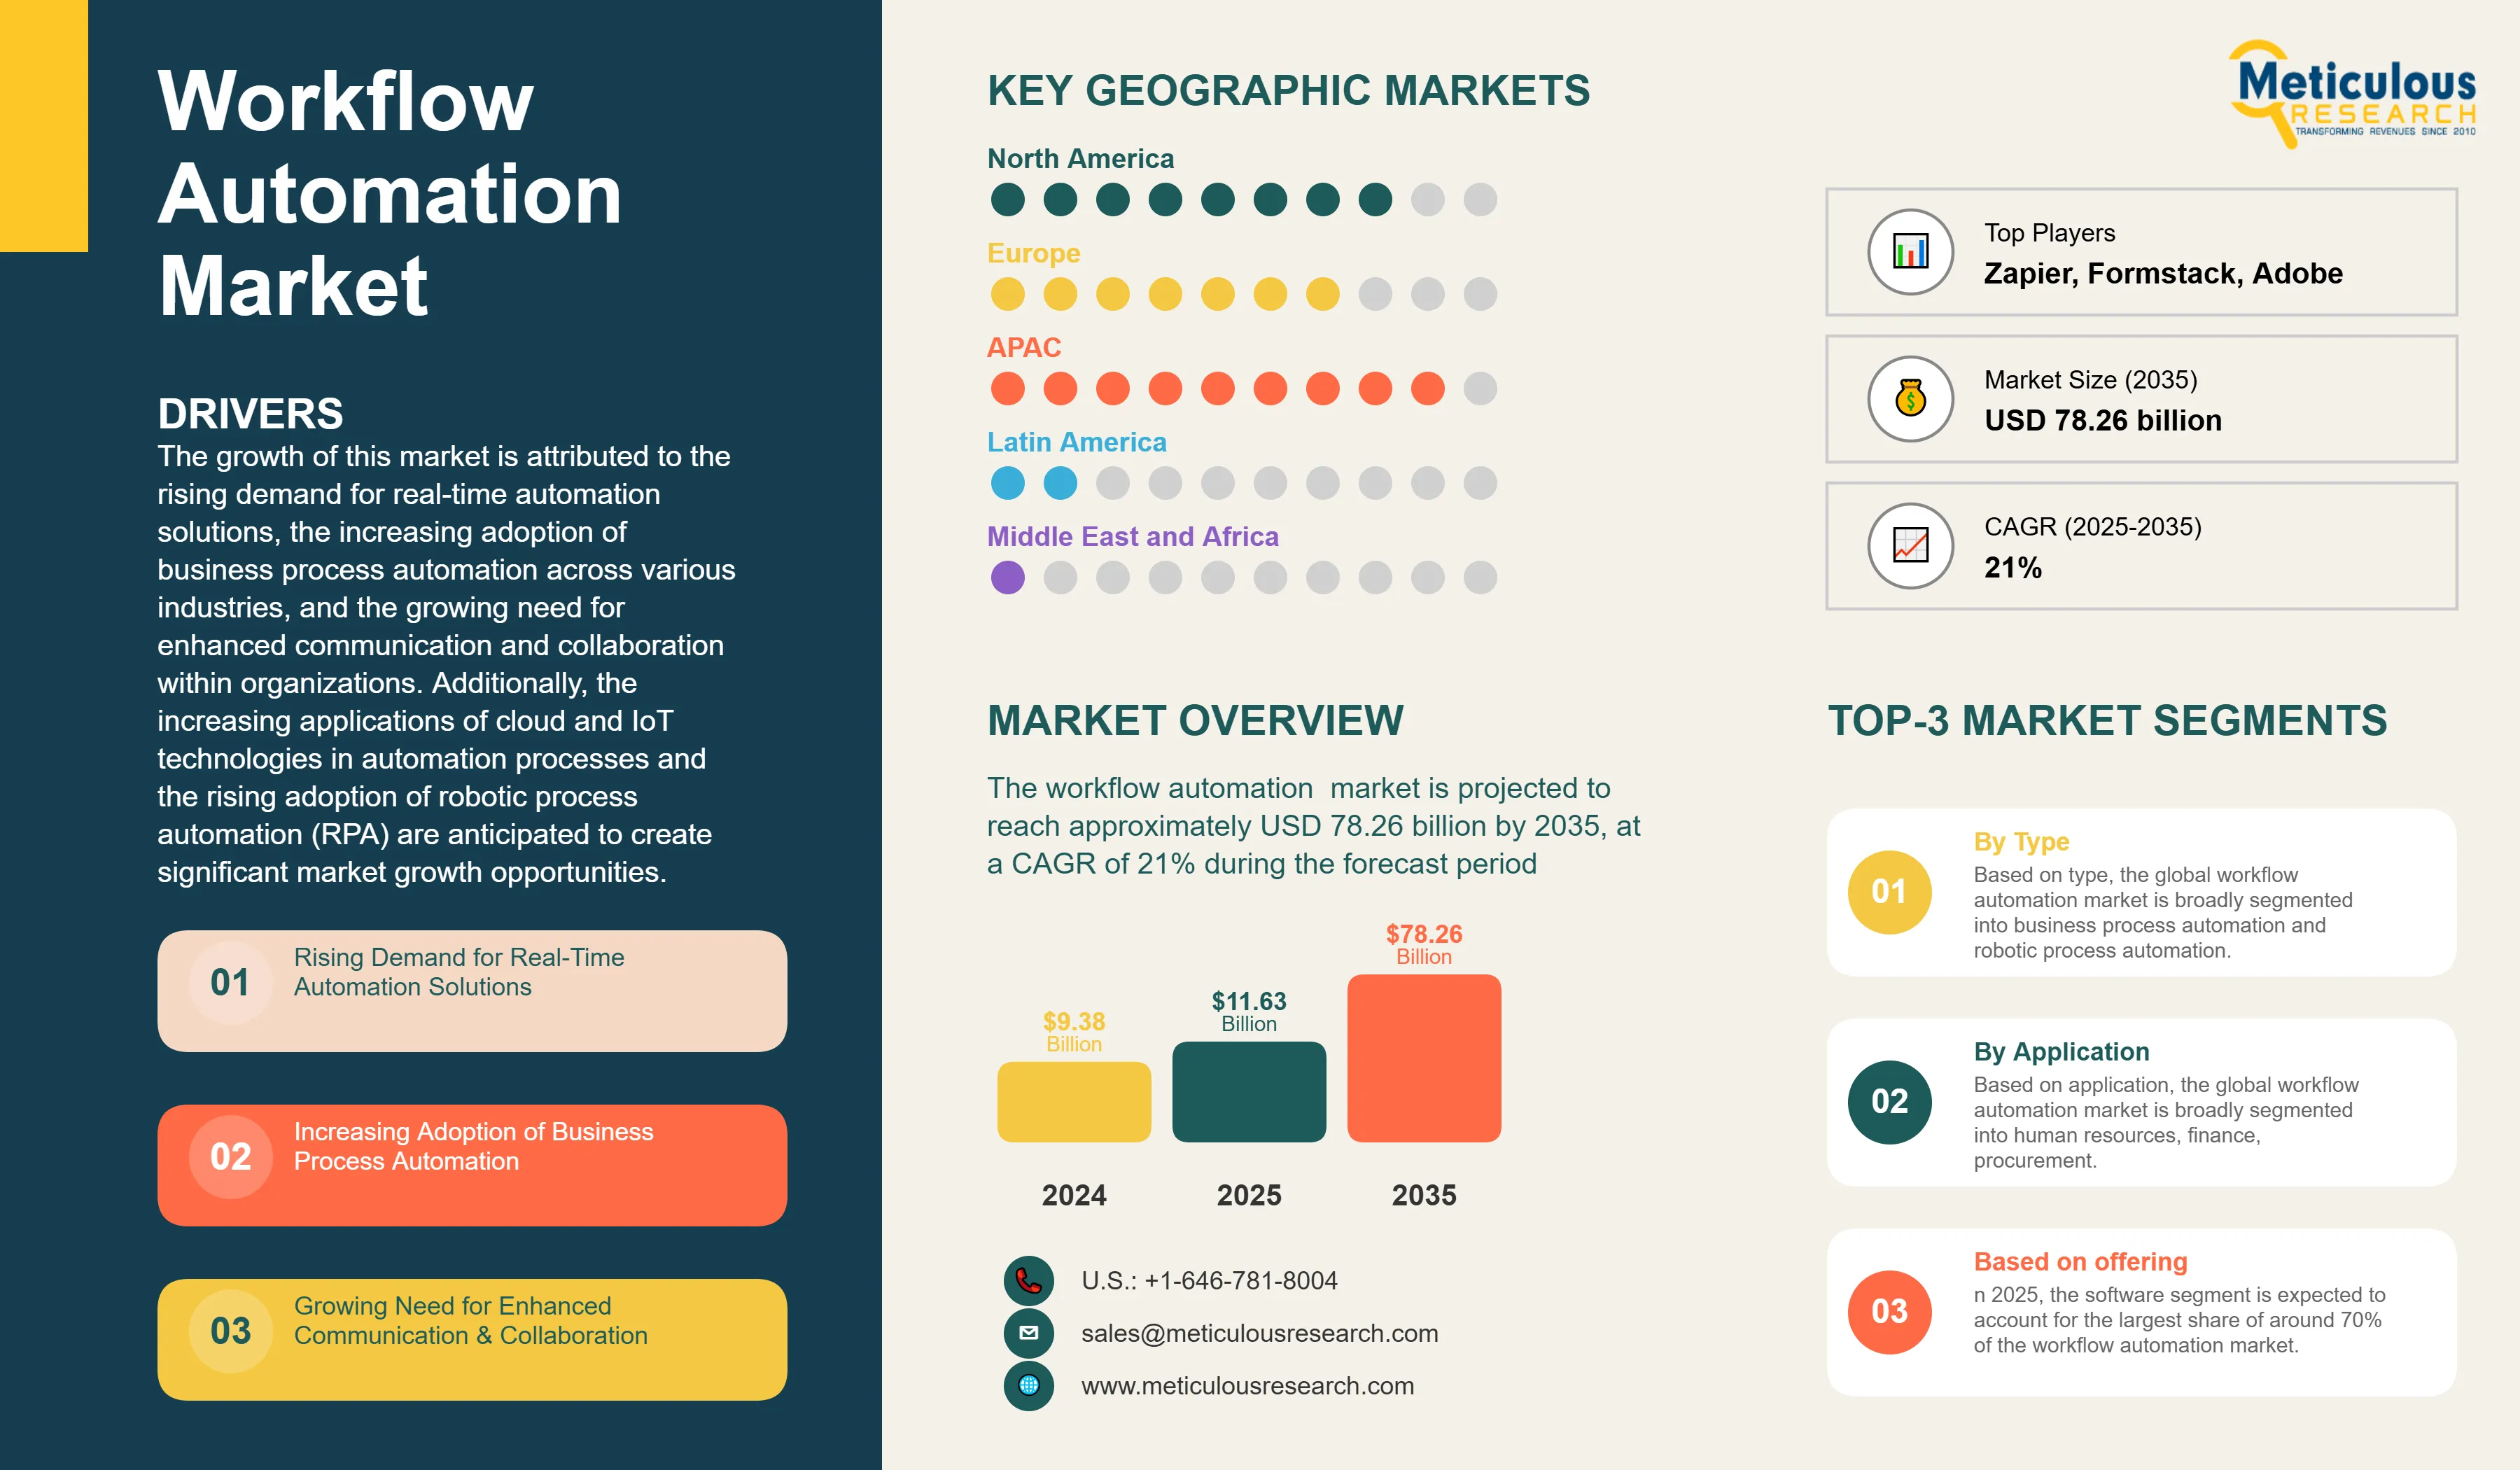
Table of contents
14 chapters · 135 sections · 219 pages · click to expandSegmental analysis
| Segment | Largest share (2025) | Fastest growth (2025–2035) |
|---|---|---|
| By Offering | Software | — |
| By Type | Business Process Automation | — |
| By Deployment Mode | Cloud-based Deployment | Cloud-based deployment segment's dominance and rapid growth |
| By Organization Size | Large Enterprises | — |
| By Application | Finance | Marketing |
| By Sector | — | Healthcare |
By Offering
- The software segment is expected to account for the largest share of around 70% of the workflow automation market.
- The software segment's dominance is rooted in its position as the essential, core component of any automation initiative.
- It is the foundational technology upon which automated processes are built, managed, and optimized.
- While services are crucial for implementation and support, they are inherently dependent on the existence and capabilities of the software itself.
- The initial and ongoing investment in software licenses, platforms, and suites constitutes the largest portion of automation expenditure for organizations.
- This includes investments in comprehensive Business Process Management (BPM) suites, Robotic Process Automation (RPA) tools, and integration platform-as-a-service (iPaaS) solutions, which form the digital backbone for automating complex workflows across departments like finance, HR, and supply chain.
By Type
- The business process automation segment is expected to account for the largest share of around 58% of the workflow automation market.
- The large market share of this segment is attributed to factors such as the rising need to automate repetitive tasks, the need to enhance accountability and transparency and ensure precise data recording, and the surge in digital transformation efforts among enterprises.
- However, the robotic process automation segment is projected to register a higher CAGR of more than 25% during the forecast period.
- This growth can be attributed to the increasing need to minimize human errors, enhance work efficiency, reduce overhead expenses, improve the accuracy and reliability of business processes, and reduce operational costs and the rising demand for robotic process automation in the BFSI, healthcare, and transportation & logistics sectors to meet their operational demands.
By Deployment Mode
- The cloud-based deployment segment is expected to account for the largest share of the workflow automation market.
- The cloud-based deployment segment's dominance and rapid growth are primarily driven by its fundamental alignment with the core objectives of modern businesses: agility, scalability, and cost-efficiency.
- Unlike traditional on-premises solutions that require significant upfront capital investment in hardware and dedicated IT staff for maintenance, cloud-based workflow automation operates on a subscription-based, pay-as-you-go model.
- This dramatically lowers the barrier to entry, making powerful automation tools accessible not only to large enterprises but also to small and medium-sized businesses that may lack extensive IT infrastructure.
- The cloud model eliminates the need for complex, time-consuming installations, allowing organizations to deploy solutions rapidly and begin realizing a return on investment much quicker.
- This operational expenditure (OpEx) approach is increasingly preferred over the capital expenditure (CapEx) model of on-premises systems, as it offers greater financial flexibility and reduces the total cost of ownership
- The cloud-based deployments segment is also projected to register a higher CAGR during the forecast period.
- This growth is driven by the growing adoption of cloud-based solutions by small and medium-sized enterprises, the rising demand for cost-effective subscription models and automated threat detection solutions, and the enhanced flexibility provided by cloud-based deployments.
By Organization Size
- The large enterprises segment is expected to account for the largest share of the global workflow automation market.
- The large market share of this segment can be attributed to the rising adoption of robotic process automation to streamline repetitive tasks, the growing demand for consistency across various operations within large enterprises, and the increasing focus on digital transformation initiatives.
- However, the SMEs segment is projected to register a higher CAGR during the forecast period due to the growing awareness among SMEs regarding the benefits of automating business processes and the increasing significance of digital solutions, including CRM and ERP platforms, for enhancing productivity.
By Application
- The finance segment is expected to account for the largest share of 51% of the global workflow automation market.
- The large market share of this segment can be attributed to the widespread use of digital banking solutions for real-time transaction processing and data accuracy in financial operations, an increasing focus on enhancing customer experiences, the growing implementation of RPA to reduce labor costs and improve operational efficiency, and the rising need to improve financial services and document management.
- However, the marketing segment is experiencing rapid growth as it undergoes a fundamental shift towards data-driven, personalized, and agile customer engagement.
- Modern marketing is no longer just about broad campaigns; it involves orchestrating complex, multi-channel customer journeys across email, social media, web, and advertising platforms.
- This requires seamless execution of numerous repetitive tasks—such as lead nurturing, customer segmentation, campaign deployment, and performance reporting—which are ideal for automation.
- Marketing teams are rapidly adopting automation platforms to gain a significant competitive advantage: the ability to deliver personalized content in real-time, optimize campaigns based on instantaneous data analytics, and dramatically improve lead conversion rates.
- This drive for hyper-efficiency, personalization at scale, and a measurable return on investment is fueling the marketing segment's position as the fastest-growing application area within the workflow automation market.
By Sector
- The IT & Telecommunications segment is expected to account for the largest share of 16% of the global workflow automation market.
- The IT & Telecommunications (IT & Telecom) segment's dominance in the workflow automation market is deeply rooted in its intrinsic role as both the primary user and the essential enabler of this technology.
- For IT departments, automation is a fundamental force multiplier, essential for managing the immense complexity and scale of modern digital infrastructure.
- This includes automating critical processes like network provisioning, server deployment, security patch management, and IT service desk ticketing.
- The telecommunications sector, in particular, relies on automation to manage vast networks, orchestrate customer onboarding, and dynamically allocate resources, processes that are impossible to handle manually at scale.
- This industry is characterized by rapid technological evolution and intense competition, where operational efficiency and the ability to launch services quickly are paramount.
- Consequently, IT & Telecom companies have been early and aggressive investors in automation, making it a core component of their operational DNA and securing its position as the largest application segment.
- However, the healthcare segment is witnessing rapid growth, at a CAGR of 24%, as it undergoes a profound and necessary digital transformation.
- Healthcare has traditionally been slower to adopt automation due to complex legacy systems, stringent data privacy regulations (like HIPAA), and a primary focus on patient care over administrative efficiency.
- However, the immense administrative burden within healthcare—spanning patient scheduling, claims processing, billing, records management, and regulatory compliance—has created a powerful catalyst for change.
- The industry is now rapidly turning to automation to address critical pain points: reducing skyrocketing operational costs, minimizing administrative errors that impact patient care and revenue, and improving the overall patient experience.
- The adoption of Electronic Health Records (EHRs) has created a digital foundation that automation can now build upon, integrating disparate systems to streamline workflows.
Geographic analysis
Asia-Pacific
Fastest growthIn 2025, Asia-Pacific is expected to account for the largest share of 34% of the global workflow automation market, followed by Europe, North America, Latin America, and the Middle East & Africa. Asia-Pacific’s significant market share can be attributed to various factors, such as the increasing emphasis on Industry 4.0 initiatives and digital transformation, the widespread adoption of robotic process automation and other advanced technologies, such as AI, robotics, IoT, and cloud computing, across various sectors, the rising number of government initiatives aimed at digitization, and the rising demand for cost-effective and efficient automation solutions to manage repetitive tasks. Moreover, Asia-Pacific is also projected to register the highest CAGR during the forecast period. Asia-Pacific to be the Fastest-growing Regional Market
Competitive landscape
- Business Machines Corporation
- Software AG
- Oracle Corporation
- Pegasystems Inc.
- Appian Corporation
- Newgen Software Technologies Limited
- Zapier, Inc.
- Formstack, LLC
- Microsoft Corporation
- Nintex Global Ltd.
- ServiceNow, Inc.
- IPsoft Inc.
- Amelia LLC
- Open Text Corporation
- SysAid Technologies Ltd.
- Jotform Inc.
- Kissflow Inc.
- Next Matter GmbH
- DocuWare GmbH
- Camunda Services GmbH
- HeightHQ, Inc.
- Integrify, Inc.
- Wrike, Inc.
- SAP SE
- Really Simple Systems Ltd.
Frequently asked questions
The workflow automation market is projected to reach $78.3 billion by 2035, at a CAGR of 21.0% during the forecast period.
Cite this report
Meticulous Research. (2025). Workflow Automation Market - Global Opportunity Analysis And Industry Forecast (2025-2035) (Report No. MRICT - 1041023). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/workflow-automation-market-5706