FPGA Market (2025-2032)
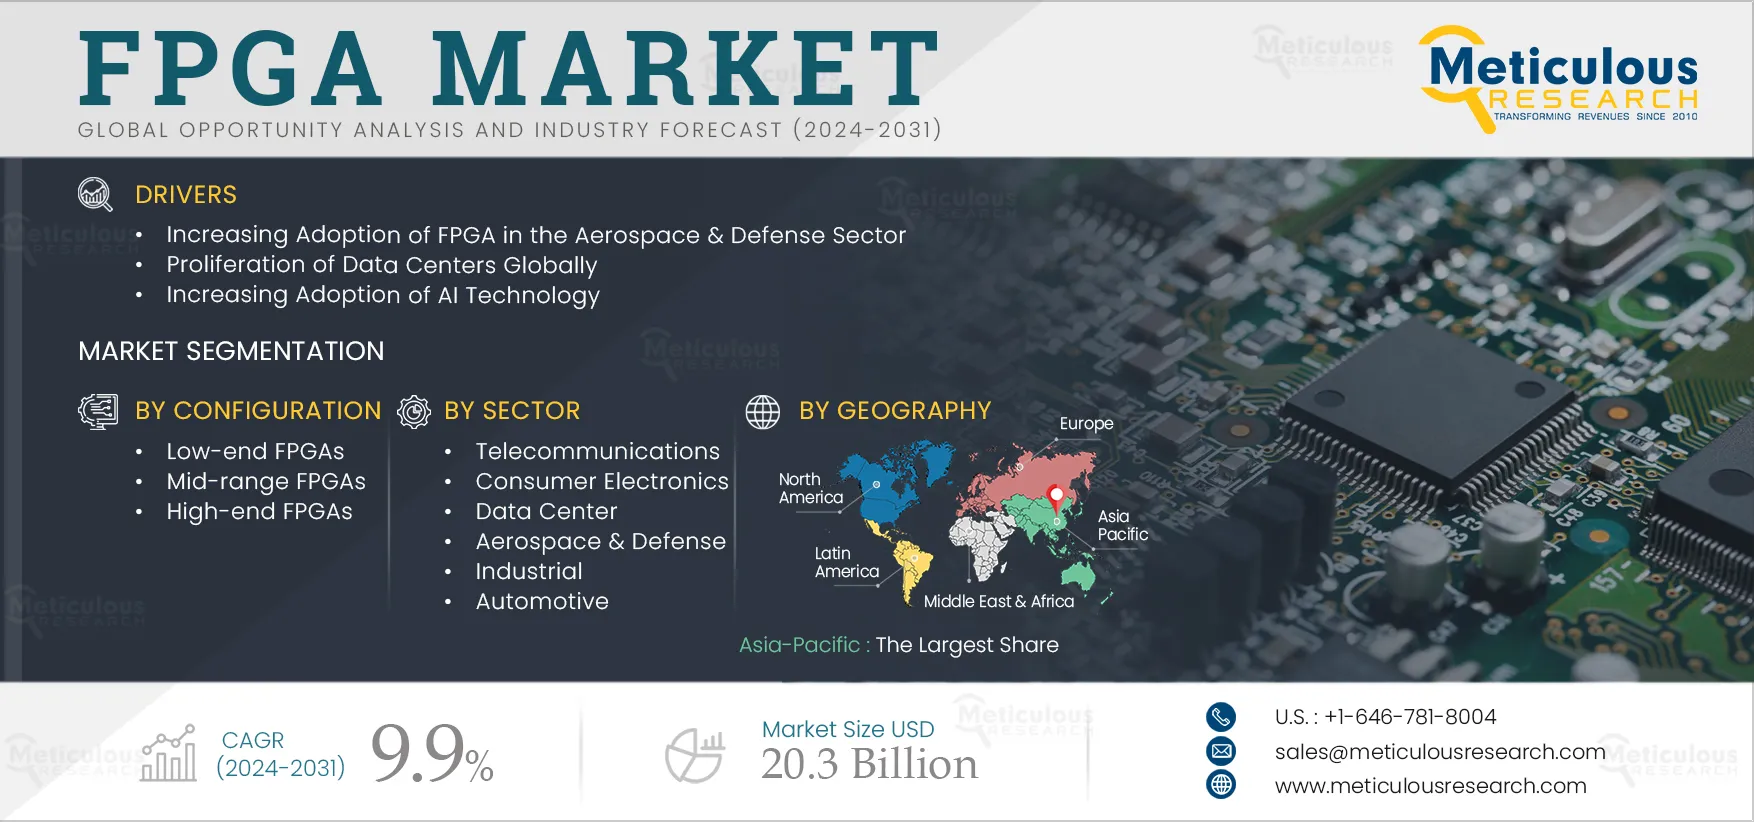
The FPGA Market is expected to reach $20.3 billion by 2032, at a CAGR of 9.9% from 2025 to 2032.
- Published
- May 2024
- Pages
- 250
- Format
- PDF + Excel
- Report ID
- MRSE - 1041154
- Base year
- 2024
- 2032 · FORECAST
- $20.30B
- 2032
- $20.30B
- CAGR 2025–2032
- 9.9%
2024 baseline · 2025–2032 forecast at 9.9% CAGR · hover a bar for the value
Key highlights
By Programming Technology: in 2025, the SRAM Segment to Dominate the FPGA Market
By Configuration: in 2025, the Low-end FPGAs Segment to Dominate the FPGA Market
By Node Size: in 2025, the Between 28-90 nm Segment to Dominate the FPGA Market
By Sector: in 2025, the Telecommunication Segment to Dominate the FPGA Market
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 250 |
| Format | |
| Forecast Period | 2025–2032 |
| Base Year | 2024 |
| CAGR (Value) | 9.9% |
| Market Size (Value) | USD 20.3 Billion by 2032 |
| Segments Covered | By Programming Technology · SRAM · Flash · Anti-fuse · By Configuration · Low-end FPGAs · Mid-range FPGAs · High-end FPGAs · By Node Size · Less than 28 nm · Between 28-90 nm · More than 90 nm · By Sector · Telecommunications · Consumer Electronics · Data Center · Aerospace & Defense · Industrial · Automotive · Healthcare · Other Sectors |
| Countries Covered | North America (U.S., Canada), Europe (Germany, U.K., France, Italy, Spain, Rest of Europe), Asia-Pacific (Japan, China, India, South Korea, Australia & New Zealand, Singapore, Rest of Asia-Pacific), Latin America (Mexico, Brazil, Rest of Latin America), and the Middle East & Africa (UAE, Israel, Rest of Middle East & Africa) |
| Key Companies | Qualcomm Technologies, Inc. (U.S.), Efinix, Inc. (U.S.), Advanced Micro Devices, Inc. (U.S.), QuickLogic Corporation (U.S.), Microchip Technology Inc. (U.S.), Intel Corporation (U.S.), GOWIN Semiconductor Corp. (China), Achronix Semiconductor Corporation (U.S.), S2C Limited. (U.S.), FlexLogix (U.S.), NVIDIA Corporation (U.S.), Broadcom Inc. (U.S.), Lattice Semiconductor Corporation (U.S.), Shanghai Anlogic Infotech Co., Ltd. (China), and NanoXplore SAS (France) |
Report overview
Segments covered: programming technology, configuration, node size, sector. Regions: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa.
The growth of the FPGA market is driven by the increasing adoption of FPGA in the aerospace & defense sector, the increasing adoption of AI technology, and the proliferation of data centers globally.
Furthermore, the integration of FPGA in cloud computing and infrastructure-as-a-service (IaaS) and the increasing integration of FPGA in consumer electronics are expected to create growth opportunities for the stakeholders in this market.
Report infographic
Market dynamics
5 factors across 3 forcesProliferation of Data Centers Globally
In recent years, enterprises have begun integrating complex systems to adapt to evolving customer demands. Across various sectors, organizations are decentralizing their IT workloads and turning to data centers to meet their network and IT infrastructure requirements. However, as data centers manage substantial data traffic along with compute-intensive tasks, traditional CPUs face challenges. They struggle to deliver the performance and efficiency required to handle increasing workloads. As a result, there is a rising demand for enhanced computing and data processing capabilities, particularly in fields such as artificial intelligence, machine learning, big data analytics, and high-performance computing.
FPGAs offer an excellent solution for enhancing computing power and streamlining data center operations due to their high degree of flexibility and programmability. They can be customized at the hardware level to align with the demands of specific workloads, making them well-suited for accelerating data center operations. Organizations are responding to the rising demand from data centers by providing FPGA solutions. For instance, in November 2021, Advanced Micro Devices, Inc. (U.S.) launched the Alveo U55C FPGA-based accelerator card designed specifically for HPC workloads and data centers. These advancements are expected to drive the growth of the FPGA market during the forecast period.
Increasing Adoption of AI Technology
The increasing adoption of Artificial Intelligence (AI) is driving the growth of the Field-Programmable Gate Array (FPGA) market, primarily due to its capacity to offer high-performance hardware acceleration for AI applications. With AI algorithms growing in complexity, traditional processors struggle to meet the computational demands, necessitating specialized hardware to manage the substantial data volumes requiring processing.
FPGAs, as programmable logic devices, are reconfigurable to execute specific tasks, rendering them well-suited for implementing custom logic designs tailored to AI applications. They can be programmed to execute specific AI algorithms, enabling parallel processing of tasks, a crucial capability for AI workloads demanding extensive parallelism. As AI adoption continues to rise, so does the demand for FPGAs to deliver high performance and low latency for AI applications. These factors are expected to drive the growth of the FPGA market during the forecast period.
Table of contents
12 chapters · 112 sections · 250 pages · click to expandSegmental analysis
| Segment | Largest share (2025) | Fastest growth (2025–2032) |
|---|---|---|
| By Programming Technology | SRAM | SRAM |
| By Configuration | Low-end FPGAs | High-end FPGAs |
| By Node Size | Between 28-90 nm | Between 28-90 nm |
| By Sector | Telecommunication | Aerospace & defense |
By Programming Technology
- The SRAM Segment to Dominate the FPGA Market
- The SRAM segment is expected to account for the largest share of over 44% of the global FPGA market.
- This segment's large market share can be attributed to the benefits offered by SRAM, including superior flexibility, re-programmability, easy integration, and high performance across a variety of applications.
- SRAM-based FPGAs are also less expensive to manufacture than flash-based counterparts, further driving their adoption across sectors such as aerospace & defense, consumer electronics, and telecommunications.
- In response to the increasing utilization of SRAM-based FPGAs, market players are launching initiatives to develop these FPGAs.
- For instance, in September 2024, GOWIN Semiconductor Corp. (China) partnered with Andes Technology Corporation (Taiwan) to develop an SRAM FPGA SoC featuring a hard-instantiated RISC-V core, enabling the utilization of both software and custom hardware within the same chip.
- Moreover, the SRAM segment is projected to register the highest CAGR during the forecast period.
By Configuration
- The Low-end FPGAs Segment to Dominate the FPGA Market
- The low-end FPGA segment is expected to account for the largest share of over 52% of the global FPGA market.
- This segment's large market share can be attributed to the affordability of low-end FPGAs, making them a more budget-friendly option for designers compared to high-end counterparts and the increasing utilization of low-end FPGAs across the telecommunications, automotive, industrial, consumer electronics, and medical sectors due to their efficiency in terms of power consumption.
- However, the high-end FPGAs segment is projected to register the highest CAGR during the forecast period.
- This segment's growth can be attributed to the increasing utilization of high-end FPGAs for data center acceleration, high-performance computing, and aerospace & defense applications.
- Furthermore, there is a growing demand for data processing and analytics in various sectors, such as finance, healthcare, and retail, which further drives the adoption of high-end FPGAs.
By Node Size
- The Between 28-90 nm Segment to Dominate the FPGA Market
- The between 28-90 nm segment is expected to account for the largest share of the global FPGA market.
- This segment's large market share can be attributed to the increasing use of 28-90 nm FPGA in battery-powered IoT devices and portable electronic devices and the increasing demand for 28-90 nm FPGA from manufacturers due to their affordability and high performance.
- Moreover, the between 28-90 nm segment is projected to register the highest CAGR of over 11.5% during the forecast period.
By Sector
- The Telecommunication Segment to Dominate the FPGA Market
- The telecommunications segment is expected to account for the largest share of over 32% of the global FPGA market.
- This segment's large market share can be attributed to the growing utilization of FPGAs in the telecommunications sector for various applications, including data packet switching, packet processing, and optical transport networks.
- Additionally, the rising adoption of Infrastructure as a Service (IaaS) among enterprises and the widespread adoption of 5G technology contribute to the growth of this segment.
- In response to this rising demand, market players are introducing various FPGAs tailored for the telecommunications sector.
- For instance, in March 2025, Advanced Micro Devices, Inc. (U.S.) launched the Spartan-7 series of Field-Programmable Gate Arrays (FPGAs) to address the rising need for customization, high performance, and flexible computing hardware in the telecommunications sector.
- However, the aerospace & defense segment is projected to register the highest CAGR during the forecast period.
- The segment's growth is attributed to the increasing use of FPGA for various applications such as radar and signal processing, image recognition for drones, and high-speed communication systems in military aircraft.
- Additionally, there is a growing demand for FPGAs to support critical military technologies capable of handling high data rates and complex signal processing requirements.
- In September 2024, Mercury Systems, Inc. (U.S.) launched the SCFE6933, a space-qualified FPGA processing board.
- This board integrates AMD's Xilinx Versal AI core to deliver high-performance computing for space applications.
Geographic analysis
Asia-Pacific
Largest shareIn 2025, Asia-Pacific is expected to account for the largest share of over 40% of the global FPGA market. Asia-Pacific's significant market share can be attributed to rapid technological advancements across various sectors, such as consumer electronics, automotive, telecommunications, and industrial automation in the region. Additionally, the increasing adoption of smart devices across industrial, residential, and commercial sectors, government initiatives aimed at promoting technological innovation and domestic chip production, and the rollout of 5G technology in the region contribute to the growth of this regional market. Furthermore, Asia-Pacific serves as a major hub for electronics manufacturing, facilitating faster design cycles and seamless integration of FPGAs into various electronic devices. Moreover, market players are launching various initiatives to cater to the rising demand in the region. For instance, in October 2021, Achronix Semiconductor Corporation (U.S.) signed an agreement with Nexcomm Asia (Singapore) to offer its high-performance FPGAs and embedded FPGA (eFPGA) IP solutions across India, Singapore, Malaysia, Thailand, Indonesia, and Vietnam. Moreover, the market in Asia-Pacific is projected to register the highest CAGR of over 11% during the forecast period.
Competitive landscape
- March 2025
Intel Corporation (U.S.) announced the official launch of Altera, its new standalone field-programmable gate array (FPGA) company. The company also unveiled its product roadmap and strategy to secure leadership in the high-growth FPGA space.
- September 2024
Logic Fruit Technologies (India), a leading product engineering and consulting service provider, entered into a partnership with AMD Xilinx (U.S.) to enhance FPGA innovation. With this collaboration, Logic Fruit Technologies becomes a premier partner with AMD Xilinx, empowering them to pioneer innovations and technologies in their latest advancements in FPGA technology that will benefit their global client base.
- August 2024
QuickLogic (U.S.) partnered up with YorChip (U.S.) to develop Low-Power, Low-Cost UCIe FPGA Chiplets. These chiplets are optimized for low power consumption and low cost, offering new possibilities for a wide range of applications, including the fast-growing edge IoT and AI/ML markets.
- April 2024
Xiphera, Ltd, a Finnish company specializing in designing and implementing hardware-based security solutions for Field Programmable Gate Arrays (FPGA) and Application Specific Integrated Circuits (ASIC), joined the partner program of Microchip Technology Inc. (U.S.), a leading provider of smart, connected, and secure embedded control solutions. Under this partnership, Xiphera becomes one of Microchip's FPGA Design Partners, leveraging their extensive knowledge and expertise in FPGAs and hardware-based security.
- Qualcomm Technologies, Inc. (U.S.)
- Efinix, Inc. (U.S.)
- Advanced Micro Devices, Inc. (U.S.)
- QuickLogic Corporation (U.S.)
- Microchip Technology Inc. (U.S.)
- Intel Corporation (U.S.)
- GOWIN Semiconductor Corp. · China
- Achronix Semiconductor Corporation (U.S.)
- S2C Limited. (U.S.)
- FlexLogix (U.S.)
- NVIDIA Corporation (U.S.)
- Broadcom Inc. (U.S.)
- Lattice Semiconductor Corporation (U.S.)
- Shanghai Anlogic Infotech Co., Ltd. · China
- NanoXplore SAS · France
Frequently asked questions
The FPGA (Field-Programmable Gate Array) market involves the use of programmable integrated circuits that can be configured to perform specific tasks, offering flexibility and high performance for various applications.
Cite this report
Meticulous Research. (2024). FPGA Market - Global Opportunity Analysis and Industry Forecast (2025-2032) (Report No. MRSE - 1041154). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/fpga-market-5837