Micro Data Centers Market (2025-2032)
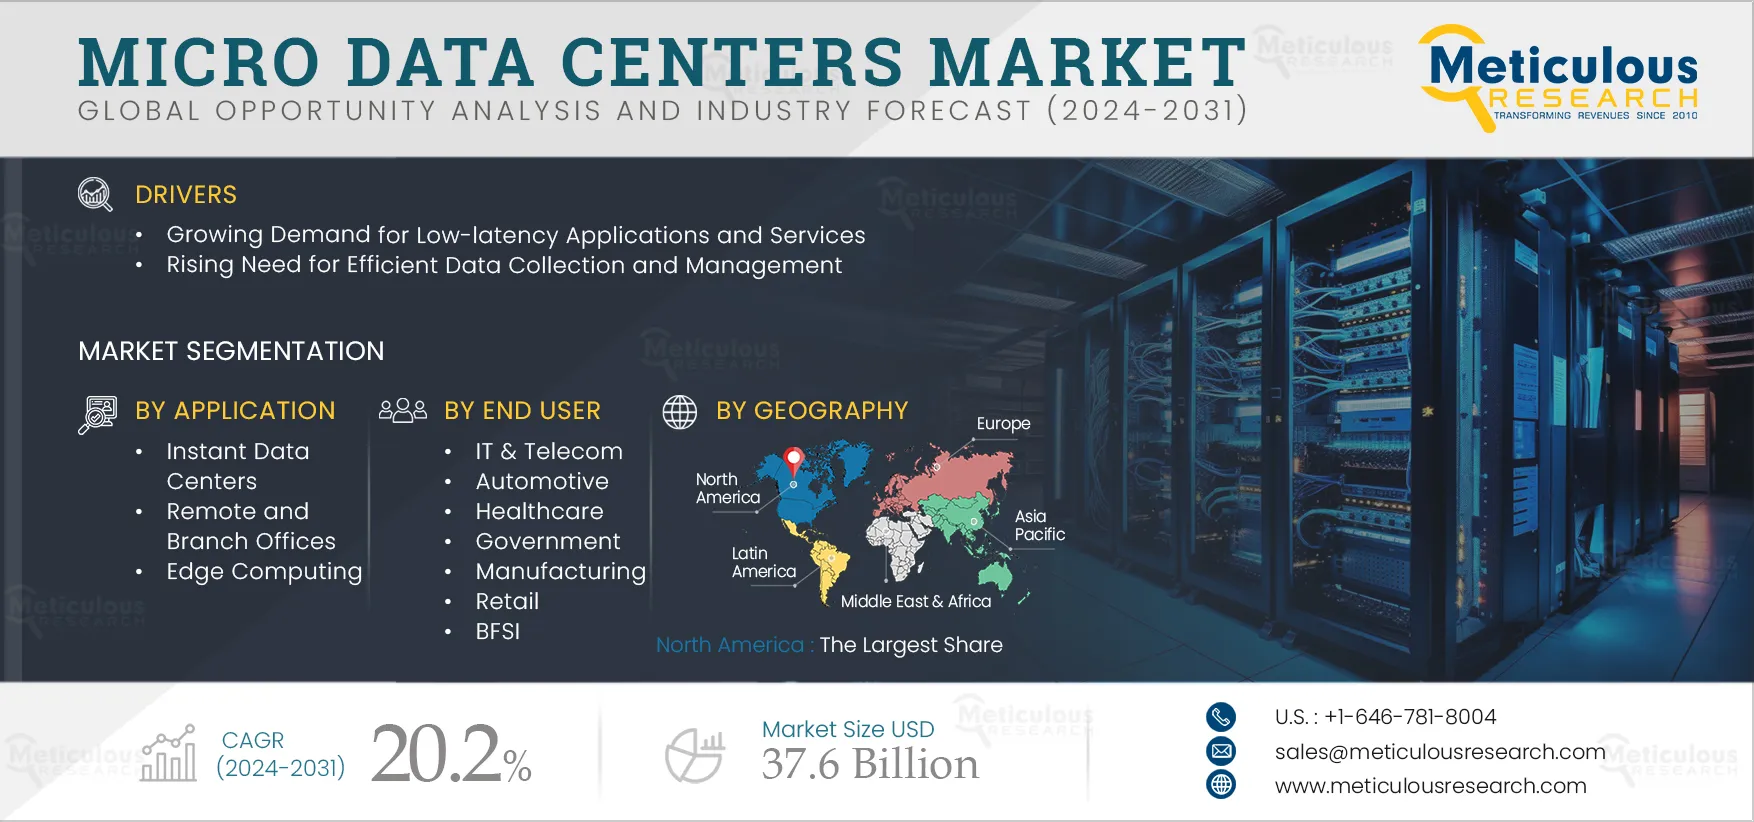
The Micro Data Centers Market is expected to reach $37.6 billion by 2032, at a CAGR of 20.2% from 2025 to 2032.
- Published
- May 2024
- Pages
- 300
- Format
- PDF + Excel
- Report ID
- MRICT - 1041175
- Base year
- 2024
- 2032 · FORECAST
- $37.60B
- 2032
- $37.60B
- CAGR 2025–2032
- 20.2%
2024 baseline · 2025–2032 forecast at 20.2% CAGR · hover a bar for the value
Key highlights
By Offering: In 2025, the Solutions Segment to Dominate the Micro Data Centers Market
By Organization Size: In 2025, the Large Enterprises Segment to Dominate the Micro Data Centers Market
By Application: In 2025, the Instant Data Centers Segment to Dominate the Micro Data Centers Market
By End User: In 2025, the IT & Telecom Segment to Dominate the Micro Data Centers Market
In 2025, North America Region to Dominate the Micro Data Centers Market
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 300 |
| Format | |
| Forecast Period | 2025–2032 |
| Base Year | 2024 |
| CAGR (Value) | 20.2% |
| Market Size (Value) | USD 37.6 Billion by 2032 |
| Segments Covered | By Offering · Solutions · Micro Data Centers · Indoor Micro Data Centers · Cabinet Micro Data Centers · Container Micro Data Centers · Other Micro Data Centers · Rack Units · Up to 20 RU · 20–40 RU · Above 40 RU · Services · Training & Support Services · Consulting Services · Installation & Deployment Services · Network Connectivity & Security Services · By Organization Size · Large Enterprises · Small & Medium-sized Enterprises · By Application · Instant Data Centers · Remote and Branch Offices · Edge Computing · Other Applications · By End User · IT & Telecom · Automotive · Healthcare · Transportation & Logistics · Government · Manufacturing · Retail · Energy & Utilities · BFSI · Other End Users |
| Countries Covered | North America (U.S., Canada), Europe (Germany, U.K., France, Italy, Netherlands, Spain, Sweden, and Rest of Europe), Asia-Pacific (China, India, Japan, South Korea, Singapore, Australia & New Zealand, Indonesia, and Rest of Asia-Pacific), Latin America (Brazil, Mexico, and Rest of Latin America), and the Middle East & Africa (Saudi Arabia, UAE, Israel, and Rest of the Middle East & Africa) |
| Key Companies | Schneider Electric SE (France), Vertiv Group Corporation (U.S.), Eaton Corporation plc (Ireland), Delta Electronics, Inc. (Taiwan), Hewlett Packard Enterprise (U.S.), IBM Corporation (U.S.), Huawei Digital Power Technologies Co., Ltd. (China), Hitachi Systems, Ltd. (Japan), Rittal GmbH & Co. KG (Germany), Dell Inc. (U.S.), Cannon Technologies Ltd (U.K.), Legrand SA (France), Shenzhen Kstar Science & Technology Co., Ltd. (China), Zella DC (Australia), Panduit Corp. (U.S.), Advanced Facilities, Inc. (U.S.), Attom Technology Inc. (U.S.), Sicon Chat Union Electric Co. (China), Stulz GmbH (Germany), and Dataracks t/a Stagwood Industries Ltd (U.K). |
Report overview
Segments covered: offering, organization size, application, end user. Regions: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa.
The growth of the micro data centers market is driven by the growing demand for low-latency applications and services and the rising need for efficient data collection and management. Furthermore, the proliferation of cloud-based services and IoT devices is expected to generate growth opportunities for the players operating in this market.
Report infographic
Market dynamics
4 factors across 3 forcesGrowing Demand for Low-latency Applications and Services
Low-latency applications and services refer to technology systems that process data in real time with very minimal delays. The adoption of low-latency applications and services to improve accuracy, enhance user experience, and increase competition has revolutionized the way businesses operate. Thus, micro data centers are ideal for low-latency applications because they process data locally and reduce the delay caused by transmitting data to distant data centers. Additionally, the use of micro data centers for low-latency applications helps businesses by reducing the risk associated with transmitting sensitive information over long distances.
Moreover, micro data centers provide scalability, reliability, and flexibility to meet the demand of edge computing and real-time data processing. Several companies are launching solutions for various geographic locations to serve content to users with minimal delay for low-latency connections. For instance, in April 2025, Nippon Telegraph and Telephone Corporation (Japan) launched a demonstration of All-Photonics Network (APN) driven hyper low-latency connections between data centers in the United States and the United Kingdom. Such growing developments help increase the demand for micro data centers for low-latency applications and services.
Rising Need for Efficient Data Collection and Management
Efficient data collection and management is important for organizations to make decisions and to optimize their data-related process. Thus, micro data centers (MDCs) are an effective solution for collecting and managing data, particularly in scenarios where data needs to be processed close to the edge. MDCs are deployed at the edge, near data sources like sensors, IoT devices, and other equipment. This proximity allows for efficient data collection with reduced latency. Additionally, In IoT-heavy environments, MDCs serve as localized data hubs, aggregating data from multiple devices and providing initial processing or filtering before sending data to a central system or cloud.
Moreover, MDCs have built-in storage capacity that allows them to store data locally. This is useful for scenarios where data needs to be retained for a specific duration before being transferred or processed further. Additionally, managing data locally with MDCs helps to improve security by keeping sensitive information on-site, reducing the risk of data breaches during transmission. Thus, micro data centers are a flexible and efficient solution for data collection and management that provides the ability to process data locally, improve security, and reduce latency.
Table of contents
12 chapters · 135 sections · 300 pages · click to expandSegmental analysis
| Segment | Largest share (2025) | Fastest growth (2025–2032) |
|---|---|---|
| By Offering | Solutions | — |
| By Organization Size | Large Enterprises | — |
| By Application | Instant Data Centers | Edge computing |
| By End User | Segment's large market share | Healthcare |
By Offering
- The Solutions Segment to Dominate the Micro Data Centers Market
- The solutions segment is expected to account for the larger share of above 62.0% of the micro data centers market.
- The segment's large market share is attributed to the growing need to replace computing resources closer to IoT devices to reduce latency for real-time data processing; the increasing adoption of micro data centers to enhance IT infrastructure's agility, performance, and resilience; the growing demand for low-latency applications and services; and the increasing demand for micro data centers in the telecom industry.
- Additionally, due to the increasing demand for high-density computing infrastructure for cloud infrastructure, several companies are launching micro data centers for private cloud companies.
- For instance, in March 2025, Avant Technologies, Inc. (U.S.) launched the first Avant-branded micro data center, which will be specifically designed for private cloud companies in the booming AI and big data sectors.
- However, the services segment is expected to register a higher CAGR during the forecast period.
- This growth is attributed to the growing use of micro data center services for rapid deployment and provision, which allow businesses to quickly adapt to changing business needs; the growing need to reduce capital expenditures and operational costs; and the growing need to implement robust security measures and compliance standards to protect customer data and regulatory compliance.
By Organization Size
- The large enterprises segment is expected to account for the larger share of above 58.0% of the micro data centers market.
- The segment's large market share is attributed to the growing adoption of MDCs in large enterprises to reduce the risk of physical breaches; the increasing use of advanced technologies such as IoT and AI for real-time processing; the increasing implementation of MDCs to reduce downtime and minimize the disruption to business operations during upgrades or repairs; and the rising need of MDCs to ensure data remains within specific jurisdictions, aiding compliance with data sovereignty regulations.
- However, the small & medium-sized enterprises segment is expected to register a higher CAGR during the forecast period.
- The growth of this segment is attributed to the growing adoption of MDCs to protect data and ensure compliance with industry regulations; the increasing use of MDCs in SMEs as scalable, flexible, and cost-effective solutions for IT infrastructure; MDCs’ redundancy features, such as backup power and data replication to reduces the risk of downtime; and MDC’s flexibility in terms of hardware and software configurations, allowing SMEs to tailor the infrastructure to their specific needs.
By Application
- The instant data centers segment is expected to account for the largest share of above 45.0% of the micro data centers market.
- The segment's large market share is attributed to the growing adoption of instant data centers due to easy installation and high portability across businesses; the increasing need for instant data centers for better service, more reliability, and less expense than traditional data centers; and the ability of low-latency compute capacity closer to applications, makes real-time data processing faster.
- However, the edge computing segment is expected to register a highest CAGR during the forecast period.
- The growth of this segment is attributed to the growing adoption of MDCs due to their ability to be located in close proximity to the point where data is generated; the implementation of MDCs at the edge to improve overall performance by ensuring greater bandwidth available for critical applications; and the rising adoption of MDC’s for edge computing help to enhance competitiveness and ability to offer real-time services and applications.
By End User
- The IT & Telecom Segment to Dominate the Micro Data Centers Market
- The IT & telecom segment is expected to account for the largest share of above 30.0% of the micro data centers market.
- The segment's large market share is attributed to the growing adoption of MDCs in IT & telecom to integrate new technology without disrupting existing systems; the growing adoption of 5G and IoT, the ability of MDCs to help telecom companies manage the increased data loads and complexity of modern networks; and the increasing adoption of MDCs in IT & telecom to improve security and compliance.
- However, the healthcare segment is expected to register the highest CAGR during the forecast period.
- The growth of this segment is attributed to the growing adoption of MDCs in healthcare due to their robust security features such as data encryption, access controls, and secure physical enclosures; the healthcare sector’s reliance on MDCs to minimize the risk of service disruptions; and the rise of telemedicine and remote patient monitoring, MDCs ensures robust connectivity and data processing for telehealth services.
Geographic analysis
North America
Largest shareIn 2025, North America is expected to account for the largest share of above 40.0% of the micro data centers market. North America’s significant market share can be attributed to the growing adoption of edge computing across businesses in the region; the increasing adoption of MDCs in retail to enhance consumer experience and improve logistics operations; and the rising need for efficient data collection and management in the region. Various companies are providing micro data center solutions for edge computing in the region. For instance, in October 2022, Vertiv Group Corporation (U.S.) launched the Vertiv SmartCabinet 2M, a self-contained micro data center designed for edge computing applications. In 2025, North America Region to Dominate the Micro Data Centers Market
Asia-Pacific
Fastest growthHowever, Asia-Pacific is expected to register the highest CAGR of above 22.0% during the forecast period. The growth of this market is attributed to the growing demand for low-latency applications and services across businesses in the region, the increasing government investment in MDCs to manage the increased data loads and complexity of modern networks, and the growing adoption of MDCs across SMEs in the region to protect data and ensure compliance with industry regulations.
Competitive landscape
The report offers a competitive analysis based on an extensive assessment of the leading players’ product portfolios, geographic presence, and key growth strategies adopted in the last 3–4 years. Some of the key players operating in the micro data centers market Schneider Electric SE (France), Vertiv Group Corporation (U.S.), Eaton Corporation plc (Ireland), Delta Electronics, Inc. (Taiwan), Hewlett Packard Enterprise (U.S.), IBM Corporation (U.S.), Huawei Digital Power Technologies Co., Ltd. (China), Hitachi Systems, Ltd. (Japan), Rittal GmbH & Co. KG (Germany), Dell Inc. (U.S.), Cannon Technologies Ltd (U.K.), Legrand SA (France), Shenzhen Kstar Science & Technology Co., Ltd. (China), Zella DC (Australia), Panduit Corp. (U.S.), Advanced Facilities, Inc. (U.S.), Attom Technology Inc. (U.S.), Sicon Chat Union Electric Co. (China), Stulz GmbH (Germany), and Dataracks t/a Stagwood Industries Ltd (U.K).
- April 2025
Vertiv Group Corporation (U.S.) launched Vertiv SmartAisle 3, a micro modular data center system that utilizes Artificial Intelligence (AI) to provide enhanced intelligence and enable efficient operations within the data center environment.
- October 2024
Prose Technologies Co. Ltd. (Ireland) launched the Khipu Micro Data Center. Khipu Micro Data Center includes energy-efficient operations, space-saving design, smart cloud-based management, robust security measures, and cost-effective installations.
- Schneider Electric SE · France
- Vertiv Group Corporation (U.S.)
- Eaton Corporation plc · Ireland
- Delta Electronics, Inc. · Taiwan
- Hewlett Packard Enterprise (U.S.)
- IBM Corporation (U.S.)
- Huawei Digital Power Technologies Co., Ltd. · China
- Hitachi Systems, Ltd. · Japan
- Rittal GmbH & Co. KG · Germany
- Dell Inc. (U.S.)
- Cannon Technologies Ltd (U.K.)
- Legrand SA · France
- Shenzhen Kstar Science & Technology Co., Ltd. · China
- Zella DC · Australia
- Panduit Corp. (U.S.)
- Advanced Facilities, Inc. (U.S.)
- Attom Technology Inc. (U.S.)
- Sicon Chat Union Electric Co. · China
- Stulz GmbH · Germany
- Dataracks t/a Stagwood Industries Ltd (U.K)
Frequently asked questions
The micro data centers market study focuses on market assessment and opportunity analysis through the sales of micro data centers across different regions and countries across different market segmentations. This study is also focused on competitive analysis for micro data centers based on an extensive assessment of the leading players’ product portfolios, geographic presence, and key growth strategies.
Cite this report
Meticulous Research. (2024). Micro Data Centers Market - Global Opportunity Analysis and Industry Forecast (2025-2032) (Report No. MRICT - 1041175). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/micro-data-centers-market-5858