ADAS Market (2024-2031)
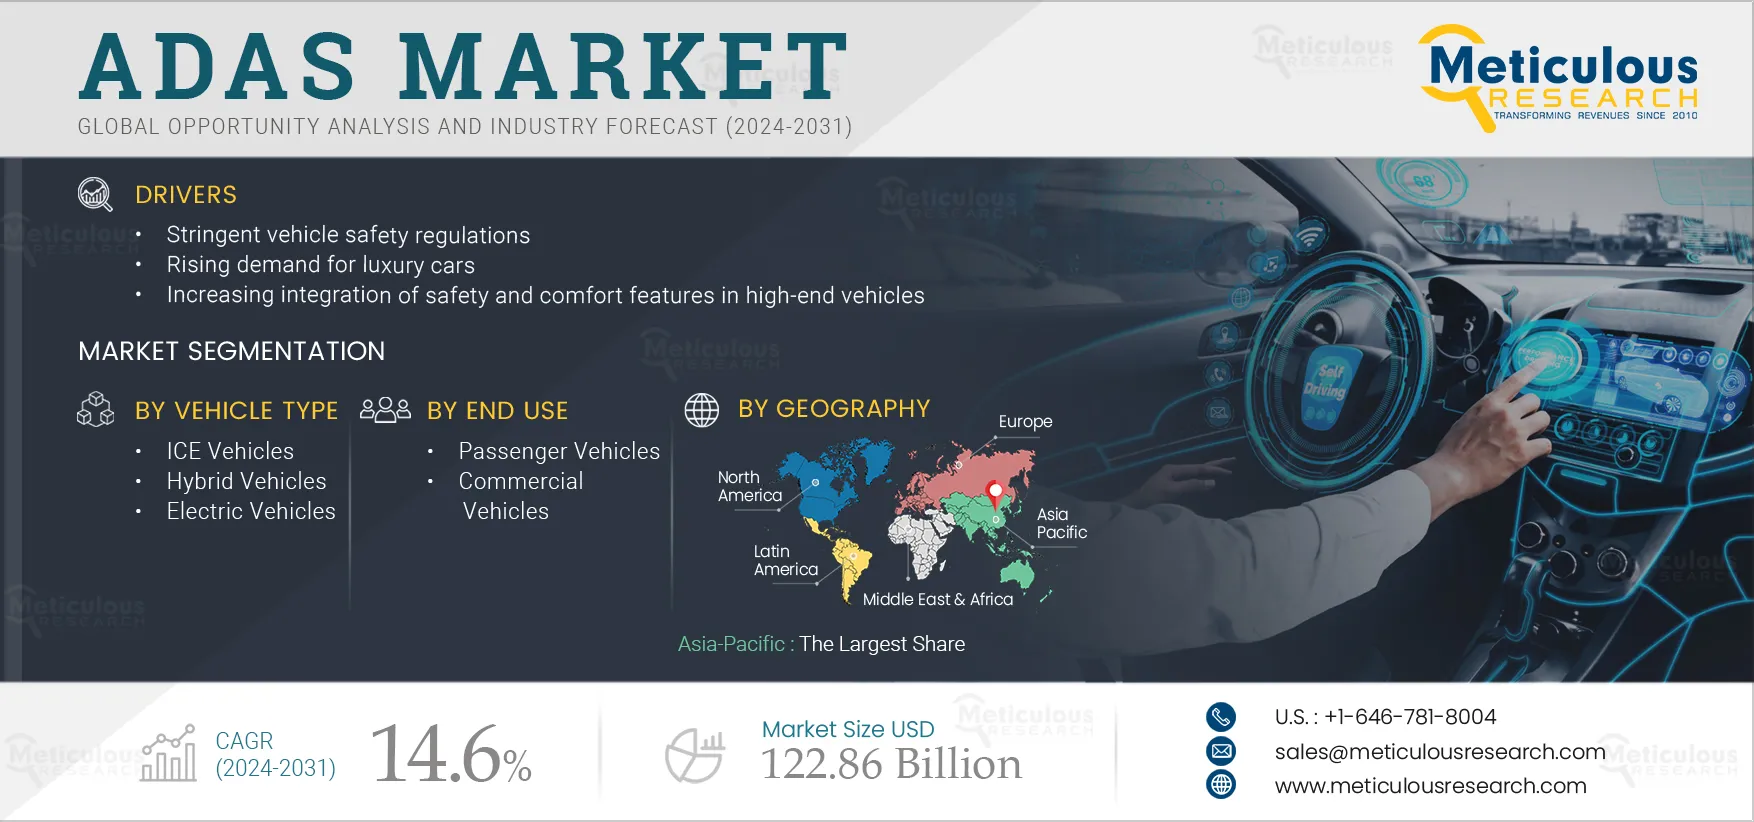
The ADAS Market is expected to reach $122.86 billion by 2031, at a CAGR of 14.6% from 2024 to 2031.
- Published
- Jan 2024
- Pages
- 267
- Format
- PDF + Excel
- Report ID
- MRAUTO - 104693
- Base year
- 2023
- 2031 · FORECAST
- $122.9B
- 2031
- $122.9B
- CAGR 2024–2031
- 14.6%
2023 baseline · 2024–2031 forecast at 14.6% CAGR · hover a bar for the value
Key highlights
By System Type: In 2024, the Adaptive Cruise Control Systems Segment to Dominate the ADAS Market
By Level of Automation: In 2024, the Level 1 Segment to Dominate the ADAS Market
By Component: In 2024, the Sensors Segment to Dominate the ADAS Market
By Vehicle Type: In 2024, the Internal Combustion Engine Vehicles Segment to Dominate the ADAS Market
By End Use: In 2024, the Passenger Vehicles Segment to Dominate the ADAS Market
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 267 |
| Format | |
| Forecast Period | 2024–2031 |
| Base Year | 2023 |
| CAGR (Value) | 14.6% |
| Market Size (Value) | USD 122.86 Billion by 2031 |
| Segments Covered | By System Type · Blind Spot Detection Systems · Parking Assistance Systems · Lane Departure Warning Systems · Adaptive Front-Lighting Systems · Forward Collision Warning Systems · Driver Monitoring Systems · Night Vision Systems · Adaptive Cruise Control Systems · Automatic Emergency Braking Systems · Tire Pressure Monitoring Systems · Traffic Sign Recognition Systems · Pedestrian Detection Systems · Traffic Jam Assistance Systems · By Level of Automation · Level 1 · Level 2 · Level 3 · By Component · Vision Camera Systems · Sensors · LiDAR · Radar · Ultrasonic Sensors · GPS/GNSS Sensors · ECU · Software · Actuators · By Vehicle Type · ICE Vehicles · Petrol Vehicles · Diesel Vehicles · CNG Vehicles · Other Vehicles · Hybrid Vehicles · Pure Hybrid Vehicles · Plug-in Hybrid Vehicles · Electric Vehicles · By End Use · Passenger Vehicles · Commercial Vehicles · Light Commercial Vehicles · Heavy Commercial Vehicles |
| Countries Covered | North America (U.S., Canada), Europe (Germany, France, U.K., Russia, Sweden, Netherlands, Italy, Spain, Denmark, and Rest of Europe), Asia-Pacific (China, India, Japan, South Korea, Indonesia, Thailand, and Rest of Asia-Pacific), Latin America, and the Middle East & Africa |
| Key Companies | Continental AG (Germany), Valeo SA (France), Robert Bosch GmbH (Germany), ZF Friedrichshafen AG (Germany), and Aptiv PLC (Ireland), Autoliv, Inc. (Sweden), Denso Corporation (Japan), Garmin Ltd. (U.S.), Infineon Technologies AG (Germany), Magna International Inc. (Canada), Mobileye B.V. (Israel), Huawei Technologies Co., Ltd. (China), Qualcomm Technologies, Inc. (U.S.), Microsoft (U.S.), and NXP Semiconductors N.V. (Netherlands). |
Report overview
Segments covered: type, automation, component, vehicle, end use. Regions: North America, Europe, Asia-Pacific.
The growth of the ADAS market is driven by stringent vehicle safety regulations, the rising demand for luxury cars, and the increasing integration of safety and comfort features in high-end vehicles. Moreover, the emergence of autonomous vehicles, increasing developments in the autonomous shared mobility space, and the rising adoption of electric vehicles are expected to generate market growth opportunities.
Report infographic
Market dynamics
2 factors across 2 forcesIncreasing Integration of Safety and Comfort Features in High-end Vehicles
ADAS technology aims to reduce human errors that may lead to vehicle accidents. ADAS operates both actively and passively, alerting the driver of a potential collision or braking and steering the vehicle. Due to its dynamic nature, regulating ADAS is a constant challenge globally. Therefore, safety standards need to remain flexible to accommodate the evolution of ADAS technologies. For example, the regulatory environment in the U.S. has fostered innovation and growth in the field of partially and fully autonomous vehicles. However, the safety of certain ADAS technologies has not been fully evaluated. Hence, regulators are focused on ensuring that ADAS technologies integrated into cars improve vehicle safety & comfort.
Table of contents
13 chapters · 120 sections · 267 pages · click to expandSegmental analysis
| Segment | Largest share (2024) | Fastest growth (2024–2031) |
|---|---|---|
| By System Type | Adaptive Cruise Control Systems | Blind spot detection systems |
| By Level of Automation | Level 1 | Level 3 |
| By Component | Sensors | Sensors |
| By Vehicle Type | Internal Combustion Engine Vehicles | Electric vehicles |
| By End Use | Passenger Vehicles | Commercial vehicles |
By System Type
- The adaptive cruise control systems segment is expected to account for the largest share of 15.4% of the market.
- The growth of this segment is mainly attributed to the need to maintain a comfortable driving experience, supportive government regulations, and advancements in adaptive cruise control systems.
- However, the blind spot detection systems segment is projected to register the highest CAGR during the forecast period.
- The growth of this segment is attributed to the expanding e-commerce and logistics sector, the increasing adoption of BSD systems in vehicles, and the rising use of complementary metal oxide semiconductors (CMOS) image sensors.
By Level of Automation
- The Level 1 Segment to Dominate the ADAS Market
- The level 1 segment is expected to account for the largest share of 57.7% of the market.
- The growth of this segment is attributed to the growing investments in vehicle electrification, the rising demand for driver assistance systems, and the increasing number of Level 1 vehicles on the road.
- However, the level 3 segment is projected to register the highest CAGR during the forecast period.
- The growth of this segment is attributed to the rising demand for self-driving vehicles and the increasing initiatives by major market players aimed at launching advanced Level 3 autonomous cars.
By Component
- The Sensors Segment to Dominate the ADAS Market
- The sensors segment is expected to account for the largest share of 49.0% of the market.
- However, the sensors segment is projected to register the highest CAGR during the forecast period.
- The growth of this segment is attributed to the rising need to reduce greenhouse gas emissions and the increasing demand for sensors in hybrid powertrains.
- Also, this segment is projected to register the highest CAGR during the forecast period.
By Vehicle Type
- The internal combustion engine vehicles segment is expected to account for the largest share of 46.0% of the market.
- Internal combustion engine (ICE) vehicles are automobiles that use an internal combustion engine (ICE) to power the vehicle.
- ICEs are typically powered by fossil fuels such as gasoline or diesel, but they can also be powered by alternative fuels such as ethanol or compressed natural gas.
- ICE vehicles have been the dominant form of transportation for the past century.
- However, the electric vehicles segment is projected to register the highest CAGR during the forecast period.
- The supportive government policies and regulations, increasing investments by leading automotive OEMs, rising environmental concerns, decreasing prices of batteries, and advancements in charging technologies are the key factors driving the growth of electric vehicles in the ADAS market.
By End Use
- The passenger vehicles segment is expected to account for the larger share of 70.7% of the ADAS market.
- The growth of this segment is attributed to the growing awareness regarding the hazards associated with greenhouse gas emissions and environmental pollution, stringent emission norms, and demand for premium cars among consumers.
- However, the commercial vehicles segment is projected to register the highest CAGR during the forecast period.
- The growth of this segment is attributed to the increase in fuel prices and stringent emission norms set by governments, the growing adoption of autonomous delivery vehicles, and the increasing adoption of electric buses and trucks.
Geographic analysis
Asia-Pacific
Largest shareIn 2024, Asia-Pacific is expected to account for the largest share of 58.7% of the global ADAS market. In 2024, Asia-Pacific ADAS market is projected to be worth of USD 27.8 billion. The region's significant market share is attributed to the growing automotive manufacturing sector in countries such as Japan, China, India, and South Korea, supportive government regulations, and the rising popularity of Electric Vehicles (EVs). In 2024, Asia-Pacific Region to Dominate the ADAS Market
Europe
Fastest growthHowever, Europe is expected to command the highest CAGR of the global ADAS market. The market growth in the region is attributed to the huge presence of component manufacturers, the growth of the overall automotive sector, and the high demand for sensors for automated vehicle prototypes.
Competitive landscape
The report offers a competitive analysis based on an extensive assessment of the leading players’ product portfolios, geographic presence, and key growth strategies adopted in the last 3–4 years. Some of the key players operating in the ADAS market Continental AG (Germany), Valeo SA (France), Robert Bosch GmbH (Germany), ZF Friedrichshafen AG (Germany), and Aptiv PLC (Ireland), Autoliv, Inc. (Sweden), Denso Corporation (Japan), Garmin Ltd. (U.S.), Infineon Technologies AG (Germany), Magna International Inc. (Canada), Mobileye B.V. (Israel), Huawei Technologies Co., Ltd. (China), Qualcomm Technologies, Inc. (U.S.), Microsoft (U.S.), and NXP Semiconductors N.V. (Netherlands).
- May 2023
Infineon (Germany) and Hon Hai Technology Group (Taiwan) signed a MoU to partner on SiC collaboration and leverage respective expertise in EV development, including smart cabin applications, advanced driver assistance systems, and autonomous driving applications.
- April 2023
Continental AG (Germany) and HERE (Netherlands) partnered with IVECO (Netherlands) to increase safety, fuel-saving, and ADAS functions in commercial vehicles.
- January 2023
Mobileye (Israel) collaborated with Wistron NeWeb Corp. (WNC) (Taiwan) for the production of Mobileye’s software-defined imaging radars, which, according to the company, could be more advanced and alternative to LiDAR solutions, which were typically more expensive.
- April 2021
DENSO Corporation (Japan) launched products for Advanced Drive, an advanced driver assistance technology featured on the new Lexus LS and the new Toyota Mirai, released in Japan in April 2021.
- Continental AG · Germany
- Valeo SA · France
- Robert Bosch GmbH · Germany
- ZF Friedrichshafen AG · Germany
- Aptiv PLC · Ireland
- Autoliv, Inc. · Sweden
- Denso Corporation · Japan
- Garmin Ltd. (U.S.)
- Infineon Technologies AG · Germany
- Magna International Inc. · Canada
- Mobileye B.V. · Israel
- Huawei Technologies Co., Ltd. · China
- Qualcomm Technologies, Inc. (U.S.)
- Microsoft (U.S.)
- NXP Semiconductors N.V. · Netherlands
Frequently asked questions
The ADAS market study focuses on the market assessment and opportunity analysis through the sales of ADAS across different region, and countries across different market segmentation, this study is also focused on competitive analysis for ADAS based on an extensive assessment of the leading players’ product portfolios, geographic presence, and key growth strategies.
Cite this report
Meticulous Research. (2024). ADAS Market - Global Opportunity Analysis And Industry Forecast (2024-2031) (Report No. MRAUTO - 104693). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/adas-market-5377