Driver Monitoring Systems (DMS) Market (2026-2036)
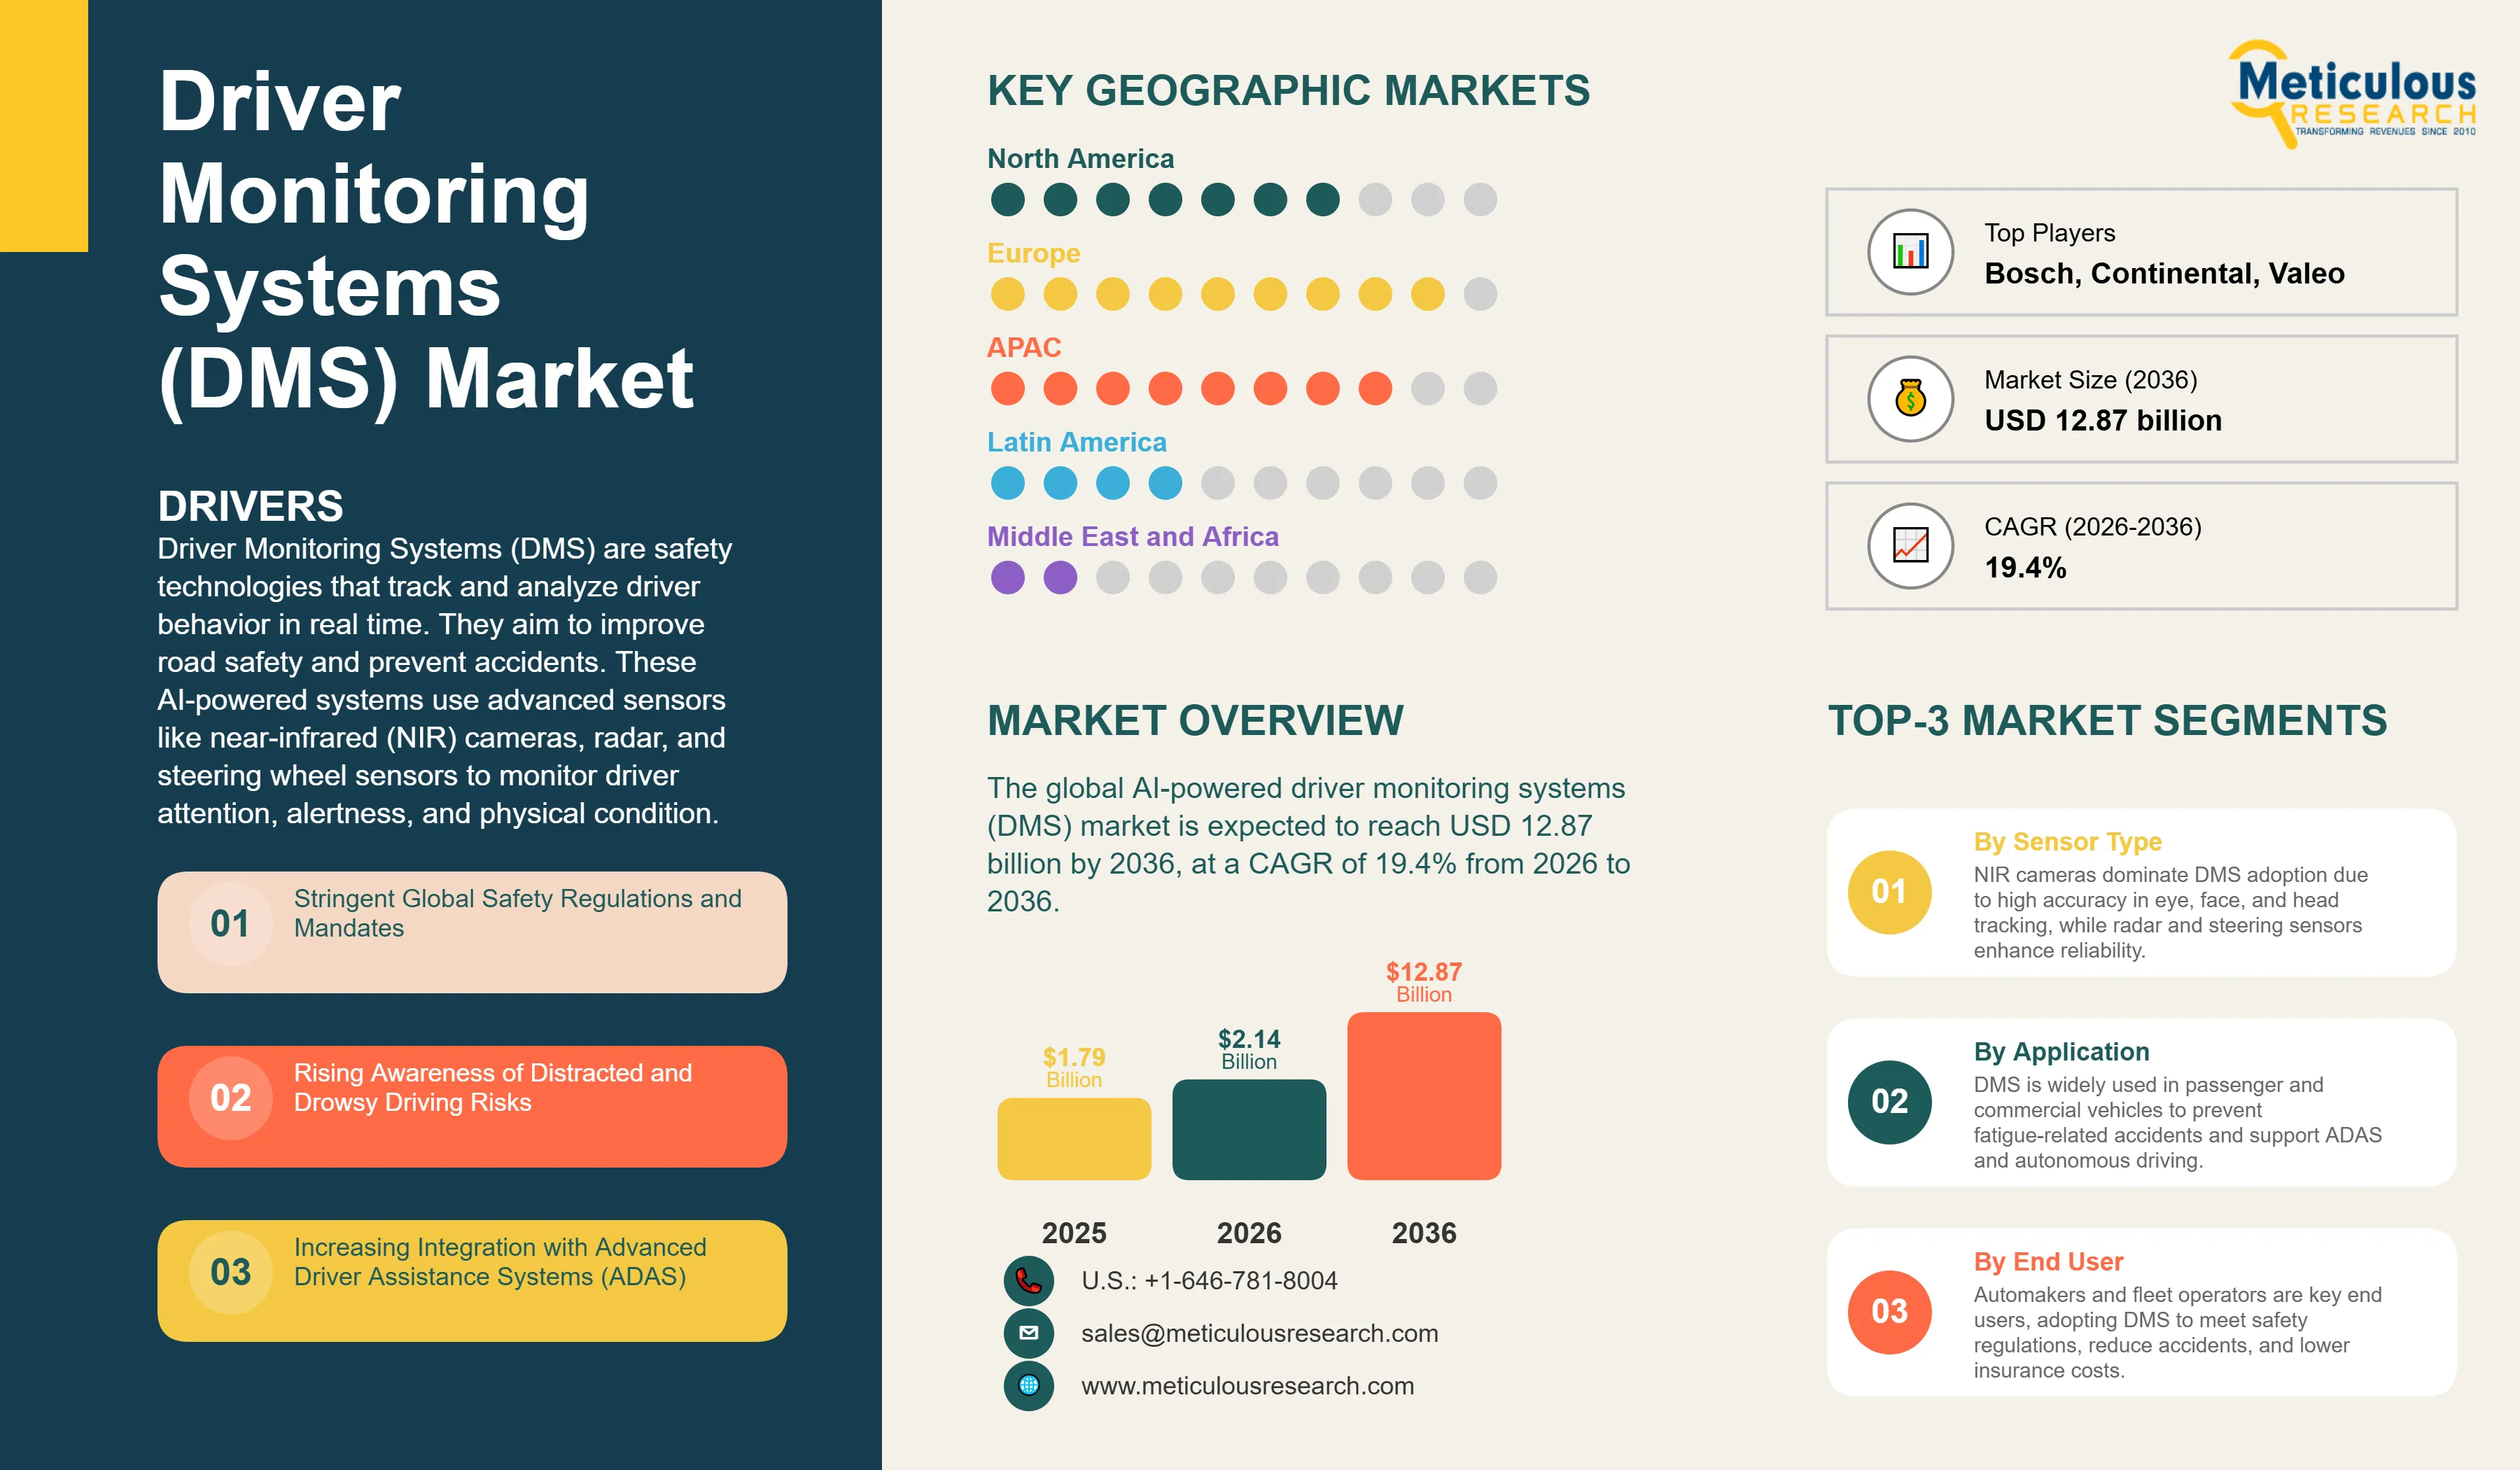
The global AI-powered driver monitoring systems (DMS) market is expected to reach USD 12.87 billion by 2036 from USD 2.14 billion in 2026, at a CAGR of 19.4% from 2026 to 2036.
- Published
- Jan 2026
- Pages
- 240
- Format
- PDF + Excel
- Report ID
- MR-1645
- Base year
- 2025
- 2026 · ESTIMATED
- $2.14B
- 2036
- $12.87B
- CAGR 2026–2036
- 19.4%
2025 baseline · 2026–2036 forecast at 19.4% CAGR · hover a bar for the value
Key highlights
In 2026, Europe is estimated to account for the largest share of the global driver monitoring systems market, driven by stringent regulatory mandates including the EU's General Safety Regulation (GSR) requiring DMS in all new vehicles starting July 2024.
Asia-Pacific is projected to register the highest CAGR during the forecast period, fueled by rapidly growing automotive production, increasing adoption of advanced safety features, and rising awareness of road safety in emerging economies.
Based on sensor type, the NIR camera segment is estimated to hold the largest share of the market in 2026, driven by its superior accuracy in detecting facial features, eye movements, and head position under various lighting conditions.
Based on AI algorithm, the drowsiness detection segment is estimated to dominate the market in 2026, owing to its critical role in preventing fatigue-related accidents and widespread regulatory focus on driver alertness monitoring.
Based on regulatory compliance, the Euro NCAP-compliant segment is expected to witness significant growth during the forecast period, driven by the rating system's influence on consumer purchasing decisions and automaker priorities.
Based on OEM integration, the passenger vehicle segment is expected to account for the largest share of the market in 2026, fueled by mandatory safety regulations and growing consumer demand for advanced driver assistance systems (ADAS).
The commercial vehicle segment is expected to grow at a significant CAGR during the forecast period, driven by fleet operators' focus on driver safety, insurance cost reduction, and regulatory compliance.
The U.S. driver monitoring systems market is projected to grow at a CAGR of around 18% during the forecast period 2026 to 2036, driven by increasing NHTSA safety initiatives and voluntary adoption by major automakers.
China is expected to lead the Asia-Pacific driver monitoring systems market, driven by massive automotive production volumes, government road safety initiatives, and rapid EV market expansion requiring advanced safety features.
In 2026, Germany is projected to account for the largest share of the European driver monitoring systems market, driven by its premium automotive segment and early adoption of advanced safety technologies by manufacturers like BMW, Mercedes-Benz, and Audi.
Report summary
| Particulars | Details |
|---|---|
| Market Size Value in 2026 | USD 2.14 Billion |
| Revenue Forecast in 2036 | USD 12.87 Billion |
| Growth Rate | CAGR of 19.4% from 2026 to 2036 |
| Format | PDF, Excel & Cloud Portal · 240 pages |
| Base Year for Estimation | 2025 |
| Historical Data | 2021–2025 |
| Forecast Period | 2026–2036 |
| Quantitative Units | Revenue in USD Billion and CAGR from 2026 to 2036 |
| Report Coverage | Revenue forecast, company ranking, competitive landscape, growth factors, and trends |
| Segments Covered | Sensor Type, AI Algorithm, Regulatory Compliance, OEM Integration, Vehicle Type, Region |
| Regional Scope | North America, Europe, Asia-Pacific, Latin America, Middle East & Africa |
| Countries Covered | U.S., Canada, Germany, U.K., France, Italy, Spain, Sweden, China, Japan, South Korea, India, Australia, Brazil, Mexico, Saudi Arabia, UAE, South Africa |
| Key Companies Profiled | Bosch GmbH, Continental AG, Denso Corporation, Valeo SA, Aptiv PLC, Magna International Inc., Visteon Corporation, Seeing Machines Limited, Smart Eye AB, Tobii AB, Jungo Connectivity Ltd., Cipia Vision Ltd., Eyeris Technologies Inc., Affectiva Inc. (Smart Eye), Hyundai Mobis Co. Ltd., LG Innotek Co. Ltd., Panasonic Automotive Systems Co. Ltd., Gentex Corporation, Faurecia SE (FORVIA), Harman International (Samsung Electronics) |
Report overview
Segments covered: sensor type, ai algorithm, oem integration, regulatory compliance.
Driver Monitoring Systems (DMS) are safety technologies that track and analyze driver behavior in real time. They aim to improve road safety and prevent accidents. These AI-powered systems use advanced sensors like near-infrared (NIR) cameras, radar, and steering wheel sensors to monitor driver attention, alertness, and physical condition. DMS can identify signs of drowsiness, distraction, cognitive impairment, and other risk factors that threaten driving safety. The system provides real-time alerts and interventions, including visual and sound warnings as well as active vehicle control measures. This helps ensure that drivers stay focused and can operate their vehicles safely.
Driver Monitoring Systems mark an important change in automotive safety technology. They move away from traditional passive safety features to proactive, AI-driven systems. These smart systems act like a co-pilot, constantly checking the driver's mental and physical state to prevent accidents before they happen. By using advanced sensor technology and machine learning algorithms, DMS builds a solid safety net that tackles one of the biggest causes of road accidents: human error from distraction, drowsiness, or impairment.
Several important trends are changing the driver monitoring systems market. These include stricter global safety regulations that require DMS installation, quick advancements in artificial intelligence and computer vision technologies, the rise of semi-autonomous and autonomous vehicles needing human-machine handover protocols, and the integration of DMS with larger vehicle safety systems. The mix of regulatory pressure, technology maturity, and increasing consumer awareness of road safety has turned DMS from a luxury feature into a crucial part of modern vehicle safety.
The combination of DMS and autonomous driving technologies is opening up new uses and market possibilities. As vehicles move through different levels of autonomy, DMS is crucial for managing the shift between automated and manual driving modes. It ensures that drivers stay alert and can take control when needed. This feature is vital for Level 2 and Level 3 autonomous systems, leading to significant investments in DMS technology.
Connecting with larger vehicle communication networks is widening DMS capabilities beyond alerts within the vehicle. Modern systems can interact with fleet management platforms, insurance tracking systems, and even emergency services. This creates better safety and risk management solutions. The connectivity allows for proactive interventions, data-driven safety improvements, and new business approaches centered around usage-based insurance and fleet safety management.
Report infographic
Market dynamics
7 factors across 3 forcesStringent Global Safety Regulations and Mandates
Regulatory requirements are pushing the adoption of DMS in automotive markets around the world. The European Union's General Safety Regulation (GSR), effective in July 2024, requires driver drowsiness and attention warning systems in all new vehicle types. This regulation creates a significant market for DMS technology. It demands systems that can detect driver inattention and fatigue, along with standards that ensure real safety improvements. Other markets are seeing similar initiatives, with the United States National Highway Traffic Safety Administration (NHTSA) considering DMS mandates as part of a broader approach to advanced driver assistance systems (ADAS). The Euro NCAP safety rating system has also added DMS assessment to its testing protocols, encouraging automakers to adopt advanced systems for better safety ratings and competitive market advantages.
Rising Awareness of Distracted and Drowsy Driving Risks
Growing recognition of human factors as the main cause of road accidents is increasing the demand for proactive safety measures. The National Highway Traffic Safety Administration reports that drowsy driving led to around 91,000 police-reported crashes in 2017, resulting in nearly 50,000 injuries and 800 deaths in the United States. Distracted driving remains a serious safety issue as well; the NHTSA stated that 3,142 people died in motor vehicle crashes involving distracted drivers in 2020. These alarming figures have raised awareness among consumers, fleet operators, and insurance companies about how DMS technology can prevent accidents, lower liability, and save lives. Commercial fleet operators are quickly adopting DMS to protect drivers, lower accident rates, reduce insurance costs, and show compliance with duty of care.
Table of contents
14 chapters · 156 sections · 240 pages · click to expandGeographic analysis
Europe
Largest shareIn 2026, Europe is expected to hold the largest share of the global driver monitoring systems market. This leadership comes from its strong regulations that require DMS installation in all new vehicles, a robust automotive safety culture, and the presence of premium car manufacturers that focus on improved safety technologies. The influence of Euro NCAP safety ratings also encourages better DMS use. Germany leads the region thanks to its concentration of premium car makers like BMW, Mercedes-Benz, Audi, and Porsche, which have adopted driver monitoring technology early and continue to innovate.
Asia-Pacific
The Asia-Pacific region is expected to grow at the highest rate during the forecast period. This growth is due to rapidly expanding automotive production, a rising middle class seeking better safety features, increased government attention to road safety, and the large shift to electric vehicles that include the latest safety technologies. China, as the largest automotive market in the world and backed by government efforts to promote intelligent connected vehicles and advanced driver assistance systems, will significantly boost regional growth. Japan and South Korea will also play a key role in this expansion, thanks to their advanced automotive industries and key DMS technology suppliers.
North America
North America is a notable market fueled by growing safety awareness, proactive automaker actions ahead of possible regulations, strong consumer interest in advanced safety features, and the presence of major tech firms working on AI and computer vision solutions. In the United States, major automakers are voluntarily adopting DMS as part of their safety strategies. Organizations like the Insurance Institute for Highway Safety (IIHS) and NHTSA provide guidance and incentives for this implementation.
Competitive landscape
- Bosch GmbH · Germany
- Continental AG · Germany
- Denso Corporation · Japan
- Valeo SA · France
- Aptiv PLC · Ireland
- Magna International Inc. · Canada
- Visteon Corporation (U.S.)
- Seeing Machines Limited · Australia
- Smart Eye AB · Sweden
- Tobii AB · Sweden
- Jungo Connectivity Ltd. · Israel
- Cipia Vision Ltd. · Israel
- Eyeris Technologies Inc. (U.S.)
- Hyundai Mobis Co. Ltd. · South Korea
- LG Innotek Co. Ltd. · South Korea
- Panasonic Automotive Systems Co. Ltd. · Japan
- Gentex Corporation (U.S.)
- Faurecia SE (FORVIA) · France
- Harman International (Samsung Electronics) · South Korea
Frequently asked questions
The AI-powered driver monitoring systems market is expected to grow from USD 2.14 billion in 2026 to USD 12.87 billion by 2036.
Cite this report
Meticulous Research. (2026). Driver Monitoring Systems (DMS) Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MR-1645). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/driver-monitoring-systems-market-6328