Radar Market (2022-2029)
The Radar Market is projected to reach $38.4 billion by 2029, at a CAGR of 7.6% from 2022 to 2029.
- Published
- Nov 2022
- Pages
- 300
- Format
- PDF + Excel
- Report ID
- MRSE - 104720
- Base year
- 2021
- 2029 · FORECAST
- $38.40B
- 2029
- $38.40B
- CAGR 2022–2029
- 7.6%
2021 baseline · 2022–2029 forecast at 7.6% CAGR · hover a bar for the value
Key highlights
Based on Type, the Primary Radar Segment is Projected to Register the Highest CAGR During the Forecast Period
Based on Dimension Type, the 4D Segment is Projected to Register the Highest CAGR During the Forecast Period
Based on Frequency Band Type, the S-band Segment is Projected to Register the Highest CAGR During the Forecast Period
Based on Installation Type, the Ground-based Radar Segment is Projected to Register the Highest CAGR During the Forecast Period
Based on End-user, the Automotive & Mobility Segment is Projected to Register the Highest CAGR During the Forecast Period
Asia-Pacific is Slated to Register the Highest CAGR During the Forecast Period
Report summary
| Particulars | Details |
|---|---|
| Base Year | 2021 |
| Estimated Year | 2022 |
| Forecast Period | 2022–2029 |
| Market Size (2029) | USD 38.40 billion |
| CAGR (2022–2029) | 7.6% |
| Format | PDF, Excel & Cloud Portal · 300 pages |
| Segments Covered | By Type: Primary Radar Continuous Wave Radar Unmodulated Radar, Modulated Radar, Moving Target Indicator (MTI) Radar, Doppler Radar · By Dimension Type: 2D Radar, 3D Radar, 4D Radar, Other Dimension Types · By Frequency Band Type: L-band, S-band, C-band, X-band, Ku-band, Ka-band, Other Frequency Bands · By Installation Type: Ground-based Radar, Marine Radar, Airborne Radar, Spaceborne Radar, Other Installation Types · By End-user: Automotive & Mobility, Aerospace & Defense, Industrial, Consumer, Healthcare, Other End-users |
| Countries Covered | North America (Canada), Europe (Germany, U.K., France, Italy, Spain, Rest of Europe), Asia-Pacific (China, Japan, South Korea, India, Singapore, Rest of Asia-Pacific) |
| Key Companies | DRS RADA Technologies, Thales Group, Honeywell International Inc. (U.S.), Lockheed Martin Corporation (U.S.), Rosoboronexport, Raytheon Anschütz, Saab AB, Northrop Grumman Corporation (U.S.), Israel Aerospace Industries Ltd., General Dynamics Mission Systems, Inc. (U.S.), BAE Systems plc (U.K.), ASELSAN A.Ş, L3Harris Technologies, Inc. (U.S.), Airbus SE, Elbit Systems Ltd. |
Report overview
Segments covered: type, dimension type, frequency band type, installation type, end-user. Regions: North America, Europe, Asia-Pacific.
The growth of this market is attributed to the rising demand for radar systems in automotive and defense industries, the surge in demand for advanced weather monitoring radar systems, and the development of phased array solid-sate radar. Furthermore, the increasing investments by governments to upgrade aircraft radar systems and the rising adoption of radar-based unmanned aerial vehicles are expected to create significant opportunities for the players operating in this market.
However, the stringent cross-border trading policies and susceptibility to new jamming techniques are likely to pose challenges to the growth of this market. Additionally, the high cost of radar systems is restraining market growth.
The COVID-19 pandemic originated in Wuhan, China, in late December 2019. By March 2020, it had spread worldwide, causing huge casualties and severe economic losses. The pandemic severely affected several sectors, including the automotive sector, with major manufacturers shutting down operations entirely or operating at reduced capacity, following guidelines issued by their respective governments. The length of the lockdown and uncertainty over supply chain disruptions have made it difficult for stakeholders to predict the industry's recovery. The crisis triggered structural changes and had a significant impact on the market.
The COVID-19 pandemic had a mixed impact on the end-user. For instance, the automotive and mobility industry reported a significant revenue decline due to stringent global government regulations such as factory closure, the shutdown of manufacturing processes and other regulations. Moreover, low consumer demand for ADAS and disrupted flight operations negatively impacted this industry. Aerospace & defense witnessed significant revenue growth due to the need for radar technology in fighter aircraft to find enemy aircraft and control air-to-air missiles, rockets, and guns. Further, bombers to find surface targets, fixed or moving, and to navigate and avoid obstacles have positively contributed to the radar market.
The global radar market is segmented by type, dimension, frequency band type, installation type, end-user, and geography. The study also evaluates industry competitors and analyses the regional and country-level markets.
The need for weather monitoring is highly gaining traction for detecting climate change and providing data to input into models which enable the government to predict future changes in the environment, such as cyclones, earthquakes, hurricanes, floods, and many other natural disasters. Moreover, the aerospace and defense industry requires weather monitoring radar to determine environmental conditions before and during flight operations. Therefore, aircraft are equipped with integrated weather radar systems, usually found within the nose cone of the aircraft, known as the radome. Although most aircraft are made of metal, the radome is constructed of a special material that allows radar waves to pass through it unobstructed.
The environmental changes have led the government of various countries to undertake initiatives that are strengthening market growth. For instance, in January 2022, the Indian Meteorological Department (IMD) launched operations of four new doppler weather radars in multiple locations in India, such as Mumbai, Delhi, Chennai and Leh, to improve weather forecast systems. Moreover, in September 2022, the Indian Army and the Defense Geoinformatics and Research Establishment (DGRE) (India) installed a weather monitoring radar that can see through snow and fog and detect avalanches within three seconds of being triggered. Moreover, in an area where the frequency of triggering avalanches is high, the installation of the first avalanche radar will go a long way in safeguarding the life of troops of the Indian Army deployed in harsh terrain and sub-zero temperatures while at the same time limiting damage to vehicles and equipment operating at such snowbound, high altitudes areas. Thereby, the need for advanced weather monitoring systems is propelling the market growth in coming years.
Report infographic
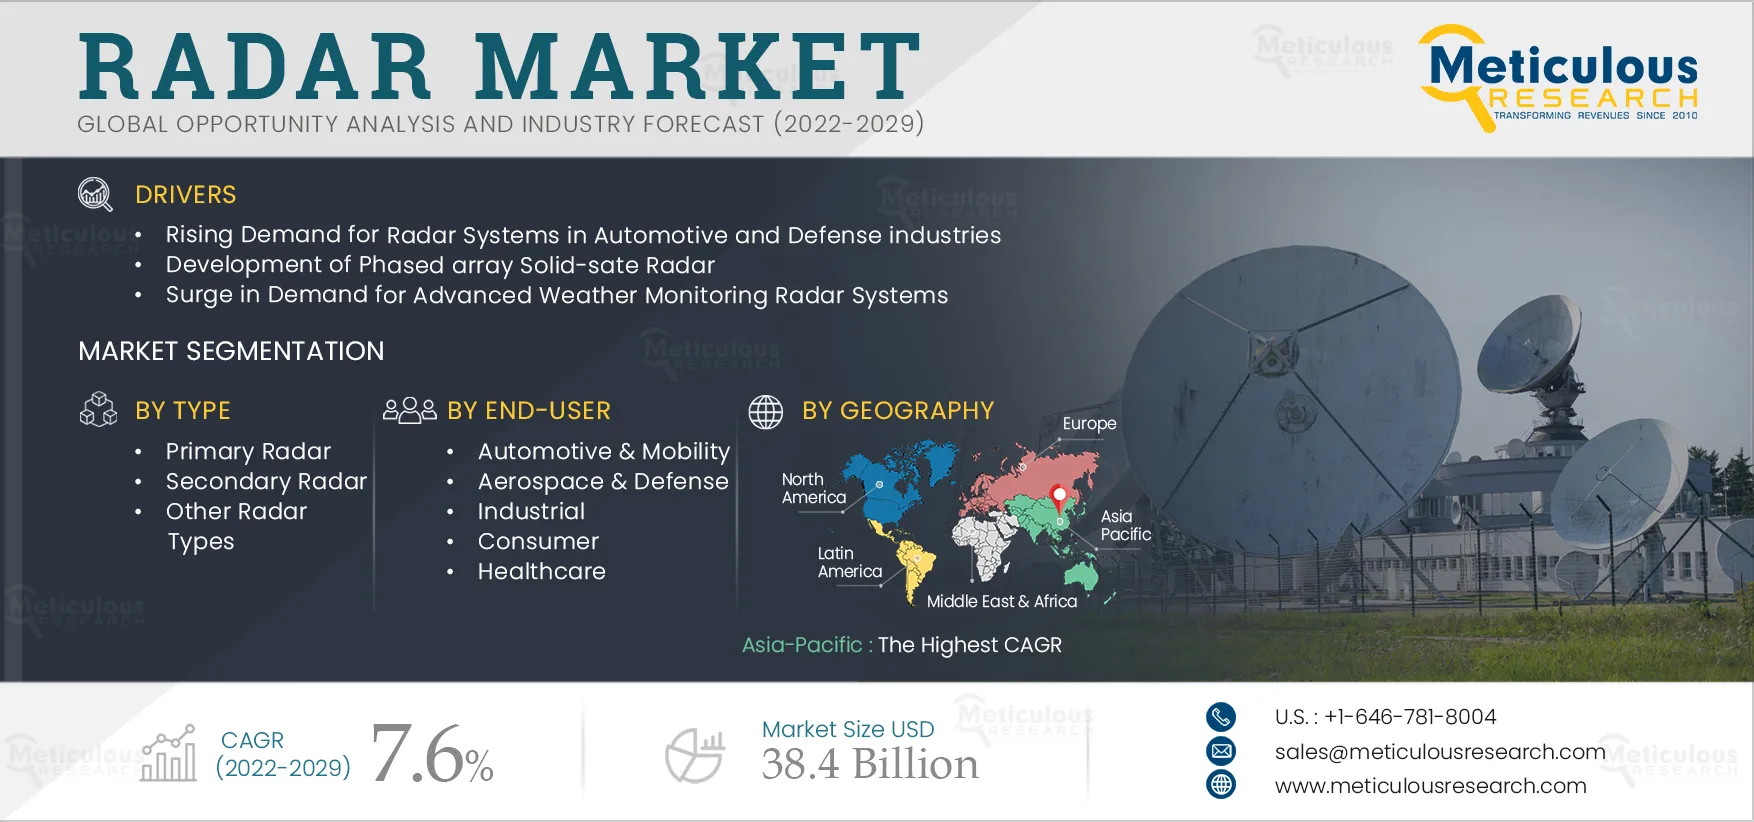
Table of contents
14 chapters · 101 sections · 300 pages · click to expandSegmental analysis
| Segment | Largest share (2022) | Fastest growth (2022–2029) |
|---|---|---|
| By Type | — | Primary radar |
| By Dimension Type | — | — |
| By Frequency Band Type | — | S-band |
| By Installation Type | — | Ground-based radar |
| By End-user | — | Automotive & mobility |
By Type
- The Primary Radar Segment is Projected to Register the Highest CAGR During the Forecast Period
- The primary radar segment is expected to grow at the highest CAGR during the forecast period.
- The segment's high growth is attributed to the use of primary radar for accurately detecting non-cooperative targets over the full radar coverage.
- The advantages of primary radar are that no onboard equipment in the aircraft is necessary for detecting the target and that it is used to monitor the movement of vehicles on the ground.
By Dimension Type
- The 4D Segment is Projected to Register the Highest CAGR During the Forecast Period
- The 4D segment is expected to grow at the highest CAGR during the forecast period.
- The growth of the 4D segment is majorly attributed to the growing demand for ADAS systems for automated driving. 4D radar is high-resolution, long-range technology that offers significant advantages over 3D radar in identifying an object's height. 4D radar is important in developing advanced driver-assistance systems (ADAS) for Level 2 and 3 functions and is a key enabler for Level 4 and 5 automated vehicles.
By Frequency Band Type
- The S-band Segment is Projected to Register the Highest CAGR During the Forecast Period
- The S-band segment is expected to grow at the highest CAGR during the forecast period.
- The demand for S-band radars is rapidly growing due to their growing deployments in large antennas and their popularity in maritime operations.
- These radars are often used for specific applications such as long-range bird detection and for better visibility in precipitation & harsh weather conditions during flight.
- The demand for an S-band radar is also increasing due to the growing demand for communication satellites.
By Installation Type
- The ground-based radar segment is expected to grow at the highest CAGR during the forecast period.
- The demand for ground-based systems is increasing faster due to the need for strengthening cavalry units and locating targets.
- Moreover, the latest innovations in next-gen military systems include radiofrequency tiles & gallium nitride transmitters and modular 3D radar, fueling the market growth.
By End-user
- The automotive & mobility segment is expected to grow at the highest CAGR during the forecast period.
- The growth of this segment is attributed to the growing usage of radar technology in the ADAS systems for collision avoidance, pedestrian and cyclist detection, and HMI in the automotive industry.
- The frequency of flights and cargo planes and the growing air traffic demand efficient traffic control to prevent fatal encounters further fueling this segment's demand.
Geographic analysis
Asia-Pacific
Fastest growthAsia-Pacific is estimated to capture a significant market share during the forecast period. This market growth is owing to increasing demand for modern naval radars with advanced technologies from emerging nations such as India and China. Furthermore, the need for anti-ballistic missile systems in the defense service across Asia-Pacific helped to grow the market. Asia-Pacific is Slated to Register the Highest CAGR During the Forecast Period
Competitive landscape
- DRS RADA Technologies · Israel
- Thales Group · France
- Honeywell International Inc. (U.S.)
- Lockheed Martin Corporation (U.S.)
- Rosoboronexport · Russia
- Raytheon Anschütz · Germany
- Saab AB · Sweden
- Northrop Grumman Corporation (U.S.)
- Israel Aerospace Industries Ltd. · Israel
- General Dynamics Mission Systems, Inc. (U.S.)
- BAE Systems plc (U.K.)
- ASELSAN A.Ş · Turkey
- L3Harris Technologies, Inc. (U.S.)
- Airbus SE · Netherlands
- Elbit Systems Ltd. · Israel
Frequently asked questions
The global radar market is segmented based on type, dimension type, frequency band type, installation type, end-user, and geography. The study also evaluates industry competitors and analyses the regional and country-level markets.
Cite this report
Meticulous Research. (2022). Radar Market - Global Opportunity Analysis and Industry Forecast (2022-2029) (Report No. MRSE - 104720). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/radar-market-5404