Direct to Consumer (DTC) Pet Food Market (2024-2031)
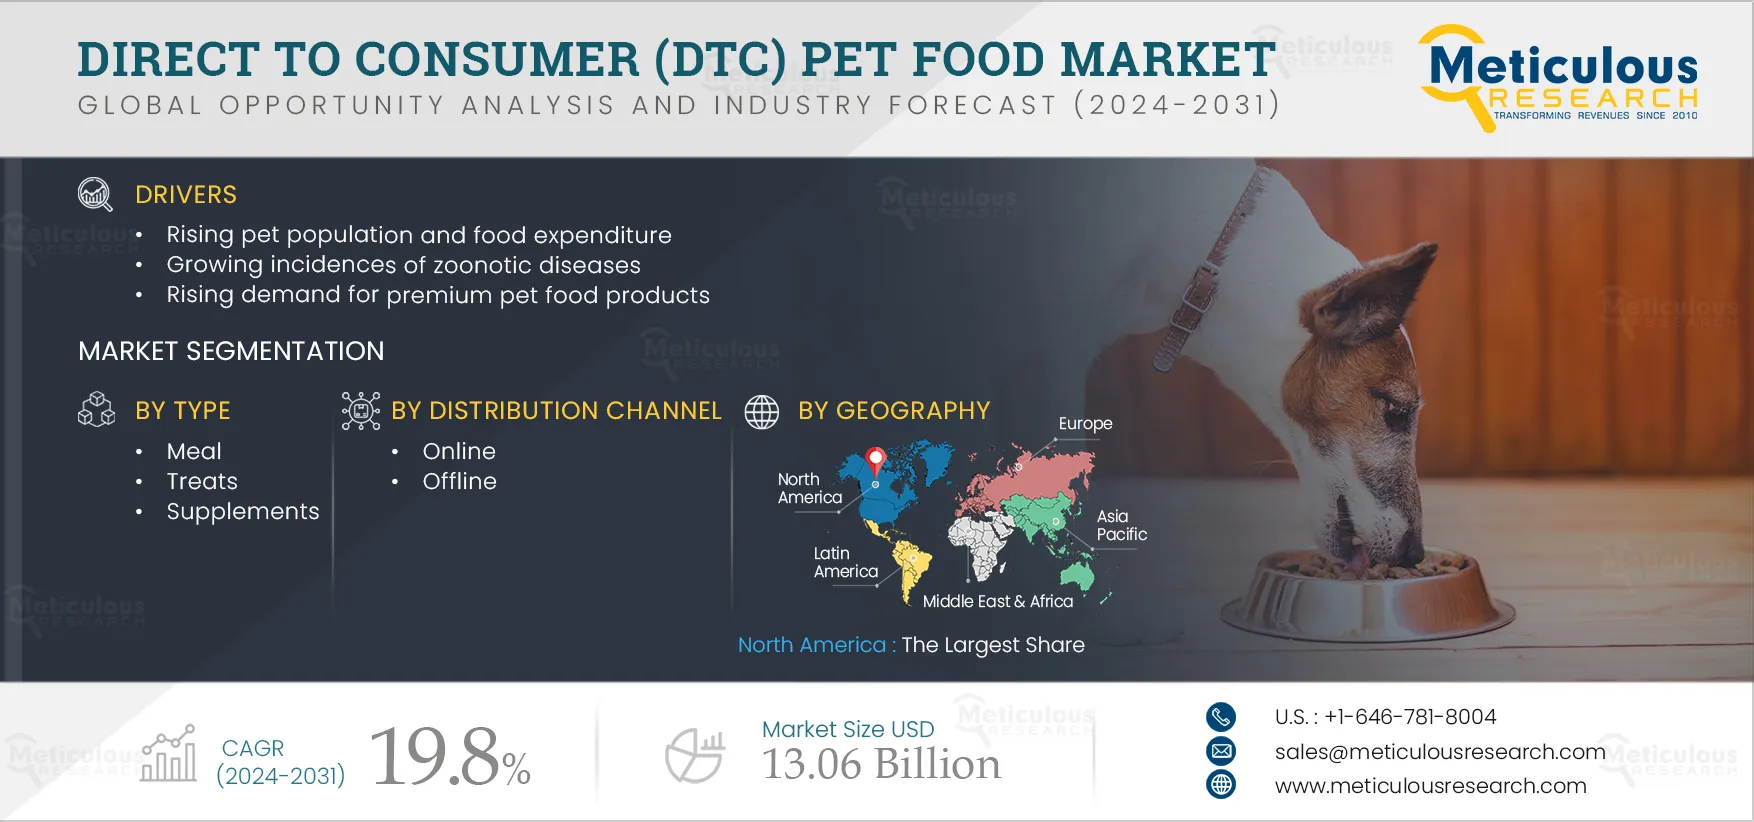
The Direct to Consumer (DTC) Pet Food Market was valued at $2.9 billion in 2023. This market is expected to reach $13.06 billion by 2031, from an estimated $3.68 billion in 2024, at a CAGR of 19.8% during the forecast period 2024-2031. Direct-to-Consumer Pet Food Market Size & Forecast The growth of
- Published
- May 2024
- Pages
- 230
- Format
- PDF + Excel
- Report ID
- MRFB - 104450
- Base year
- 2023
- 2023 · BASELINE
- $2.90B
- 2031
- $13.06B
- CAGR 2024–2031
- 19.8%
2023 baseline · 2024–2031 forecast at 19.8% CAGR · hover a bar for the value
Key highlights
By Type: In 2024, the Meal Segment to Dominate the Direct-to-Consumer Pet Food Market
By Pet Type: In 2024, the Dogs Segment to Dominate the Direct-to-Consumer Pet Food Market
By Health Conditions: The Digestive Health Segment to Witness Highest Demand During the Forecast Period
By Distribution Channel: In 2024, the Online Segment to Dominate the Direct-to-Consumer Pet Food Market
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 230 |
| Format | |
| Forecast Period | 2024–2031 |
| Base Year | 2023 |
| CAGR (Value) | 19.8% |
| Market Size (Value) | $13.06 billion |
| Segments Covered | By Type · Meal · Pet Meal Market, by Category · Standard Meal · Customized Meal · Pet Meal Market, by Form · Dry Meal · Wet Meal · Treats · Standard Treats · Dental Chews · Standard Chews · Supplements · By Pet Type · Dogs · Cats · Other Pets · By Health Condition · Nutritional · Digestive Health · Heart Health · Allergies · Dental Health · Skin Problems · Stress · Joint Health · Other Health Conditions · By Distribution Channel · Online · Offline |
| Countries Covered | North America (U.S., Canada), Europe (U.K., Germany, France, Italy, Spain, Russia, and Rest of Europe), Asia-Pacific (Japan, Australia, China, India, and Rest of Asia-Pacific), Latin America (Brazil, Argentina, and Rest of Latin America), and the Middle East & Africa |
| Key Companies | Nestlé S.A. (Switzerland), General Mills, Inc. (U.S.), Mars, Incorporated (U.S.), Hill's Pet Nutrition, Inc. (Part of Colgate-Palmolive Company) (U.S.), The J.M. Smucker Company (U.S.), Diamond Pet Foods, Inc. (Part of Schell & Kampeter, Inc.) (U.S.), Heristo Aktiengesellschaft (Germany), Simmon Pet Food, Inc. (U.S.), WellPet, LLC (U.S.), The Farmers Dog, Inc. (U.S.), Jinx, Inc. (U.S.), JustFoodForDogs, LLC (U.S.), Ollie Pets Inc. (U.S.), Farmina Pet Foods Holding B.V. (Netherlands), and NomNomNow, Inc. (Philippines). |
Report overview
Segments covered: type. Regions: North America, Europe, Asia-Pacific, Latin America.
The growth of this market can be attributed to several factors, including the rising pet population and food expenditure, growing incidences of zoonotic diseases, rising demand for premium pet food products, rising number of pet DTC brands, and rise in e-commerce. However, the quality issues related to pet food products and product recalls restrain the growth of this market. Moreover, the use of cannabis in pet food is expected to generate significant growth opportunities for the stakeholders in the direct-to-consumer pet food market. The latest trends in the direct-to-consumer pet food market are the rising demand for customized pet food and the humanization of pets.
Report infographic
Market dynamics
5 factors across 3 forcesRising Demand for Premium Pet Food Products Driving Market Growth
Pet owners worldwide are becoming more conscious about choosing appropriate food for their pets, increasing the demand for premium and natural brands. These brands are in demand due to the growing awareness about pets' health and wellness, humanization trends, and rising disposable income. For instance, according to the American Pet Products Association (APPA) pet ownership report 2023, 45% of dog owners bought premium dog foods in 2022.
To capitalize on this industry trend, many pet food manufacturers have started providing a variety of premium products, including gluten-free, GMO-free, organic, and multi-vitamins & minerals-rich products offering enhanced health benefits, such as dog food with Omega 3 and 6 fatty acids for healthy skin, probiotics in dry formulas to help maintain digestive health, glucosamine for healthy joints and strong bones, which further supports the trend of premiumization.
Thus, the rising demand for premium pet food products is expected to support the growth of the direct-to-consumer pet food market.
Rise in E-commerce to Boost Market Growth
In recent years, e-commerce has become popular in the pet care industry. The growing preference for online shopping of pet products is expected to provide immense opportunities for players operating in the pet care business. E-commerce offers hassle-free delivery, user-friendly websites/apps, and a wide range of products. Hectic lifestyles have led individuals to choose online retail channels for expeditious doorstep delivery.
Furthermore, the easy accessibility of pet products through online retail channels has influenced numerous leading retailers to launch their online websites. Numerous startup pet stores have also started operating their e-commerce stores in recent years. Thus, modern shopping methods and advanced e-commerce technologies have magnified pet product sales. Moreover, e-commerce sales trends in the pet food market provide huge scope for personalized pet food. Various startups focus on offering customized pet meals based on lifestyle, breed, age, current illnesses, and environment. Personalized pet food is gaining huge popularity among pet owners who want the best food for their pets.
Thus, the rise in e-commerce is expected to support the growth of the direct-to-consumer pet food market.
Table of contents
12 chapters · 127 sections · 230 pages · click to expandSegmental analysis
| Segment | Largest share (2024) | Fastest growth (2024–2031) |
|---|---|---|
| By Type | Meal | — |
| By Pet Type | Dogs | — |
| By Health Condition | Nutritional conditions | Digestive health |
| By Distribution Channel | Online | — |
By Type
- The Meal Segment to Dominate the Direct-to-Consumer Pet Food Market
- The meal segment is expected to account for the largest share of 75.9% of the direct-to-consumer pet food market.
- The large market share of this segment can be attributed to the rising awareness about pet health, increased spending on premium meals, and the growing demand for customized meals.
- The meal segment is divided into standardized meals and customized meals.
- The standardized meal segment is expected to account for the larger share of 71.5% of the direct-to-consumer pet meal market.
- The high quality of ingredients, longer shelf life, and the humanization of pets are the key factors attributed to the large share of this segment.
By Pet Type
- The Dogs Segment to Dominate the Direct-to-Consumer Pet Food Market
- The dogs segment is expected to account for the largest share of 75.1% of the direct-to-consumer pet food market.
- The large market share of this segment can be attributed to the rising number of dog adoptions, the growing demand for high-quality dog food products, and the humanization of dogs.
By Health Condition
- The Digestive Health Segment to Witness Highest Demand During the Forecast Period
- The nutritional conditions segment is expected to account for the largest share of 25.5% of the direct-to-consumer pet food market.
- The large market share of this segment can be attributed to the increasing expansion of premium pet food brands and the rising awareness of pet owners towards the preferences and health conditions of their pets.
- However, the digestive health segment is projected to witness the highest growth rate of 23.9% during the forecast period of 2024–2031.
- This growth is driven by the increasing number of customized nutritional formulations to prevent digestive problems and the introduction of prebiotics and probiotics in pet food diets.
By Distribution Channel
- The Online Segment to Dominate the Direct-to-Consumer Pet Food Market
- The online segment is expected to account for the larger share of 91.6% of the direct-to-consumer pet food market.
- The large market share of this segment can be attributed to the growing preference for personalization, consumer convenience, availability of greater discounts compared to offline stores, and greater product selection experience.
Geographic analysis
North America
Largest shareIn 2024, North America is expected to account for the largest share of 47.9% of the direct-to-consumer pet food market, followed by Europe, Asia-Pacific, Latin America, and the Middle East & Africa. North America’s significant market share can be attributed to several key factors, including the rising number of millennials as pet owners, the availability of a wide range of customized pet food in the region, the growing focus on the health and diets of pets, and the presence of major players in North America. Moreover, it is also slated to register the highest growth rate of 22.5% during the forecast period. The growth of this regional market is driven by the growing adoption of digital channels. By Geography: In 2024, North America to Dominate the Direct-to-Consumer Pet Food Market
Competitive landscape
- November 2021
Hill’s Pet Nutrition partnered with Bond Pet Foods, Inc. (U.S.) to develop meat protein produced through fermentation.
- August 2021
WellPet, LLC launched Wellness Complete Health wet diets for kittens and WHIMZEES Value Packs assorted dental treats for dogs and is planning to launch a CORE Digestive Health diet in 2022.
- June 2021
Nestlé Purina PetCare Company invested USD 182 million to expand manufacturing operations in King William County (Virginia) and enhance business operations for its Tidy Cats litter products in the U.S. and Canada.
- May 2021
Nestlé Purina PetCare expanded in Dunkirk, New York, with an investment of USD 19 million to increase production capacity for Fancy Feast Savory Cravings, a new cat treat.
- Nestlé S.A. · Switzerland
- General Mills, Inc. (U.S.)
- Mars, Incorporated (U.S.)
- J.M. Smucker Company (U.S.)
- Heristo Aktiengesellschaft · Germany
- Simmon Pet Food, Inc. (U.S.)
- WellPet, LLC (U.S.)
- Farmers Dog, Inc. (U.S.)
- Jinx, Inc. (U.S.)
- JustFoodForDogs, LLC (U.S.)
- Ollie Pets Inc. (U.S.)
- Farmina Pet Foods Holding B.V. · Netherlands
- NomNomNow, Inc. · Philippines
Frequently asked questions
This report covers the market sizes and forecasts of the direct-to-consumer pet food market based on type, pet type, health condition, distribution channel, and geography. It also provides the value analysis of various segments of the direct-to-consumer pet food market at the regional and country levels.
Cite this report
Meticulous Research. (2024). Direct to Consumer (DTC) Pet Food Market- Global Opportunity Analysis and Industry Forecast (2024-2031) (Report No. MRFB - 104450). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/direct-to-consumer-pet-food-market-5146