Digital Key & Secure Vehicle Access Systems Market (2026-2036)
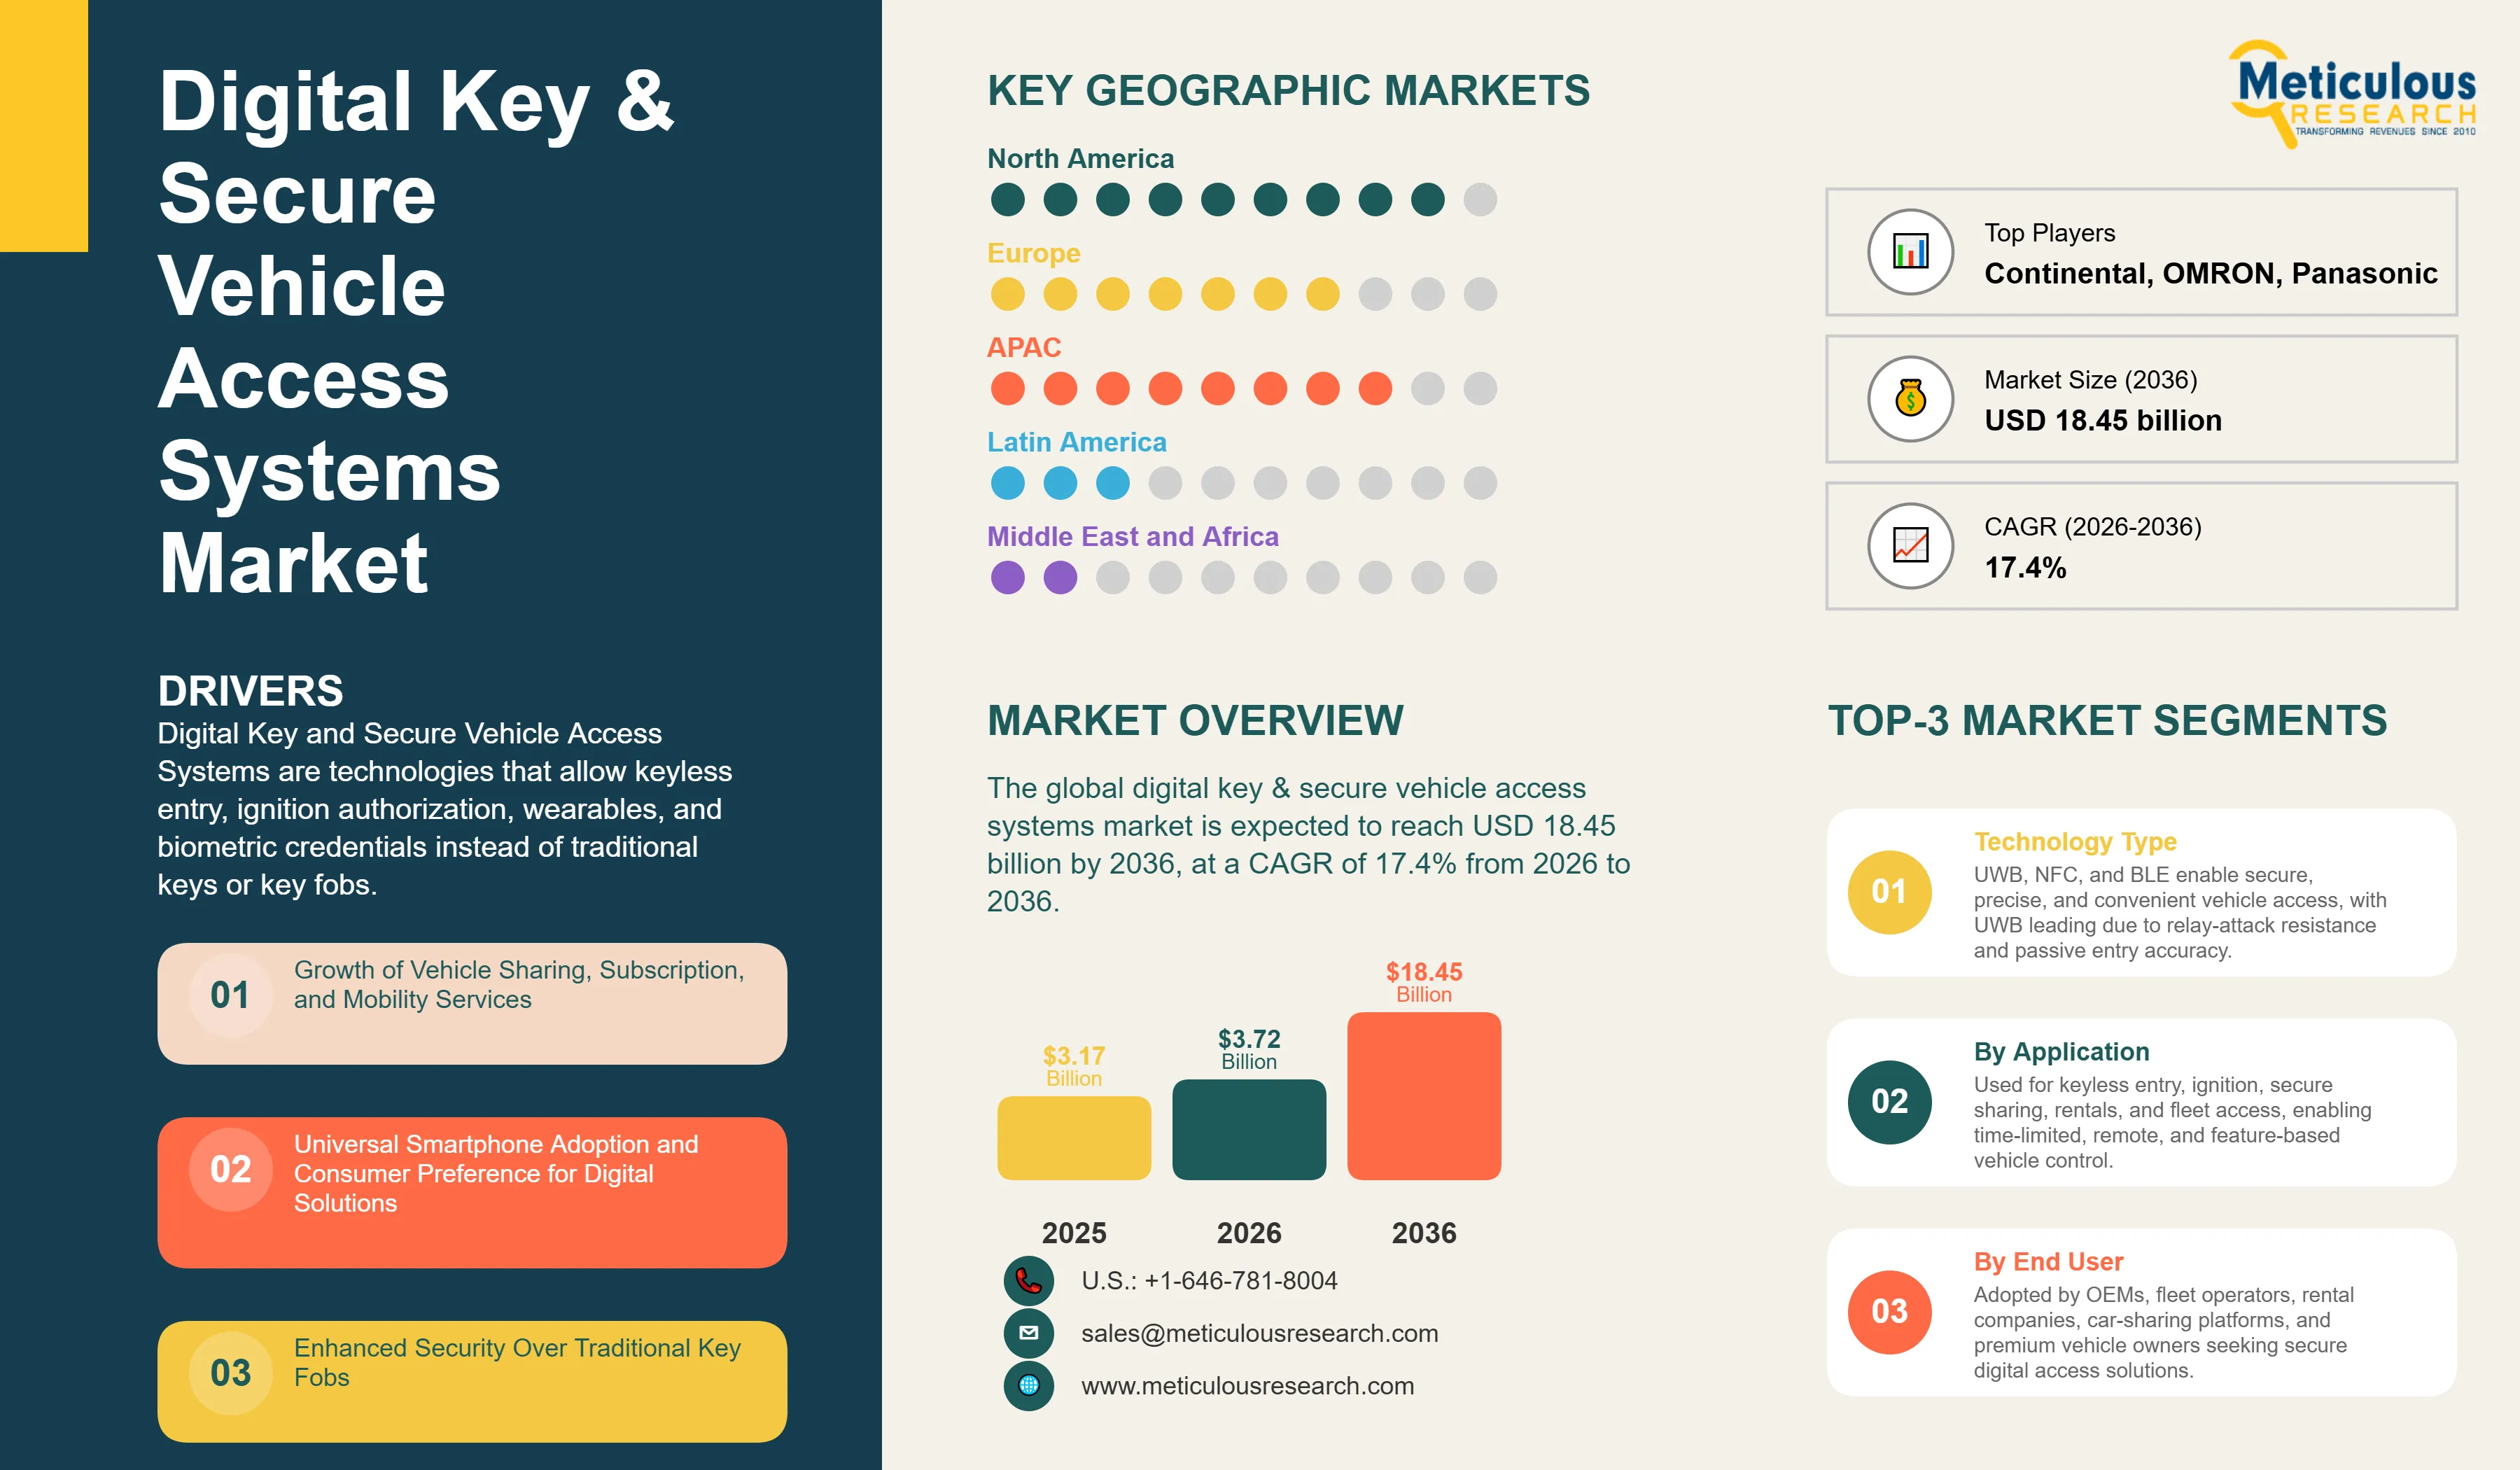
The global digital key & secure vehicle access systems market is expected to reach USD 18.45 billion by 2036 from USD 3.72 billion in 2026, at a CAGR of 17.4% from 2026 to 2036.
- Published
- Jan 2026
- Pages
- 255
- Format
- PDF + Excel
- Report ID
- MRAUTO - 1041657
- Base year
- 2025
- 2026 · ESTIMATED
- $3.72B
- 2036
- $18.45B
- CAGR 2026–2036
- 17.4%
2025 baseline · 2026–2036 forecast at 17.4% CAGR · hover a bar for the value
Key highlights
In 2026, North America is estimated to account for the largest share of the global digital key & secure vehicle access systems market, driven by high smartphone penetration, strong adoption of connected vehicle services, early deployment by major automakers, and growing vehicle sharing platforms.
Asia-Pacific is projected to register the highest CAGR during the forecast period, fueled by rapidly growing automotive production, aggressive adoption by Chinese EV manufacturers, increasing smartphone ubiquity, and strong regional electronics and semiconductor ecosystem.
Based on technology type, the UWB (Ultra-Wideband) segment is estimated to hold the largest share of the market in 2026, driven by its superior security, precise positioning capability, relay attack resistance, and adoption by leading smartphone manufacturers.
Based on security protocol, the end-to-end encrypted digital credentials segment is estimated to dominate the market in 2026, owing to robust security architecture and compliance with CCC (Car Connectivity Consortium) Digital Key standards.
Based on smartphone integration, the native smartphone digital key segment is expected to witness significant growth during the forecast period, driven by Apple Car Key and Google Digital Car Key platform adoption eliminating need for proprietary apps.
Based on OEM adoption strategy, the embedded OEM systems segment is expected to account for the largest share of the market in 2026, fueled by automaker prioritization of integrated security and seamless user experiences.
The aftermarket and retrofit segment is expected to grow at a significant CAGR during the forecast period, driven by fleet operators and commercial applications requiring digital access management for existing vehicles.
The U.S. digital key & secure vehicle access systems market is projected to grow at a CAGR of around 16% during the forecast period 2026 to 2036, driven by luxury vehicle adoption, car sharing service growth, and consumer preference for smartphone-based solutions.
China is expected to lead the Asia-Pacific digital key & secure vehicle access systems market, driven by massive EV production with integrated digital key systems, domestic smartphone manufacturers, advanced mobile payment ecosystem integration, and government support for intelligent connected vehicles.
In 2026, Germany is projected to account for the largest share of the European digital key & secure vehicle access systems market, driven by premium automakers BMW, Mercedes-Benz, and Audi pioneering digital key deployment and integration with luxury vehicle features.
Report summary
| Particulars | Details |
|---|---|
| Market Size Value in 2026 | USD 3.72 Billion |
| Revenue Forecast in 2036 | USD 18.45 Billion |
| Growth Rate | CAGR of 17.4% from 2026 to 2036 |
| Format | PDF, Excel & Cloud Portal · 255 pages |
| Base Year for Estimation | 2025 |
| Historical Data | 2021–2025 |
| Forecast Period | 2026–2036 |
| Quantitative Units | Revenue in USD Billion and CAGR from 2026 to 2036 |
| Report Coverage | Revenue forecast, company ranking, competitive landscape, growth factors, and trends |
| Segments Covered | Technology Type, Security Protocol, Smartphone Integration, Access Management, OEM Adoption Strategy, Use Case, Vehicle Segment, Region |
| Regional Scope | North America, Europe, Asia-Pacific, Latin America, Middle East & Africa |
| Countries Covered | U.S., Canada, Germany, U.K., France, Italy, Spain, Sweden, China, Japan, South Korea, India, Australia, Brazil, Mexico, Saudi Arabia, UAE, South Africa |
| Key Companies Profiled | Continental AG, Denso Corporation, Valeo SA, HELLA GmbH & Co. KGaA, ZF Friedrichshafen AG, Alps Alpine Co. Ltd., Tokai Rika Co. Ltd., Marquardt GmbH, OMRON Corporation, NXP Semiconductors N.V., STMicroelectronics N.V., Infineon Technologies AG, Qualcomm Technologies Inc., Apple Inc., Google LLC, Samsung Electronics Co. Ltd., Hyundai Mobis Co. Ltd., LG Innotek Co. Ltd., Panasonic Automotive Systems Co. Ltd., Lear Corporation |
Report overview
Segments covered: technology, security protocol, integration with smartphone, oem adoption.
Digital Key and Secure Vehicle Access Systems are technologies that allow keyless entry, ignition authorization, and secure sharing using smartphones, wearables, and biometric credentials instead of traditional keys or key fobs. They aim to remove the need for physical key management, allow secure temporary access sharing, improve user convenience, and provide control over personal and shared vehicles. These systems use various technologies such as Near Field Communication (NFC), Ultra-Wideband (UWB), Bluetooth Low Energy (BLE), biometric authentication, and encrypted digital credentials to authenticate users and manage their access permissions.
Digital key systems can unlock and start vehicles using a smartphone, support secure key sharing with family, friends, or service providers, offer time-limited and restricted access for car sharing and rentals, integrate biometric authentication for better security, and allow remote access management via cloud platforms. This system offers a smooth keyless experience, removes worries about lost or stolen keys, helps create new mobility business models, and supports fleet and access management. This approach helps automakers provide modern user experiences that match smartphone-focused lifestyles while also enabling vehicle sharing services, subscription programs, and rental operations that need flexible and secure access management.
Digital Key and Secure Vehicle Access Systems are changing how we control access to vehicles and manage ownership. They move away from traditional metal keys, using digital credentials stored on smartphones and other devices instead. This shift allows for secure and flexible access that fits modern lifestyles. These smart systems use the power, connectivity, and security features of smartphones to provide authentication and authorization that go far beyond traditional key fobs. They also introduce new possibilities like instant key sharing, temporary access permissions, and remote access management. By combining several wireless technologies with strong encryption protocols and cloud-based credential management, digital key systems offer improved convenience and higher security than physical keys, which can be lost, stolen, duplicated, or subjected to relay attacks.
Several key trends are transforming the digital key and secure vehicle access systems market. One trend is the shift from specific OEM apps to standard platform-native digital keys integrated into Apple Wallet and Google Wallet. Another is the rapid growth of Ultra-Wideband technology, which offers relay attack resistance and accurate positioning for passive entry. The use of biometric authentication also adds multiple layers of security. Additionally, there is a move from luxury vehicle exclusivity to wider adoption driven by vehicle sharing and subscription services. The growth of smartphone use, recognition by automakers of digital keys as vital for new mobility services, standardization through the Car Connectivity Consortium, and advancements in wireless and security technologies have sped up the shift from premium niche features to mainstream use in various vehicle segments.
The digital key and secure vehicle access systems market is quickly moving toward standardized, secure, and highly functional systems that work seamlessly with smartphone platforms and support a variety of uses, from personal ownership to shared mobility. Today's digital key solutions do much more than just unlock doors via Bluetooth. They create access ecosystems that support different authentication methods—like smartphones, smartwatches, and biometrics. They allow for detailed permission management such as time limits, feature restrictions, and geofencing. These systems also integrate with vehicle personalization setups, provide detailed access logs and analytics, and work with connected vehicle platforms for remote management. The shift from proprietary OEM-specific digital key apps to standardized platform-native versions in Apple Wallet and Google Wallet is a major advancement, enhancing user experience and speeding up adoption.
Wireless technology and security structures are quickly improving. These advancements let digital key systems provide better security than traditional key fobs while keeping user convenience high. Ultra-Wideband (UWB) technology is becoming the top choice for premium digital key systems. It offers secure distance measurement to stop relay attacks, allows passive entry without needing to unlock phones or open apps, supports precise positioning for features like automatic trunk opening when you approach from behind, and functions well in crowded radio frequency environments. The mix of UWB for secure positioning, NFC for backup access and easy pairing, and Bluetooth Low Energy (BLE) for long-range detection creates multi-technology setups that enhance security and convenience.
The combination of digital keys with vehicle sharing platforms, subscription services, and mobility-as-a-service applications is opening up new opportunities and uses. Modern systems allow for instant digital key delivery to rental customers, removing the need for physical key exchanges. They support peer-to-peer car sharing with secure temporary access and help subscription service providers manage vehicle access for rotating customers. Fleet operators can control driver access with detailed logs, and there’s integration with ride-sharing platforms for smooth vehicle access management. This ecosystem integration changes digital keys from being just convenient personal features to crucial tools for new mobility business models that need flexible, secure, and remotely controlled access.
The merging of digital key technology with autonomous vehicle development is creating new scenarios and requirements. As vehicles move toward being autonomous and shared mobility services, strong occupant authentication and access control are crucial for security, safety, and service quality. Digital keys will confirm authorized passengers in robotaxis, make sure only approved users access autonomous delivery vehicles, manage access control in shared fleets, and support easy integration with mobility-as-a-service platforms. The shift toward passenger authentication instead of driver authentication in autonomous vehicles requires digital key systems to handle multi-passenger verification, flexible access levels, and integration with passenger monitoring systems.
The rise of digital vehicle identity ecosystems is broadening digital key functionality beyond just access control. It now includes complete vehicle interaction and ownership management. These new implementations connect digital keys with vehicle personalization systems, link with insurance platforms for usage-based policies, allow payment authorization for fueling and charging, support remote vehicle control and monitoring, and ease vehicle ownership transfer and resale. This digital identity approach positions digital keys as essential parts of connected vehicle ecosystems instead of standalone access tools.
Report infographic
Market dynamics
4 factors across 2 forcesGrowth of Vehicle Sharing, Subscription, and Mobility Services
The rapid growth of vehicle sharing platforms, subscription services, and mobility-as-a-service models is creating a strong demand for flexible, secure digital access management. Traditional key distribution causes a lot of operational complexity and cost for these services. Keys must be physically exchanged, tracked, secured when not in use, and replaced if lost. This physical key management is a big issue for car sharing services (like Zipcar, Turo, Getaround), rental companies, corporate fleets, and subscription programs (such as Care by Volvo and Porsche Passport). Digital key technology solves this problem by allowing instant remote key delivery and revocation. Services can send digital keys to customer smartphones right after reservation. Access can be automatically revoked when the rental ends, and time-limited access can be aligned with reservation periods. Complete access logs can be maintained for security and accountability. The efficiency gains, better customer experience (no need for key pickup or drop-off locations), and improved security make digital keys essential for these growing mobility sectors. As vehicle sharing and subscription services continue to expand—driven by urbanization and changing preferences for ownership—the demand for digital key technology will also increase.
Universal Smartphone Adoption and Consumer Preference for Digital Solutions
The widespread adoption of smartphones among vehicle-buying demographics and a strong preference for smartphone-based solutions over physical items are driving demand for digital key systems. Modern consumers expect to use smartphones for access control in various situations—unlocking homes, hotel rooms, office buildings, and making payments. This cultural shift leads to the expectation that vehicles should also be accessible through smartphones. The convenience is significant. Smartphones are always on hand, while physical keys can be forgotten, misplaced, or locked inside vehicles. Digital keys remove common frustrations, such as fumbling for keys with full hands, being unable to enter vehicles when keys are lost, and worrying about key theft. Consumer familiarity with smartphone-based authentication from other areas (like Apple Pay, building access, and airline boarding passes) raises expectations for similar applications in cars. Automakers see digital keys as a solution to real consumer problems and align them with modern technology trends. This drives adoption especially in vehicles aimed at tech-savvy buyers and premium customers who appreciate convenient innovations.
Table of contents
16 chapters · 178 sections · 255 pages · click to expandGeographic analysis
North America
Largest shareIn 2026, North America is expected to hold the largest share of the global digital key and secure vehicle access systems market. This leadership results from a very high smartphone penetration, nearing 90%, among car buyers, strong market presence and adoption by luxury automakers offering digital keys, established vehicle sharing and subscription service ecosystems that need flexible access management, and growing demand for smartphone-based solutions. The United States, in particular, drives market leadership with a high concentration of luxury vehicles (BMW, Mercedes-Benz, Genesis, Tesla) that are leading digital key deployment, and the rise of car-sharing platforms (Zipcar, Turo, Getaround) that require digital access management. Corporate fleet adoption also seeks efficiency, while tech-savvy consumers appreciate convenience innovations. Early adoption by premium brands builds consumer awareness and establishes expectations that spread to broader markets.
Asia-Pacific
Fastest growthThe Asia-Pacific region is projected to see the highest growth during the forecast period. This rapid growth is fueled by large automotive production volumes, particularly in China, and aggressive digital key adoption by Chinese EV manufacturers as standard features. There is also extremely high smartphone penetration and a mature mobile payment ecosystem, along with an established regional supply chain for semiconductors and wireless technology, plus robust domestic technology platforms. China, in particular, will drive regional growth through automakers such as NIO, XPeng, Li Auto, BYD, and others that implement advanced digital key systems as standard equipment, even in mid-range vehicles. The combination of automotive digital keys with complete mobile payment and digital identity ecosystems creates unique local implementation patterns. Japan and South Korea enhance regional growth with their advanced automotive industries and presence of key technology suppliers (Denso, Alps Alpine, Hyundai Mobis, Samsung).
Europe
Europe represents a significant market with a high concentration of premium vehicles and wide deployment of digital keys. Strong data privacy regulations (GDPR) influence security architecture decisions, while established luxury brands like BMW, Mercedes-Benz, and Audi lead the way in implementations. There is also growth in subscription and car-sharing services, especially in urban markets. European projects focus on privacy-preserving systems with local data processing and strong encryption.
Competitive landscape
- Continental AG · Germany
- Denso Corporation · Japan
- Valeo SA · France
- HELLA GmbH & Co. KGaA · Germany
- ZF Friedrichshafen AG · Germany
- Alps Alpine Co. Ltd. · Japan
- Tokai Rika Co. Ltd. · Japan
- Marquardt GmbH · Germany
- OMRON Corporation · Japan
- NXP Semiconductors N.V. · Netherlands
- Robert Bosch GmbH · Germany
- STMicroelectronics N.V. · Switzerland
- Infineon Technologies AG · Germany
- Qualcomm Technologies Inc. (U.S.)
- Apple Inc. (U.S.)
- Google LLC (U.S.)
- Samsung Electronics Co. Ltd. · South Korea
- Hyundai Mobis Co. Ltd. · South Korea
- Huf Hülsbeck & Fürst · Germany
- LG Innotek Co. Ltd. · South Korea
- Panasonic Automotive Systems Co. Ltd. · Japan
- Lear Corporation (U.S.)
Frequently asked questions
The digital key & secure vehicle access systems market is expected to grow from USD 3.72 billion in 2026 to USD 18.45 billion by 2036.
Cite this report
Meticulous Research. (2026). Digital Key & Secure Vehicle Access Systems Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MRAUTO - 1041657). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/digital-key-and-secure-vehicle-access-systems-market-6340