Virtual Clinical Trials (VCT) Market (2026-2036)
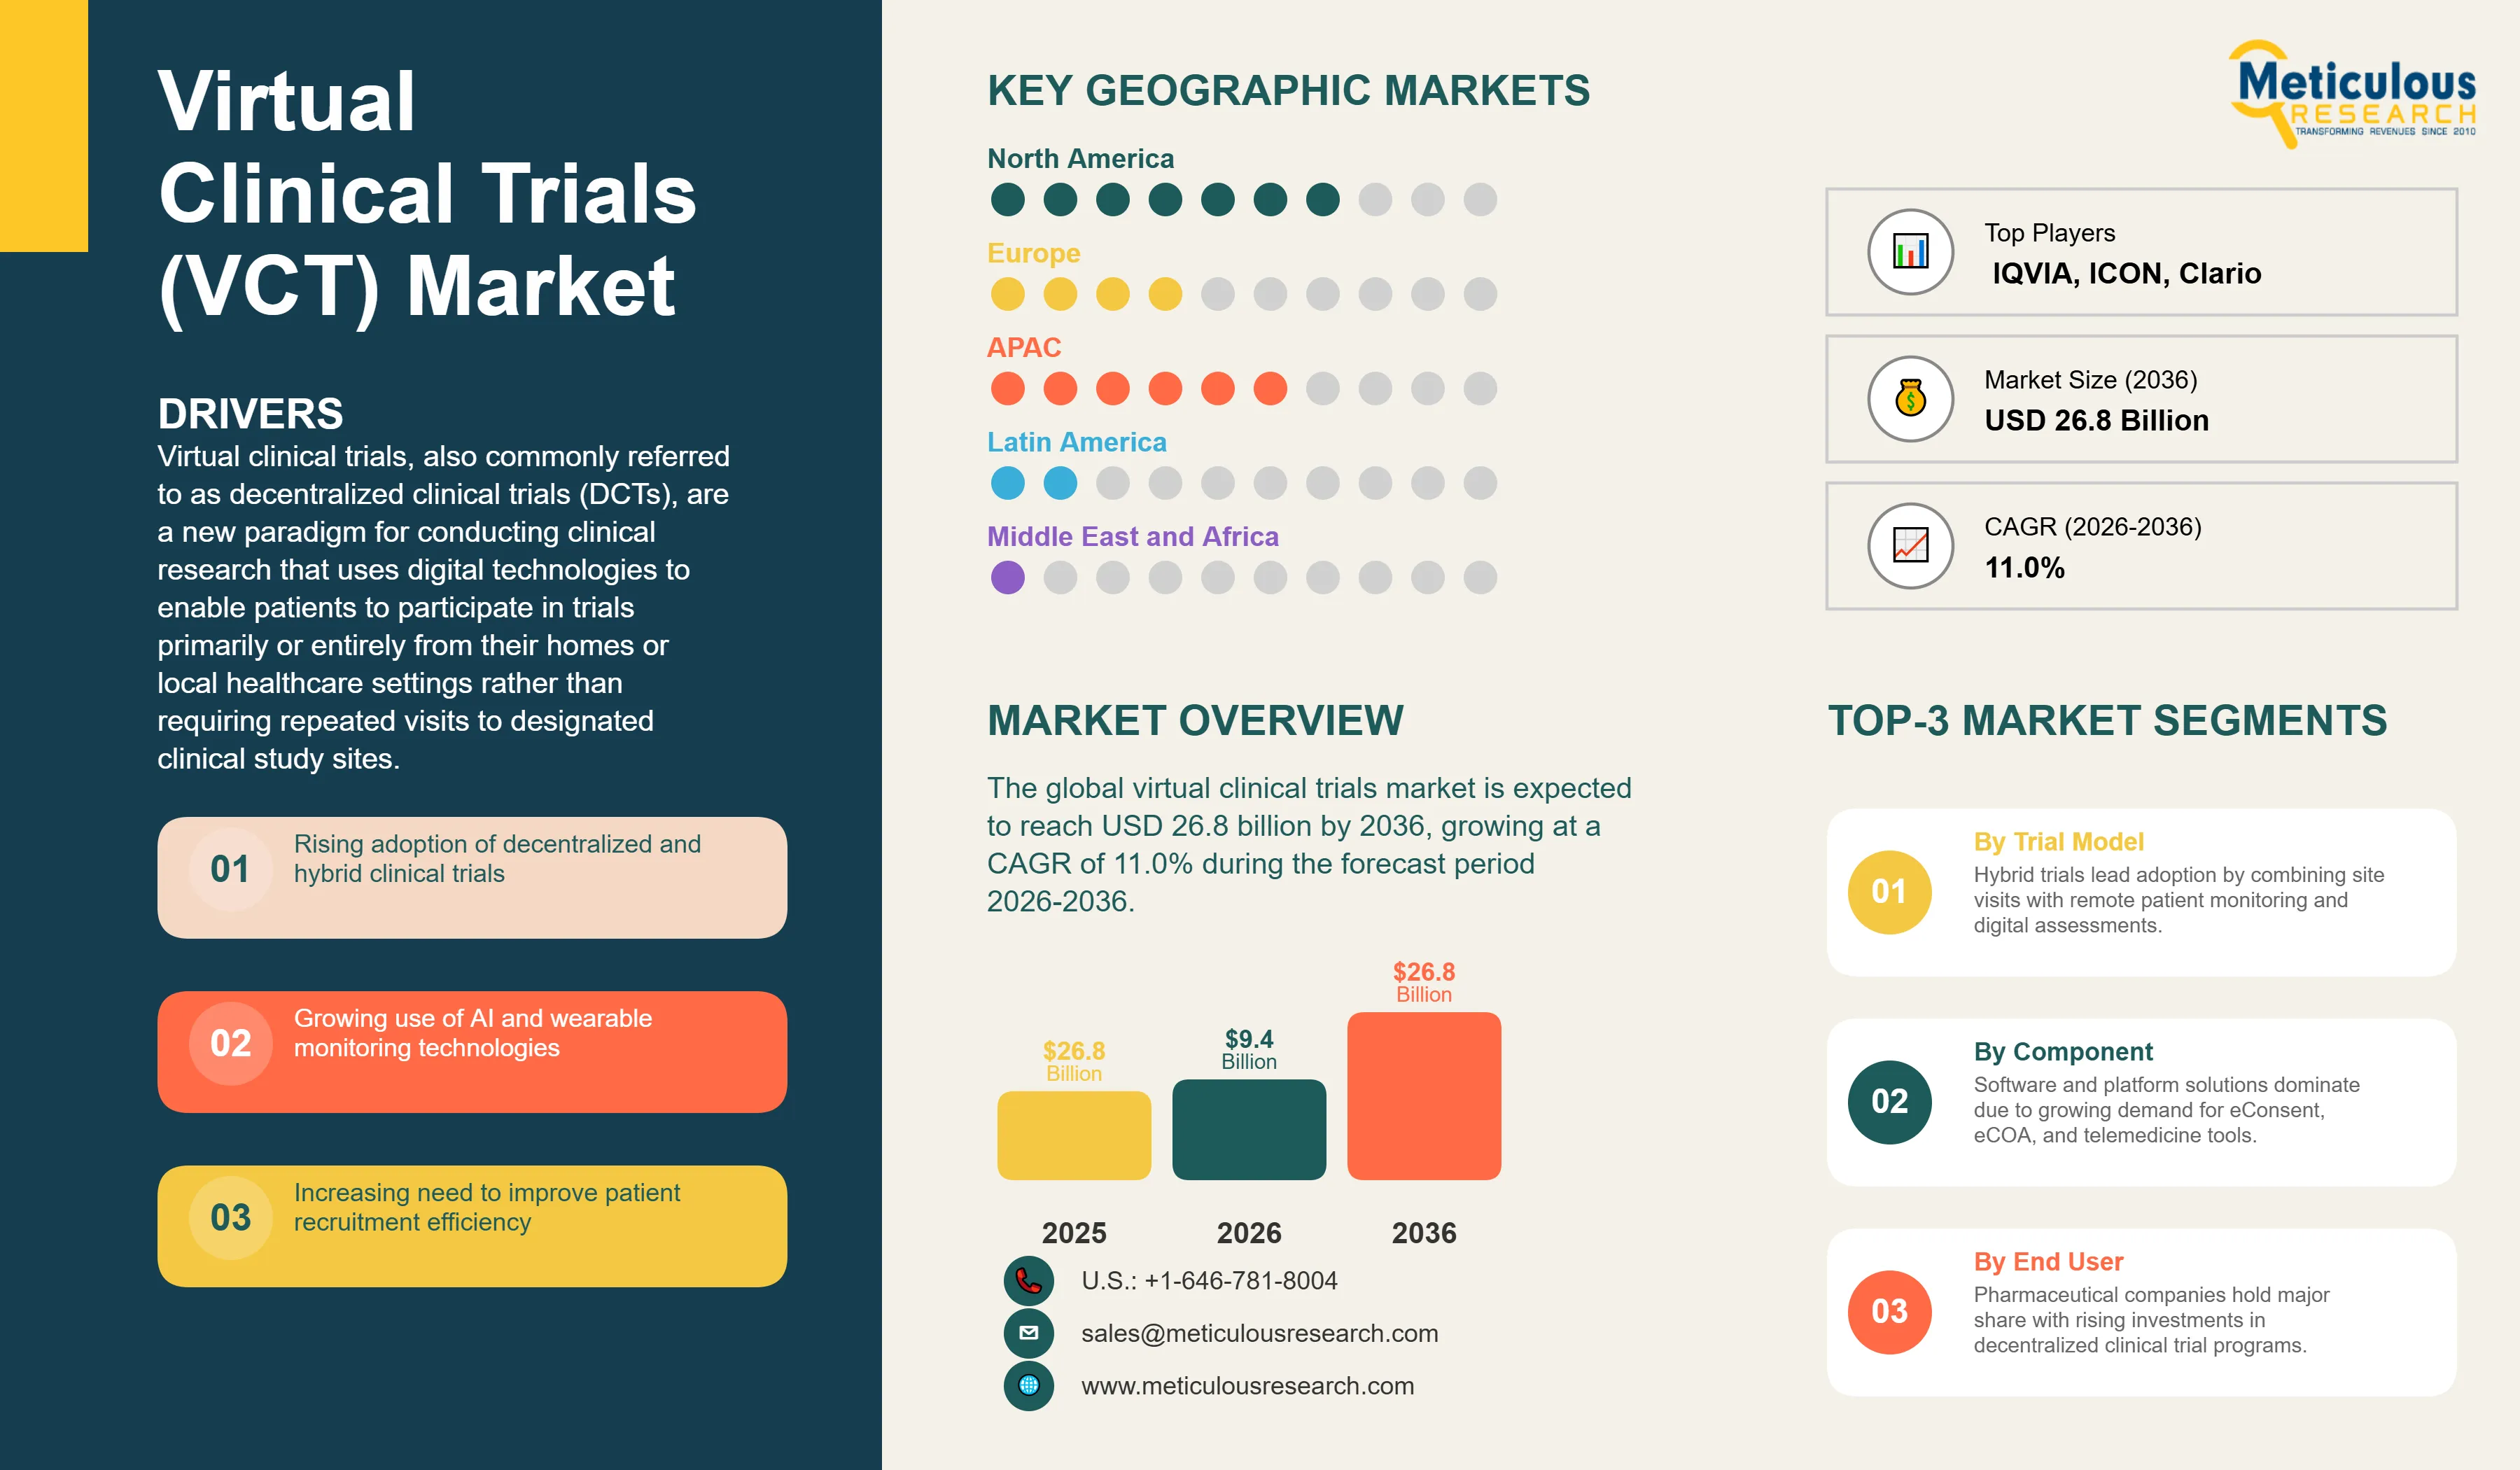
The global virtual clinical trials market was valued at USD 7.8 billion in 2025. This market is expected to reach USD 26.8 billion by 2036 from an estimated USD 9.4 billion in 2026, growing at a CAGR of 11.0% during the forecast period 2026-2036.
- Published
- May 2026
- Pages
- 288
- Format
- PDF + Excel
- Report ID
- MRHC - 1041966
- Base year
- 2025
- 2025 · BASELINE
- $7.80B
- 2036
- $26.80B
- CAGR 2026–2036
- 11.0%
2025 baseline · 2026–2036 forecast at 11.0% CAGR · hover a bar for the value
Key highlights
The global virtual clinical trials market is projected to reach USD 26.8 billion by 2036.
The market is expected to grow at a CAGR of 11.0% during the forecast period 2026-2036.
The global market for virtual clinical trials was valued at USD 7.8 billion in 2025 and is estimated to reach USD 9.4 billion in 2026.
North America is expected to dominate the global virtual clinical trials market with the largest market share in 2026, while Asia-Pacific is projected to register the highest CAGR during the forecast period.
By trial model, the hybrid trials segment is expected to hold the largest share of the market in 2026, while the fully virtual trials segment is projected to register the highest CAGR during the forecast period.
By component, the software and platforms segment is expected to hold the largest share in 2026, while the devices and infrastructure (wearables) segment is projected to register the highest CAGR during the forecast period.
By phase, the Phase III segment is expected to hold the largest share in 2026, while the Phase II segment is projected to register the highest CAGR during the forecast period.
By therapeutic area, the oncology segment is expected to hold the largest share in 2026, while the rare diseases segment is projected to register the highest CAGR during the forecast period.
By indication type, the chronic diseases segment is expected to hold the largest share in 2026, while the rare diseases segment is projected to register the highest CAGR during the forecast period.
By end user, the pharmaceutical companies segment is expected to hold the largest share in 2026, while the biotechnology companies segment is projected to register the highest CAGR during the forecast period.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 26.8 Billion |
| Market Size in 2026 | USD 9.4 Billion |
| Market Size in 2025 | USD 7.8 Billion |
| Revenue Growth Rate (2026-2036) | CAGR of 11.0% |
| Format | PDF, Excel & Cloud Portal · 288 pages |
| Dominating Trial Model | Hybrid Trials (On-site + Remote) |
| Fastest Growing Trial Model | Fully Virtual Trials |
| Dominating Component | Software & Platforms |
| Fastest Growing Component | Devices & Infrastructure (Wearables) |
| Dominating Phase | Phase III |
| Fastest Growing Phase | Phase II |
| Dominating Therapeutic Area | Oncology |
| Fastest Growing Therapeutic Area | Rare Diseases |
| Dominating Indication Type | Chronic Diseases |
| Fastest Growing Indication Type | Rare Diseases |
| Dominating End User | Pharmaceutical Companies |
| Fastest Growing End User | Biotechnology Companies |
| Dominating Geography | North America |
| Fastest Growing Geography | Asia-Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
Report overview
Segments covered: trial model, component, phase, therapeutic area, indication type, end user.
According to the Tufts Center for the Study of Drug Development's 2025 impact report, majority of pharmaceutical sponsors incorporated at least some decentralized or virtual trial elements in their clinical programs in 2024, marking the transition of virtual and decentralized clinical trial approaches from pandemic-era emergency adoption to permanent mainstream practice in pharmaceutical R&D.
Virtual clinical trials, also commonly referred to as decentralized clinical trials (DCTs), are a new paradigm for conducting clinical research that uses digital technologies to enable patients to participate in trials primarily or entirely from their homes or local healthcare settings rather than requiring repeated visits to designated clinical study sites. The virtual trial technology stack includes telemedicine platforms for remote investigator consultations, eConsent systems for fully digital informed consent, eCOA and ePRO applications for electronic capture of patient-reported and clinician-assessed outcome data, wearable sensors for continuous physiological monitoring, direct-to-patient drug delivery logistics, and home nursing visit coordination. These elements can be combined in different proportions to create fully virtual trials where no site visit is required, hybrid trials where some site visits are retained for specific procedures, or site-based digital trials where conventional site visits are enhanced with digital data collection tools.
The market is growing rapidly because the regulatory, commercial, and operational case for virtual trial approaches has been definitively established. The FDA's September 2023 final guidance on decentralized clinical trials, which provides clear direction on how sponsors can design and conduct DCTs for investigational new drug applications and biologics license applications, removed the primary regulatory uncertainty that had previously slowed DCT adoption. The EMA issued its parallel reflection paper in 2023 providing equivalent European regulatory clarity. Tufts CSDD research reinforces that patient recruitment remains one of the biggest operational bottlenecks in conventional clinical trials, and virtual or decentralized approaches can help broaden access for patients who face barriers such as distance, work schedules, or mobility constraints.
Report infographic
Market dynamics
7 factors across 3 forcesNeed to Improve Patient Recruitment & Retention
Patient recruitment failure is the single most common cause of clinical trial delay and budget overrun, with the Tufts CSDD's 2025 analysis confirming that approximately 80-85% of clinical trials fail to meet their original enrolment timeline, adding an average of four to six months to study duration. The geographic constraint of conventional site-based trials, which require patients to live within a manageable distance of a designated clinical site, structurally excludes the majority of potentially eligible patients in most therapeutic areas. A 2025 analysis published in Clinical Trials journal found that decentralized trial elements can improve enrollment speed, with particularly strong benefits in patient groups that face travel, time, or mobility barriers, including rare disease, neurology, and working-age populations.
From a commercial perspective, the importance of improving recruitment efficiency is further amplified by sustained growth in pharmaceutical R&D investment. Organizations such as Pharmaceutical Research and Manufacturers of America highlight the scale of industry spending on drug development, where delays in patient recruitment remain a major contributor to cost inflation. As a result, virtual and decentralized trial models that can demonstrably improve enrolment speed and patient accessibility present a compelling value proposition across the clinical research ecosystem.
Increasing Cost & Complexity of Traditional Trials
The cost of clinical development has been increasing consistently, with Deloitte's 2025 Measuring the Return from Pharmaceutical Innovation report estimating the average cost to bring a drug to market at approximately USD 2.23 billion, including capital costs of failed programs. Site management, patient travel reimbursement, and clinical monitoring account for a very large share of Phase II and Phase III trial operational costs, and these are precisely the cost categories that virtual trial approaches most directly reduce by eliminating site visits, replacing on-site monitoring with risk-based remote monitoring, and removing patient travel costs entirely. IQVIA’s clinical-operations materials and broader industry research suggest that decentralized trial elements can reduce operational burden and improve efficiency, but the magnitude of savings varies by study design, therapeutic area, and how extensively decentralized methods are used.
Table of contents
14 chapters · 162 sections · 288 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Trial Model | Hybrid Trials | Fully virtual trials |
| By Component | Software & Platforms | Devices and infrastructure |
By Trial Model
- Hybrid Trials to Hold the Largest Share
- The global market for virtual clinical trials is segmented into fully virtual trials, hybrid trials (on-site and remote), and site-based digital trials.
- The hybrid trials segment is expected to account for the largest share of the global virtual clinical trials market.
- Hybrid trials, which combine conventional site visits for specific procedures including imaging, blood draws, and physical examinations with remote virtual elements for assessments that can be conducted at home, represent the most commercially adopted trial design because they allow sponsors to retain the site infrastructure and investigator relationships of conventional trials while adding the patient access and burden reduction benefits of virtual elements.
- However, the fully virtual trials segment is projected to register the highest CAGR during the forecast period.
- As the evidence base for fully remote trial conduct grows, as FDA and EMA guidance provides greater regulatory clarity on fully virtual designs, and as specialist VCT platform companies develop more complete end-to-end remote trial solutions, the proportion of trials running fully virtual protocols is expected to grow substantially from its currently smaller base.
- Therapeutic areas including dermatology, pain management, and certain mental health indications are already demonstrating that fully remote assessment can deliver high-quality primary endpoint data.
By Component
- Software & Platforms to Hold the Largest Share
- The software and platforms segment is expected to account for the largest share of the global virtual clinical trials market.
- Clinical trial management systems, eConsent platforms, and eCOA solutions are the operational backbone of any virtual trial and are required by every VCT regardless of the degree of decentralization.
- Veeva Systems, Oracle's clinical platform division, and Medidata Solutions (Dassault Systemes) are the largest platform suppliers and generate substantial recurring subscription revenues from their large installed bases across the pharmaceutical and CRO community.
- However, the devices and infrastructure segment, particularly wearables, is projected to register the highest CAGR during the forecast period.
- The progressive validation of wearable-collected clinical endpoints and the growing number of regulatory submissions incorporating wearable data are driving rapidly expanding investment in wearable device selection, procurement, provisioning, and data integration for VCTs.
- The clinical wearable market for trials is growing from a smaller base and represents the newest and fastest-scaling component category in the VCT ecosystem.
Geographic analysis
North America
Largest shareNorth America is expected to account for the largest share of the global virtual clinical trials (VCT) market in 2026. The United States remains the world’s leading clinical research market and the most advanced in terms of VCT adoption, supported by its dominant position in pharmaceutical and biotechnology R&D. The country benefits from a highly developed clinical research infrastructure, a strong base of innovative sponsors, and a mature ecosystem of contract research organizations and technology providers. A key enabler of this leadership is the regulatory clarity provided by the U.S. Food and Drug Administration, particularly through its comprehensive guidance on decentralized clinical trials. This framework has created a supportive environment for the design and execution of virtual and hybrid trial models. The United States also hosts the largest number of trials incorporating decentralized elements, reflecting both early adoption and strong sponsor confidence. In addition, North America is home to several leading VCT technology companies, including Medable, Science 37, ObvioHealth, Thread Research, and Curebase. Their presence reinforces the region’s technological and commercial leadership. Canada further contributes to regional growth through increasing clinical research activity and evolving regulatory support for decentralized approaches under Health Canada.
Asia-Pacific
Fastest growthHowever, the Asia-Pacific virtual clinical trials market is projected to grow at the fastest rate during the forecast period. The region offers a compelling combination of large and diverse patient populations, a growing base of skilled clinical investigators, and cost-efficient trial execution environments. Regulatory frameworks across key markets are increasingly aligning with global standards, enabling broader adoption of decentralized and hybrid trial models. Countries such as Japan, South Korea, China, and Singapore are playing a central role in this growth. Japan’s Pharmaceuticals and Medical Devices Agency has introduced guidance aligned with international frameworks, while South Korea’s Ministry of Food and Drug Safety is actively supporting digital health and clinical trial innovation. China’s National Medical Products Administration is progressively incorporating digital approaches into its clinical trial regulations, with increasing adoption of hybrid models by domestic sponsors and CROs.
Competitive landscape
- Medable Inc. (U.S.)
- Science 37 Holdings Inc. (U.S.)
- Parexel International Corporation (U.S.)
- IQVIA Inc. (U.S.)
- ICON plc · Ireland
- Labcorp Drug Development (U.S.)
- Oracle Corporation Clinical Platforms (U.S.)
- Veeva Systems Inc. (U.S.)
- Medidata Solutions/Dassault Systemes (U.S./France)
- Signant Health (U.S.)
- Clario (U.S./UK)
- Castor EDC · Netherlands
- ObvioHealth (U.S.)
- Thread Research (U.S.)
- Curebase (U.S.)
Frequently asked questions
The global virtual clinical trials market is expected to reach USD 26.8 billion by 2036 from an estimated USD 9.4 billion in 2026, at a CAGR of 11.0% during the forecast period 2026-2036.
Cite this report
Meticulous Research. (2026). Virtual Clinical Trials (VCT) Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MRHC - 1041966). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/virtual-clinical-trials-market-6649