Clinical Trials Market (2025-2032)
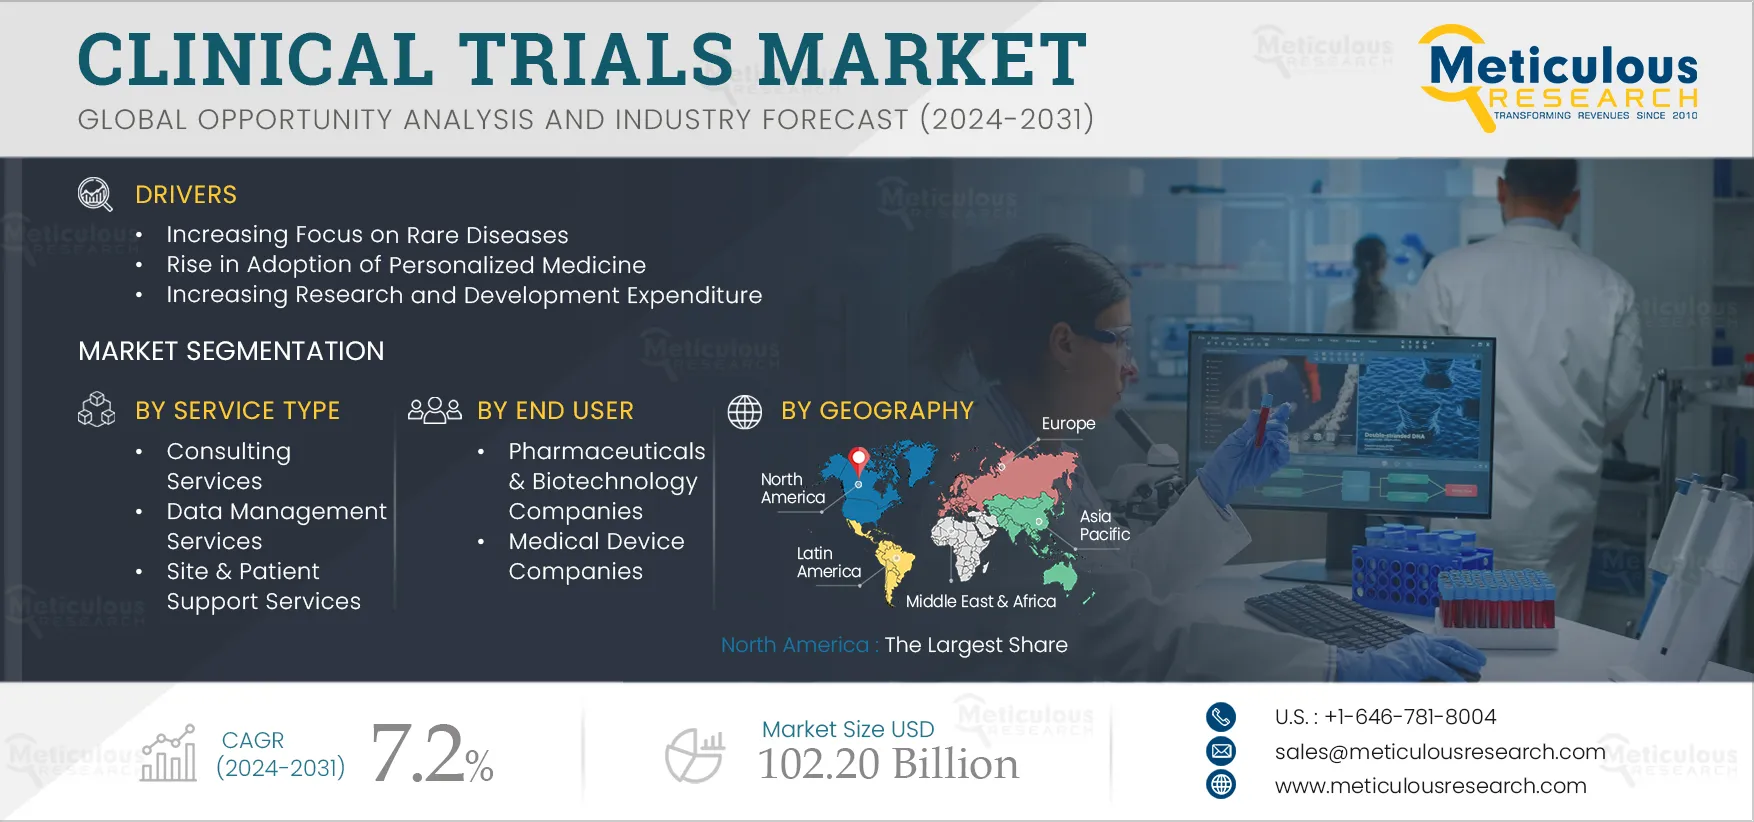
The Clinical Trials Market is projected to reach $102.20 billion by 2032 from an estimated USD 67.8 in 2025, growing at a CAGR of 7.2% from 2025 to 2032.
- Published
- Jun 2024
- Pages
- 230
- Format
- PDF + Excel
- Report ID
- MRHC - 1041251
- Base year
- 2024
- 2032 · FORECAST
- $102.2B
- 2032
- $102.2B
- CAGR 2025–2032
- 7.2%
2024 baseline · 2025–2032 forecast at 7.2% CAGR · hover a bar for the value
Key highlights
By Phase: In 2025, the Phase III Segment to Dominate the Clinical Trials Market
By Service Type: In 2025, the Patient Recruitment Services Segment is Projected to Witness the Fastest Growth in the Forecast Period
By Therapeutic Area: In 2025, the Oncology Segment to Dominate the Clinical Trials Market
By End Users: In 2025, the Pharmaceuticals & Biotechnology Companies Segment to Dominate the Clinical Trials Market
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 230 |
| Format | |
| Forecast Period | 2025-2032 |
| Base Year | 2024 |
| CAGR | 7.2% |
| Estimated Market Size (Value) | $102.20 Billion by 2032 |
| Segments Covered | By Phase · Pre-clinical Trial · Phase I · Phase II · Phase III · Phase IV · By Service Type · Consulting Services · Safety & Regulatory Compliance Services · Site & Patient Support Services · Marketing Authorization Holder Related Services · Data Management Services · Decentralized Clinical Trials (DCT) / Virtual Clinical Trials (VCT) Services · Patient Recruitment Services · Statistical Analysis Services · Bioanalytical Services · Other Services · (Note: Other Services include Sample storage and aliquoting services, Laboratory Services, Research Review Services, Manufacturing Services, Cold chain logistics and management Services, and In-Country Clinical Caretaker (ICCC) Services) · By Therapeutic Area · Oncology · Infectious Diseases · Cardiology · Metabolism & Endocrinology · Central Nervous System (CNS)/Neurology · Dermatology · Orthopedic and Rheumatology · Rare Diseases · Gastroenterology & Hepatology · Respiratory · Women's Health · Urology · Mental Health · Ophthalmology · By End User · Pharmaceuticals & Biotechnology Companies · Medical Device Companies · Other End Users · (Note: Other End Users Include Contract Research Organizations (CROs), Academics and Research Institutions, and Government Organizations) |
| Countries Covered | North America (U.S. and Canada), Europe (Germany, France, U.K., Italy, Spain, Poland, Belgium, and Rest of Europe), Asia-Pacific (Japan, China, India, Australia, South Korea, and Rest of Asia-Pacific), Latin America (Brazil, Mexico, Rest of Latin America), and Middle East & Africa |
| Key Companies | The key players operating in the global clinical trials market are Laboratory Corporation of America Holdings (U.S), Medpace, Inc. (U.S), Charles River Laboratories International, Inc. (U.S.), IQVIA Inc. (U.S.), Parexel International Corporation (U.S.), Syneos Health (U.S), ICON plc (Ireland), WuXi AppTec Co., Ltd. (China), Thermo Fisher Scientific Inc. (U.S), Fortrea Inc. (U.S), Celerion Inc. (U.S.), Novotech Health Holdings (Australia), SGS Société Générale de Surveillance SA. (Switzerland), CTI Clinical Trial and Consulting, Inc. (U.S.), and Linical USA, Inc. (U.S.). |
Report overview
Segments covered: end user. Regions: North America, Europe, Asia-Pacific, Latin America.
The growth of this market can be attributed to various factors, including increasing focus on rare diseases, rise in adoption of personalized medicine, increasing research and development expenditure, and improving recruitment in clinical trials resulting in the retention of participants.
Furthermore, patient-centric clinical trials using the Internet of Medical Things (IoMT), advancements in cloud-based systems for pharmacovigilance, and integration of AI in clinical trials are expected to offer growth opportunities.
Report infographic
Market dynamics
5 factors across 3 forcesIncreasing Focus on Rare Diseases
Rare diseases are characterized by a wide range of symptoms and signs that vary not only from disease to disease but also from patient to patient suffering from the same condition. According to the National Organization for Rare Disorders, Inc. (U.S.), more than 10,000 rare diseases have affected approximately 30 million Americans. Additionally, according to the European Commission, up to 36 million people in the European Union live with a rare disease, and more than 6000 distinct rare diseases prevail in the European Union. Owing to the increasing cases, various companies have started clinical trials for rare diseases. For instance, Pfizer Inc. (U.S.) conducted clinical trials for hemophilia, transthyretin amyloidosis, and Duchenne muscular dystrophy. Also, in February 2025, AstraZeneca PLC (U.K.) proposed an innovative open-label clinical trial design before regulators for utilizing a control group from prior trials for neuromyelitis optica spectrum disorder (NMOSD), a rare autoimmune disease, instead of a placebo group. This also led to significant interest from the patient community. Thus, the increasing cases of rare diseases are expected to propel the demand for new drugs, which is expected to drive the clinical trials market.
Increasing Pharmaceutical R&D Expenditure
Pharmaceutical companies constantly focus on R&D, which is a core aspect of drug development processes. The biotechnology industry also invests heavily in R&D to cater to the growing demand for innovation and new medical breakthroughs. The importance of R&D is evident due to the rising number of drug approvals. For instance, according to the Congressional Budget Office report of April 2021, the expenditure on research and development has risen by nearly 50 percent in the years 2015 to 2019. Clinical trials have allowed the pharmaceutical industry to develop precision medicines and discover new biomarkers in a shorter period and with low costs. Increasing R&D investments in the pharmaceutical & biotechnology sectors are expected to boost the utilization of advanced clinical trial services, driving the clinical trials market.
Table of contents
12 chapters · 137 sections · 230 pages · click to expandSegmental analysis
| Segment | Largest share (2025) | Fastest growth (2025–2032) |
|---|---|---|
| By Phase | Phase III | — |
| By Service Type | — | Fastest growth rate of the |
| By Therapeutic Area | Oncology | — |
| By End User | Pharmaceuticals & Biotechnology Companies | — |
By Phase
- The Phase III Segment to Dominate the Clinical Trials Market
- The phase III segment is expected to account for the largest share of 68.4% of the clinical trials market.
- Phase III clinical trials use large groups of people to observe the adverse effects of treatment and utilize sophisticated services for studying the efficacy and safety of the drugs.
- Such factors have contributed to the largest share of the segment.
- Additionally, many pharmaceutical and biotechnology companies outsource their phase III clinical trials to service providers has supported the largest share of the segment.
By Service Type
- The Patient Recruitment Services Segment is Projected to Witness the Fastest Growth in the Forecast Period
- The fastest growth rate of the segment is attributed to the increasing number of drugs reaching the phase III clinical trials, the large number of patients pool with required medical conditions, and rising spent on patient recruitment and screening process.
By Therapeutic Area
- The Oncology Segment to Dominate the Clinical Trials Market
- The oncology segment is expected to account for the largest share of 33.2% of the clinical trials market.
- The largest share of the segment is attributed to the increasing prevalence of cancer, increasing R&D for cancer drugs, and technological advancements in cancer treatments.
- For instance, cancer is the leading cause of death worldwide.
- The most common cancers are breast, lung, colon, rectum, and prostate cancers.
- According to the World Health Organization February 2022 report, approximately 10 million deaths in 2020 were caused due to cancer.
By End User
- The pharmaceuticals & biotechnology companies’ segment is expected to account for the largest share of the clinical trials market.
- The largest share of the segment is attributed to the high investments in R&D for the development of new drugs and therapies by pharmaceutical and biotechnology companies, increasing demand for innovative therapies for various diseases leading to high demand from pharmaceutical and biotechnology companies for outsourcing clinical trials for bringing new treatments to market.
Geographic analysis
North America
Largest shareIn 2025, North America is expected to account for the largest share of 41.6% of the clinical trials market. North America's significant market share is attributed to an increase in R&D investments, a rise in the adoption of new technologies in clinical trials, and the presence of key market players in this region. For instance, in March 2025, Laboratory Corporation of America Holdings (U.S.) launched pTau217, a biomarker test for accelerating the path to diagnosis of Alzheimer’s disease, which is also used for clinical trials. Additionally, according to the National Library of Medicine (U.S.), as of April 2025, approximately 149,999 clinical trial studies are registered in the U.S.
Competitive landscape
- April 2025
Parexel International Corporation (MA) Corporation (U.S.) partnered with Palantir Technologies Inc. (U.S.) to utilize AI to enhance and accelerate the delivery of safe and effective clinical trials while maintaining the highest level of regulatory integrity and safety.
- June 2024
Syneos Health (U.S.) collaborated with uMotif Limited (U.K.) to accelerate clinical trials and to bring new therapies for patients through an efficient and faster end-to-end digital system that includes Electronic Patient-reported Outcomes (ePRO), and Electronic Clinical Outcome Assessment (eCOA) capabilities.
- September 2024
ICON plc (Ireland) launched a next-generation Clinical Trial Tokenisation solution, which combines all the important components for allowing the collation of patient data in a discreet, confidential, and non-intrusive way with Privacy Protected Record Linkage (PPRL) across source and time.
- November 2024
Ichor Life Sciences, Inc. (U.S.) launched Ichor Clinical Trials Services. The newly launched service will combine a spectrum of clinical trial solutions ranging from individual services to full CRO services.
- Laboratory Corporation of America Holdings (U.S)
- Medpace, Inc. (U.S)
- Charles River Laboratories International, Inc. (U.S.)
- IQVIA Inc. (U.S.)
- Parexel International Corporation (U.S.)
- Syneos Health (U.S)
- ICON plc · Ireland
- WuXi AppTec Co., Ltd. · China
- Thermo Fisher Scientific Inc. (U.S)
- Fortrea Inc. (U.S)
- Celerion Inc. (U.S.)
- Novotech Health Holdings · Australia
- SGS Société Générale de Surveillance SA · Switzerland
- CTI Clinical Trial and Consulting, Inc. (U.S.)
- Linical USA, Inc. (U.S.)
Frequently asked questions
The Clinical Trials Market refers to the industry involved in conducting research studies to evaluate the safety and efficacy of drugs, treatments, or medical devices before they are brought to market.
Cite this report
Meticulous Research. (2024). Clinical Trials Market - Global Opportunity Analysis and Industry Forecast (2025-2032) (Report No. MRHC - 1041251). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/clinical-trials-market-5934