Clinical Trial Supplies Market (2024-2031)
The Clinical Trial Supplies Market was valued at $3.11 billion in 2023. This market is expected to reach $5.59 billion by 2031, from an estimated $3.33 billion in 2024, at a CAGR of 7.7% during the forecast period 2024-2031. Clinical Trial Supplies Market Size & Forecast Clinical trial supplies
- Published
- Feb 2024
- Pages
- 260
- Format
- PDF + Excel
- Report ID
- MRHC - 104373
- Base year
- 2023
- 2023 · BASELINE
- $3.11B
- 2031
- $5.59B
- CAGR 2024–2031
- 7.7%
2023 baseline · 2024–2031 forecast at 7.7% CAGR · hover a bar for the value
Key highlights
The Phase III Segment Projected to Register the Highest CAGR During the Forecast Period
The Logistics & Distribution Segment Expected to Account for the Largest Market Share in 2024
The Biologics Segment Projected to Register the Highest CAGR During the Forecast Period
The Oncology Segment Expected to Dominate the Market in 2024
The Pharmaceutical & Biotechnology Companies Segment Expected to Account for the Largest Market Share in 2024
North America to be the Largest Regional Market
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | ~260 |
| Format | |
| Forecast Period | 2024-2031 |
| Base Year | 2023 |
| CAGR | 7.7% |
| Estimated Market Size (Value) | $5.59 Billion by 2031 |
| Segments Covered | By Clinical Phase · Phase I · Phase II · Phase III · Phase IV · By Service · Manufacturing · Packaging & Labeling · Logistics & Distribution · Documentation · Other Services · (Note: Other services include comparator sourcing and clinical returns.) · By Type · Medical Devices · Biologics · Small Molecules · By Therapeutic Area · Cardiology · Infectious Diseases · Oncology · CNS · Inflammation & Immunology · Metabolic Disorders · Respiratory Diseases · Other Therapeutic Areas · (Note: Other therapeutic areas include ophthalmology, pediatrics, gynecology, rare diseases, and blood disorders.) · By End User · Pharmaceutical & Biotechnology Companies · Contract Research Organizations · Medical Device Manufacturers · Clinical Research Organizations |
| Regions/Countries Covered | North America (U.S. and Canada), Europe (Germany, France, U.K., Italy, Spain, RoE), Asia-Pacific (China, Japan, India, RoAPAC), Latin America (Brazil, Mexico, RoLATAM), and the Middle East & Africa |
| Key Companies Profiled | Catalent, Inc. (U.S.), NUVISAN GmbH (Germany), Thermo Fisher Scientific Inc. (U.S.), Almac Group (U.K.), Eurofins Scientific SE (Luxembourg), Parexel International (MA) Corporation (U.S.), Marken (U.S.), Biocair International Limited (U.K.), KLIFO (Denmark), Piramal Pharma Limited (India), Movianto Group (U.K.), and ICON plc (Ireland) |
Report overview
Segments covered: clinical phase, phase i, phase ii, phase iii, phase iv, service, manufacturing, packaging & labeling, logistics & distribution, documentation, other service, type, medical device, biologic, small molecule, therapeutic area, cardiology, infectious disease, oncology, cns, inflammation & immunology, metabolic disorder, respiratory disease, other therapeutic area, end user, pharmaceutical & biotechnology company, contract research organization, medical device manufacturer, clinical research organization. Regions: North America, Europe, Asia-Pacific, Latin America.
Clinical trial supplies are products and services required during clinical trials, including expertise/assistance, 24-hour collection and delivery of biological specimens (including infectious samples), investigational drugs, kits, and study materials. Clinical trial supplies must be properly maintained and managed to comply with regulatory guidelines and meet quality standards. Clinical trial supplies are transported, stored, and tracked according to regulatory requirements. Clinical trial supply services include logistic, shipping, and distribution services, inventory management services, temperature monitoring, labeling, and primary and secondary packaging.
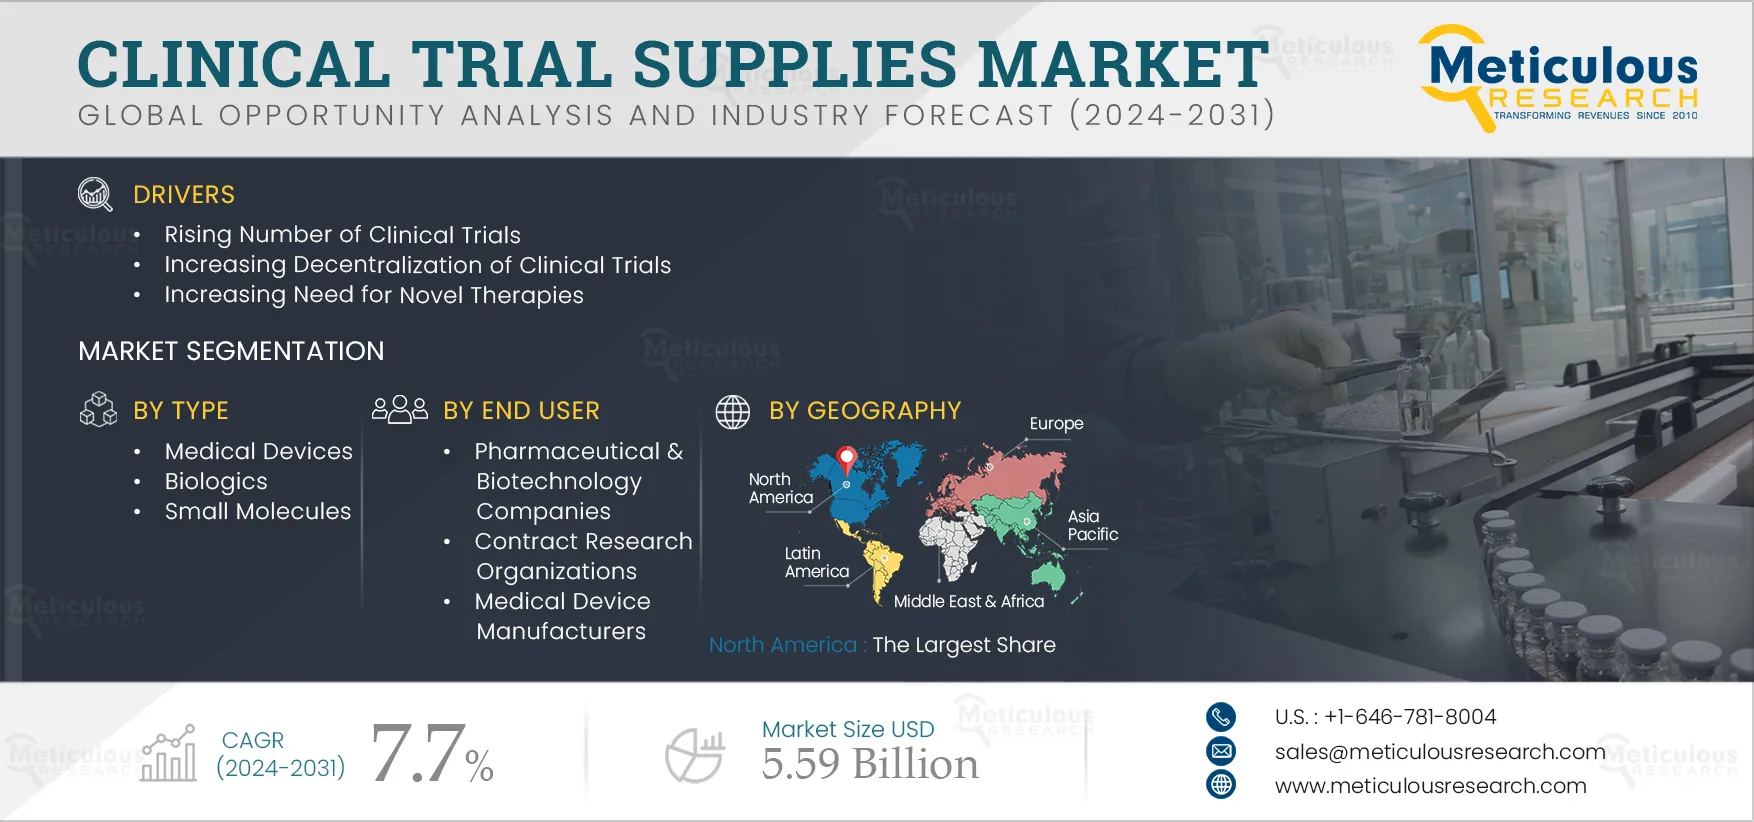
The growth of this market is mainly driven by the rising number of clinical trials, the increasing decentralization of clinical trials, increasing approvals for generic drugs & biopharmaceuticals, increasing R&D expenditures among pharmaceutical & biopharmaceutical companies, and the rising need for novel therapies. However, the high costs of drug development restrain the growth of this market.
Furthermore, emerging economies and drug patent expirations are generating market growth opportunities. However, changes in the regulatory landscape and clinical trial failures in cases of rare diseases are major challenges impacting market growth.
Report infographic
Market dynamics
2 factors across 1 forceIncreasing Number of Clinical Trials Driving Market Growth
Pharmaceutical companies constantly focus on Research and Development (R&D), which are the core of drug development processes. The biotechnology industry also continues to witness substantial growth due to increased investments in R&D to cater to the growing demand for innovation and new medical breakthroughs. According to the National Investment Promotion and Facilitation Agency (India), in 2022, India invested $1 billion in biotechnology R&D. In September 2022, the U.S. government announced federal funding of $2 billion to support the biotechnology and biomanufacturing sector. Growing R&D spending has increased the focus on efficient clinical trials management. Additionally, the number of drug approvals is gradually increasing, boosting the adoption of clinical trial supply services for efficient management of clinical trials. For instance, in 2023, the Center for Drug Evaluation and Research (CDER) approved 55 novel drugs, increasing from 37 drugs in 2022. Thus, high R&D investments in the life sciences sector are expected to drive the adoption of clinical trial supplies.
Most companies and CROs are using clinical trial supply services to allow researchers to manage all activities related to the setup, conduction, and closeout of clinical trials. These services facilitate planning, preparation, monitoring, tracking, reporting, and compliance.
Additionally, with the increasing number of clinical trials, pharmaceutical companies are focusing more on drug pipelines such as antiviral drugs, orphan drugs, and immune-oncology drugs. As the number of drugs in the pipeline is increasing, the number of clinical trials is also increasing, supporting the growth of the clinical trial supplies market. According to ClinicalTrials.gov, the number of clinical trials increased to 477,237 in 2023 from 399,484 in 2021.
Rising Adoption of Generic Drugs & Biopharmaceuticals Driving the Demand for Clinical Trial Supplies
The preference for biopharmaceuticals is rising due to their ability to target specific molecules, lower side effects, and high activity and specificity. Biopharmaceuticals are increasingly being used for treating Immune-mediated Inflammatory Diseases (IMIDs), including rheumatic diseases, such as Rheumatoid Arthritis (RA), Inflammatory Bowel Disease (IBD), and cancer. The demand for generic drugs is also increasing as they are available at lower costs and help save on drug expenditure. According to the U.S. FDA, 91% of all prescriptions in the U.S. recommend generic drugs, with more than 32,000 generic drugs approved by the FDA as of 2022.
Clinical trial supplies are essential in the biopharmaceuticals sector to ensure standardized and high-quality products. Biopharmaceutical firms can ensure constant adherence to quality standards, compliance with regulations, and continual improvements in organizational processes by using clinical trial supplies.
Table of contents
13 chapters · 106 sections · 260 pages · click to expandSegmental analysis
| Segment | Largest share (2024) | Fastest growth (2024–2031) |
|---|---|---|
| By Clinical Phase | — | Phase III |
| By Service | Logistics & Distribution Segment Expected | — |
| By Type | — | Biologics |
| By Therapeutic Area | Oncology Segment Expected | — |
| By End User | Pharmaceutical & Biotechnology Companies Segment Expected | — |
By Clinical Phase
- The Phase III Segment Projected to Register the Highest CAGR During the Forecast Period
- The phase III segment is expected to register the highest CAGR during the forecast period.
- Phase III clinical trials show researchers the rare or long-term side effects of a medication.
- The demand for clinical trial supplies is the highest in phase III due to the higher complexity of phase III clinical trials compared to other phases.
- The complexity of phase III is associated with the recruitment of study participants for randomized clinical trials.
- According to Allucent (U.S.), a provider of drug development solutions, every year, about 30% of drugs in phase III fail to reach approval.
- Owing to the high failure rate of phase III clinical trials, the need for the careful management and planning of clinical trial supplies is the highest in phase III.
By Service
- The logistics & distribution segment is expected to account for the largest share of the clinical trial supplies market.
- The logistic challenges in clinical trials are increasing the demand for logistic & distribution services.
- Logistic & distribution challenges include drugs getting stalled in cross-border customs in case of global trials, a lack of sufficient ancillary supplies to serve patients, and damage to patient samples during shipping.
- Additionally, key players are collaborating with market stakeholders to provide integrated solutions for clinical trial supplies.
- For instance, in January 2023, Cryoport, Inc. (U.S.) collaborated with Syneos Health (U.S.) to integrate clinical trial supply services offered by Syneos Health with IntegriCell, Cryoport’s platform providing standardized apheresis collection, cryopreservation, storage, and distribution for cell & gene therapies.
By Type
- The Biologics Segment Projected to Register the Highest CAGR During the Forecast Period
- The biologics segment is expected to register the highest CAGR during the forecast period.
- The high growth of this segment is driven by the growing demand for biologics, increasing research on the development of biosimilar drugs, and the increasing use of biologics for the treatment of autoimmune diseases.
- Additionally, increasing approvals for biologics support the segment’s highest CAGR.
- According to the U.S. FDA, in 2022, 40.5% of biologics were approved, compared to 28% in 2021.
By Therapeutic Area
- The Oncology Segment Expected to Dominate the Market in 2024
- The oncology segment is expected to account for the largest share of the market.
- The segment’s large share is attributed to the increasing incidence of cancer, the rising focus on developing novel therapies for the treatment of cancer, and the increasing number of drugs in the R&D pipeline for cancer treatment.
- Additionally, the increasing percentage of oncology drugs in clinical trials supports the segment’s large market share.
- For instance, in the third quarter of 2023, the U.S. FDA and the European Medicines Agency (EMA) collectively approved over 36 oncology drugs compared to 30 in the third quarter of 2022.
By End User
- The pharmaceutical & biotechnology companies segment is expected to account for the largest share of the market.
- The segment’s large market share is attributed to significant investments in research and development (R&D) and infrastructure development by pharmaceutical & biotechnology companies.
- The funding for research laboratories is increasing due to the rising demand for new drugs and therapies.
- For instance, according to the International Federation of Pharmaceutical Manufacturers & Associations (IFPMA), global pharmaceutical R&D expenditure is expected to reach $213 billion in 2026 from $179 billion in 2020.
Geographic analysis
North America
Largest shareIn 2024, North America is expected to account for the largest share of the clinical trial supplies market. North America's significant market share is attributed to several factors, including substantial R&D investments by pharmaceutical and biotechnology companies for drug and biomarker development, the growing prevalence of chronic diseases, increased healthcare expenditures, the presence of key market players in the region, and favorable government initiatives supporting research and development. The surge in R&D spending by pharmaceutical companies is anticipated to drive the demand for clinical trial supplies, which are crucial for successful clinical trials in the pharmaceutical sector. For instance, in 2022, overall pharmaceutical expenditures in the U.S. grew by 9.4% compared to 2021. North America to be the Largest Regional Market
Competitive landscape
The report offers a competitive landscape based on an extensive assessment of the product offerings and geographic presence of leading market players and the key growth strategies adopted by them over the past few years (2020–2024). The key players operating in the clinical trial supplies market are Catalent, Inc. (U.S.), NUVISAN GmbH (Germany), Thermo Fisher Scientific Inc. (U.S.), Almac Group (U.K.), Eurofins Scientific SE (Luxembourg), Parexel International (MA) Corporation (U.S.), Marken (U.S.), Biocair International Limited (U.K.), KLIFO (Denmark), Piramal Pharma Limited (India), Movianto Group (U.K.), and ICON plc (Ireland).
- Catalent, Inc. (U.S.)
- NUVISAN GmbH · Germany
- Thermo Fisher Scientific Inc. (U.S.)
- Almac Group (U.K.)
- Eurofins Scientific SE · Luxembourg
- Parexel International (MA) Corporation (U.S.)
- Marken (U.S.)
- Biocair International Limited (U.K.)
- KLIFO · Denmark
- Piramal Pharma Limited · India
- Movianto Group (U.K.)
- ICON plc · Ireland
Frequently asked questions
The clinical trial supplies market report covers the study of market segments by service, clinical phase, type, therapeutic area, and end user. This report also analyzes the clinical trial supplies market at the regional and country levels.
Cite this report
Meticulous Research. (2024). Clinical Trial Supplies Market - Global Opportunity Analysis and Industry Forecast (2024-2031) (Report No. MRHC - 104373). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/clinical-trial-supplies-market-5072