Veterinary Immunodiagnostics Market (2022-2029)
The Veterinary Immunodiagnostics Market is expected to record a CAGR of 9.3% during the forecast period 2022–2029 to reach $2.71 billion by 2029.
- Published
- Jun 2022
- Pages
- 200
- Format
- PDF + Excel
- Report ID
- MRHC - 104100
- Base year
- 2021
- 2029 · FORECAST
- $2.71B
- 2029
- $2.71B
- CAGR 2022–2029
- 9.3%
2021 baseline · 2022–2029 forecast at 9.3% CAGR · hover a bar for the value
Key highlights
The Consumables Segment to Dominate the Veterinary Immunodiagnostics Market in 2022
The ELISA Segment to Account for the Largest Market Share by 2029
The Livestock Segment to Account for the Largest Market Share by 2029
Asia-Pacific to Be the Fastest Growing Regional Market
Report summary
| Particulars | Details |
|---|---|
| Base Year | 2021 |
| Estimated Year | 2022 |
| Forecast Period | 2022–2029 |
| Market Size (2029) | USD 2.71 billion |
| CAGR (2022–2029) | 9.3% |
| Format | PDF, Excel & Cloud Portal · 200 pages |
| Segments Covered | By Product: Analyzers, Consumables Heartworm, Leukemia, Bovine Viral Diarrhea, Influenza, Foot & Mouth Disease, Blue Tongue, Bovine Tuberculosis, Bovine Herpes Virus, New Castle Disease, Avian Mycoplasma, Other Diseases · By Technology: ELISA Chemiluminescence Immunoassays, Fluorescent Immunoassays, Colorimetric Immunoassays · By Animal Type: Companion Animals Canine, Feline, Other Companion Animals, Ruminants, Swine, Poultry, Others · By End User: Reference Laboratories, Veterinary Hospitals & Clinics, PoC Testing · By Animal: Livestock, Companion |
| Countries Covered | Europe (RoE), Asia-Pacific (RoAPAC) |
| Key Companies | IDEXX Laboratories, Inc., Zoetis Inc., Thermo Fisher Scientific Inc., Heska Corporation, Randox Laboratories, Ltd, Neogen Corporation, QIAGEN N.V., Abaxis, Inc. |
Report overview
Segments covered: product, technology, animal type, end user, animal. Regions: Europe, Asia-Pacific.
The growth of this market is driven by the increasing prevalence of diseases in animals, the presence of disease-specific immunodiagnostic tests, and advancements in immunodiagnostic technology. Moreover, the increasing pet population and the rising demand for animal-derived foods support the growth of this market. Emerging economies are expected to create opportunities for the growth of this market.
However, inadequate veterinary diagnostics infrastructure in developing countries is expected to remain a major challenge to the growth of the veterinary immunodiagnostics market.
COVID-19 virus is a zoonotic disease, i.e., it emerged from an animal source. This has led to increased awareness among people regarding the health hazards of animals and animal-derived food products. Moreover, there were cases of COVID-19 infections in pets in several countries. These infected pets were found to be living with COVID-19-positive humans. For instance, in June 2020, the United States Department of Agriculture’s National Veterinary Services Laboratories (USDA NVSL) announced the first confirmed case of COVID-19 infection in a pet dog (German shepherd) in New York state. In response to these incidents, authorities such as the Centers for Disease Control and Prevention (CDC), in 2020, issued testing guidelines for companion, livestock, zoo, and wild animals for epidemiological investigations. Moreover, scientists and researchers studied test kits for detecting COVID-19 infections in animals.
The pandemic had a mixed impact on the veterinary immunodiagnostics market. On one hand, it opened new opportunities for the development and research of tests for diagnosing COVID-19 infections in animals and increased awareness among people regarding the importance of animal diagnostics and health. On the other hand, the pandemic disrupted the supply chain leading to decreased consumption of animal-derived products. Travel restrictions further made it difficult for the companies and laboratories to procure, dispatch, and ship laboratory tools and equipment. However, this negative impact is expected to last for a short duration as the world is recovering from the pandemic and consuming animal-derived food products is resumed.
Several research studies have established the relation between zoonotic infections and global human outbreaks, the recent being SARS-CoV-2 (COVID-19 virus) pandemic. Early disease diagnosis and treatment in animals are crucial to avoid the spread of such infections in the future. As animals provide food for consumption, foodborne zoonotic diseases are caused by consuming food or water contaminated by pathogenic microorganisms. For instance, according to CDC, in 2020, nearly 18,462 cases of foodborne disease infections were witnessed in the U.S., including 4,788 hospitalizations and 118 deaths. The World Health Organization (WHO) states that the total productivity loss associated with foodborne disease in low-and middle-income countries was $110 billion in 2020.
Zoonotic Tuberculosis (TB) remains a poorly addressed and monitored disease in developing and underdeveloped countries. For instance, according to the WHO, in 2019, 140,000 new cases of zoonotic TB occurred globally, resulting in approximately 11,400 deaths. Africa carries the heaviest burden of disease and death due to zoonotic TB, followed by Southeast Asia.
Diabetes mellitus & heartworm disease are the most common diseases diagnosed in canines and felines. Diabetes Mellitus is a chronic disease that requires long-term monitoring and management. According to the 2019 Banfield Pet Hospital Report, there was a 79.7% increase in dogs with diabetes between 2006 and 2018, with 23.6 cases per 10,000 dogs. Similarly, the incidence of feline diabetes increased by 18.1% from 2006 to 2018, which is 67.6 cases per 10,000 cats.
Report infographic
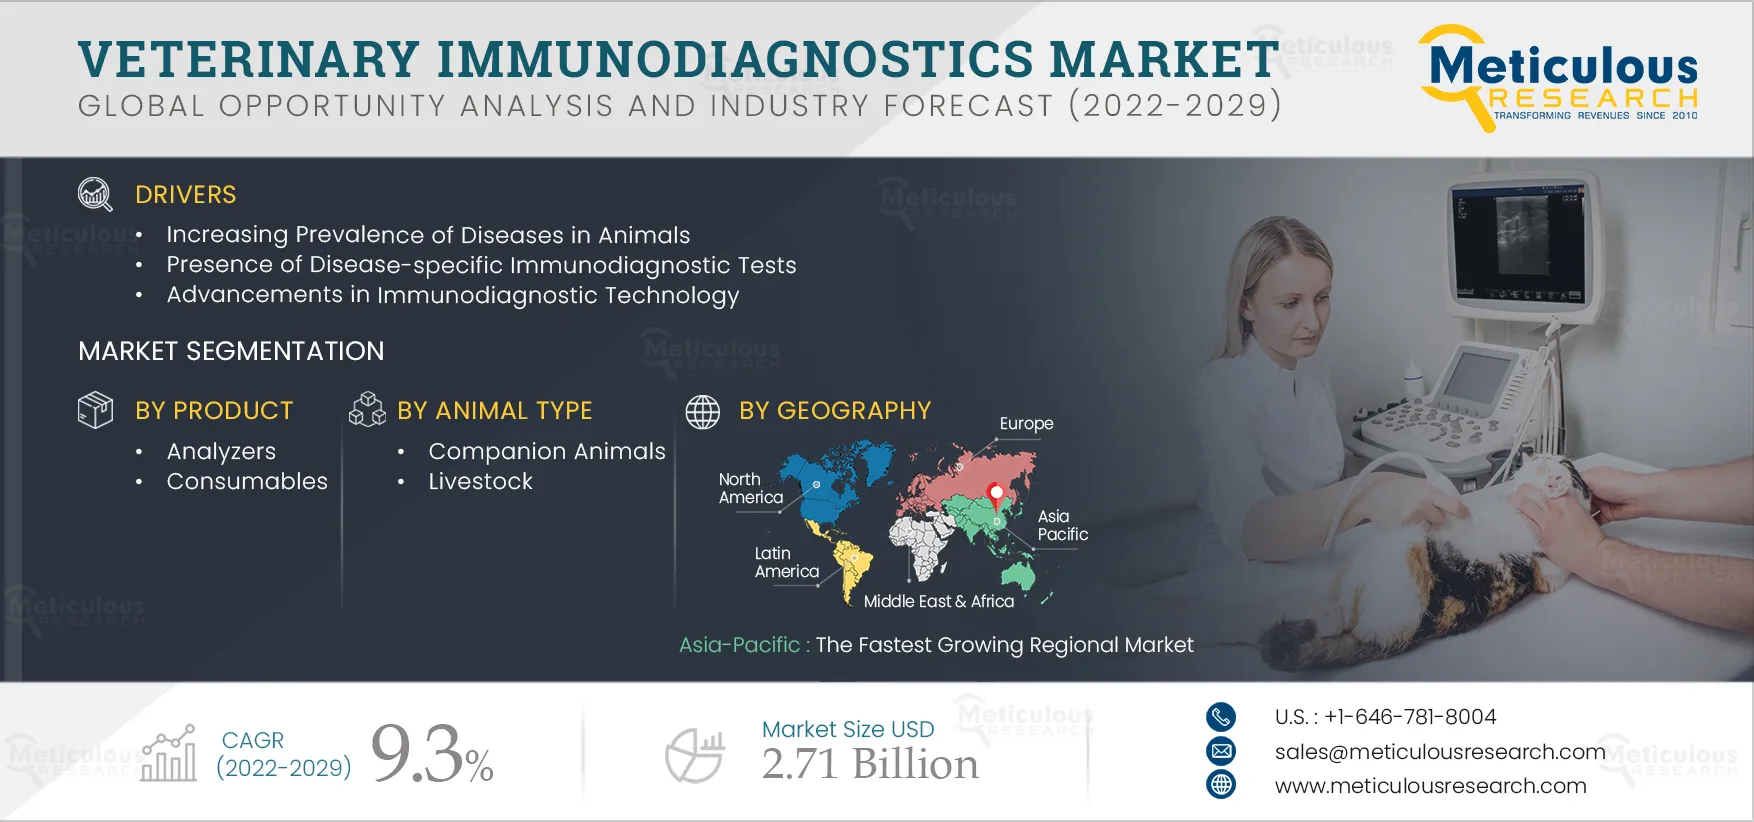
Table of contents
12 chapters · 96 sections · 200 pages · click to expandSegmental analysis
| Segment | Largest share (2022) | Fastest growth (2022–2029) |
|---|---|---|
| Other segments | Consumables | — |
| By Animal | Livestock | — |
Other segments
- The Consumables Segment to Dominate the Veterinary Immunodiagnostics Market in 2022
- The increased prevalence of zoonotic diseases among animals and the risk of infections crossing the species barrier and infecting humans drive the growth of this segment.
- The ELISA Segment to Account for the Largest Market Share by 2029
- The large market share of this segment is attributed to the continuous development of new biomarkers, cost-benefit, and growing adoption of automated platforms for ELISA.
By Animal
- The Livestock Segment to Account for the Largest Market Share by 2029
- The factors contributing to the growth of this segment are increasing demand for food production across the globe and awareness about animal health.
Geographic analysis
Asia-Pacific
Fastest growthThe high growth of the Asia-Pacific veterinary immunodiagnostics market is attributed to a large population of livestock and the rising incidence of various zoonotic diseases in the region. Asia-Pacific to Be the Fastest Growing Regional Market
North America
Largest shareIn 2022, North America is expected to dominate the veterinary immunodiagnostics market, while Asia-Pacific is expected to record the highest CAGR during the forecast period.
Competitive landscape
- IDEXX Laboratories, Inc.
- Zoetis Inc.
- Thermo Fisher Scientific Inc.
- Heska Corporation
- Randox Laboratories, Ltd
- Neogen Corporation
- QIAGEN N.V.
- Abaxis, Inc.
Frequently asked questions
The veterinary immunodiagnostics market report covers market sizes & forecasts for consumables, systems, and software used for animal diagnosis. The veterinary immunodiagnostics market study includes the value analysis of various segments and subsegments of the veterinary immunodiagnostics market at the regional and country levels.
Cite this report
Meticulous Research. (2022). Veterinary Immunodiagnostics Market - Global Opportunity Analysis and Industry Forecast (2022-2029) (Report No. MRHC - 104100). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/veterinary-immunodiagnostics-market-2897