Biomarkers Market (2025-2032)
The Biomarkers Market was valued at $69.76 billion in 2024. This market is expected to reach $201.33 billion by 2032, from an estimated $79 billion in 2025, at a CAGR of 14.3% during the forecast period 2025-2032. Biomarkers Market Size & Forecast The growth of this market can be attributed to various
- Published
- May 2024
- Pages
- 350
- Format
- PDF + Excel
- Report ID
- MRHC - 1041186
- Base year
- 2024
- 2024 · BASELINE
- $69.76B
- 2032
- $201.3B
- CAGR 2025–2032
- 14.3%
2024 baseline · 2025–2032 forecast at 14.3% CAGR · hover a bar for the value
Key highlights
By Biomarker Type: In 2025, the Safety Biomarkers Segment to Dominate the Biomarkers Market
By Offering: In 2025, the Consumables Segment to Dominate the Biomarkers Market
By Mechanism: In 2025, the Epigenetic Biomarkers Segment to Dominate the Biomarkers Market
By Profiling Technology: In 2025, the Immunoassay Segment to Dominate the Biomarkers Market
By Disease Type: In 2025, the Oncology Segment to Dominate the Biomarkers Market
By Application: In 2025, the Drug Discovery & Development Segment to Dominate the Biomarkers Market
By End User: In 2025, the Pharmaceutical & Biotechnology Companies Segment to Dominate the Biomarkers Market
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 350 |
| Format | |
| Forecast Period | 2025-2032 |
| Base Year | 2024 |
| CAGR | 14.3% |
| Estimated Market Size (Value) | $201.33 billion by 2032 |
| Segments Covered | By Biomarker Type · Efficacy Biomarkers · Prognostic Biomarkers · Pharmacodynamic Biomarkers · Surrogate Biomarkers · Predictive Biomarkers · Validation Biomarkers · Safety Biomarkers · By Offering · Consumables · Assay Kits · Reagents · Other Consumables · Services & Software · (Note: Other consumables include columns, filters, and microplates) · By Mechanism · Genetic Biomarkers · Epigenetic Biomarkers · Proteomic Biomarkers · Lipidomic Biomarkers · Other Mechanisms · (Note: Other mechanisms include metabolic biomarkers and inflammatory biomarkers) · By Profiling Technology · Immunoassay · ELISA · Western Blot · Protein Microarray · NGS · PCR · Mass Spectrometry · Chromatography · Other Technologies · (Note: Other technologies include flow cytometry, electrophoresis, and DNA microarray) · By Disease Type · Oncology · Cardiovascular Diseases · Infectious Diseases · Neurological Disorders · Diabetes and Other Metabolic Diseases · Other Diseases · (Note: Other diseases include autoimmune diseases, blood disorders, and CNS diseases) · By Application · Diagnostics · Drug Discovery and Development · Personalized Medicine · Clinical Research · Other Applications · (Note: Other applications include prognosis, risk assessment, and forensic) · By End User · Pharmaceutical & Biotechnology Companies · Hospitals · Diagnostic Laboratories · Other End Users · (Note: Other end users include academic & research institutes and forensics) |
| Countries Covered | North America (U.S. and Canada), Europe (Germany, France, U.K., Italy, Spain, Switzerland, Belgium, Netherlands, and Rest of Europe), Asia-Pacific (China, Japan, India, South Korea, Australia, and Rest of Asia-Pacific), Latin America, and Middle East & Africa |
| Key Companies | The key players operating in the biomarkers market are F. Hoffmann-La Roche AG (Switzerland), Merck KGaA (Germany), Epigenomics AG (Germany), Abbott Laboratories (U.S.), QIAGEN N.V. (Germany), Bio-Rad Laboratories (U.S.), Revvity Inc (U.S.), Siemens Healthineers AG (Germany), Mindray (China), Thermo Fisher Scientific Inc. (U.S.), Eurofins Scientific SE (France), bioMérieux SA (France), Agilent Technologies, Inc. (U.S.), and Quanterix Corp. (U.S.). |
Report overview
Segments covered: type, offering, application, disease type, end user. Regions: North America, Europe, Asia-Pacific.
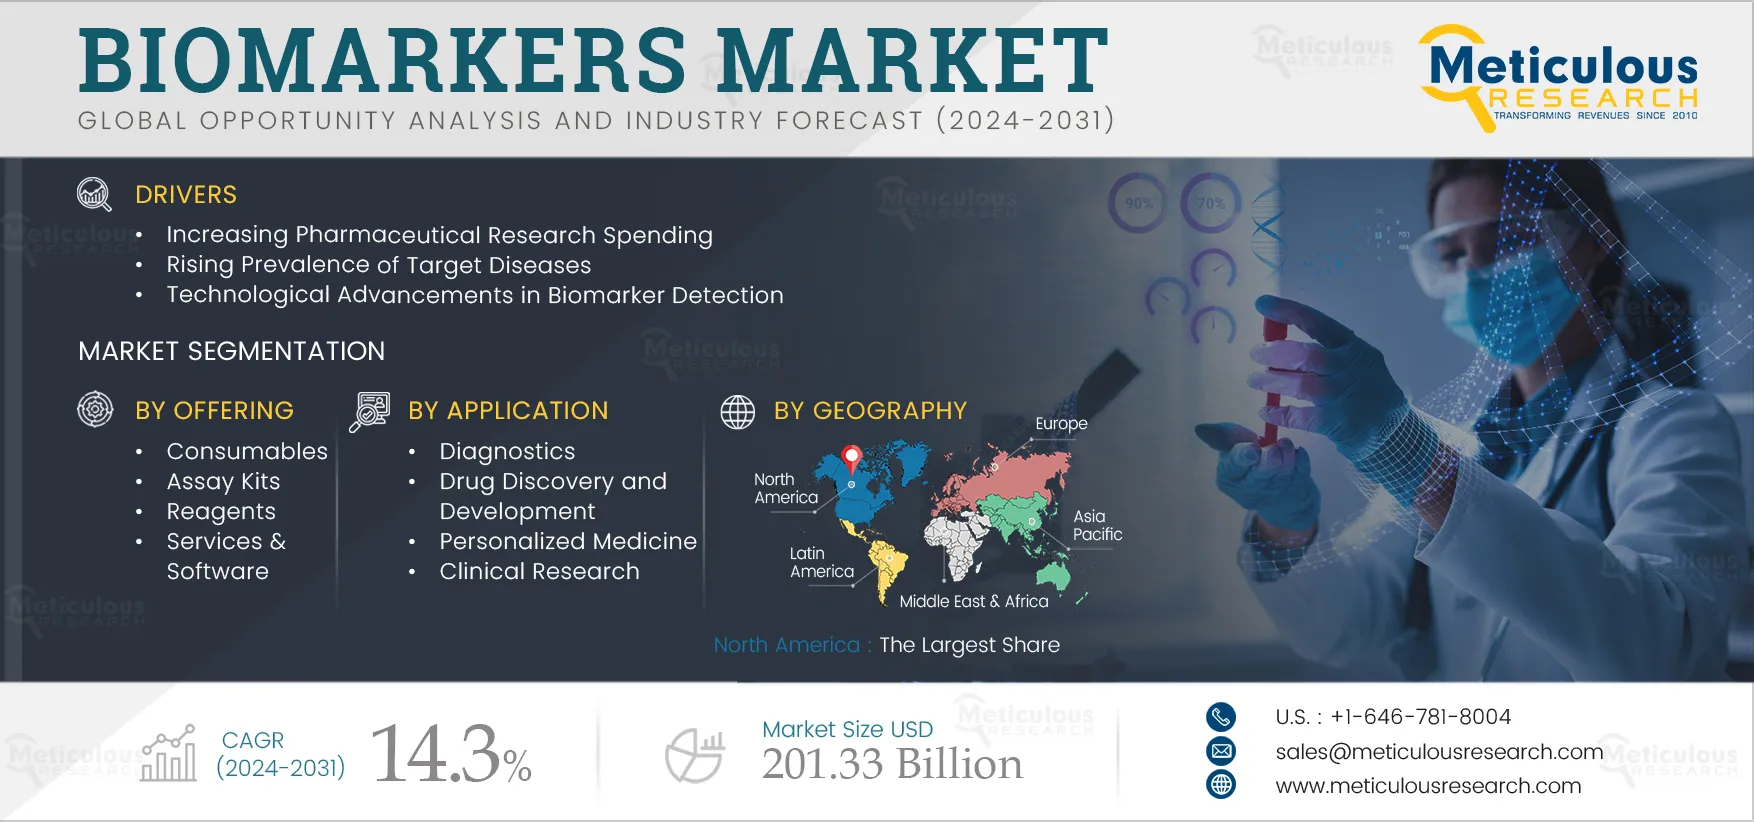
The growth of this market can be attributed to various factors, such as the increasing pharmaceutical research spending, rising prevalence of target diseases, technological advancements in biomarker detection, rising focus on clinical research, increasing funding for biomarker research, rising focus on early disease diagnosis, and application of biomarkers in multiple research areas. Furthermore, a rising focus on companion diagnostics, ongoing research on biomarkers, and a shift toward precision oncology are expected to offer growth opportunities.
Report infographic
Market dynamics
5 factors across 3 forcesRising Prevalence of Target Diseases
Biomarkers are either released by the human body in response to various diseases or by organs that are affected by the disease, such as tumors. Biomarkers are being used increasingly to detect several infectious and chronic diseases, such as cancer, neurological disorders, cardiovascular diseases, and others.
In the case of cancer, clinical biomarker testing involves the detection of molecules of DNA, protein metabolites, RNA, or transcription factors that are either produced by the tumor or as a response to the tumor. These biomarkers help in cancer diagnostics and also provide predictive and prognostic information to guide patient care. The prevalence of cardiovascular diseases, cancer, and infectious diseases is increasing. According to GLOBOCAN, the global prevalence of all types of cancer is expected to increase by 63.4% by 2045 from 2022. The rising prevalence of cancer is increasing the demand for biomarker testing.
Increasing Funding for Biomarker Research
Biomarker research has gained traction in recent years owing to its applications in early disease diagnosis. The key players operating in the market and government agencies are raising funding and providing grants for advancements in biomarkers research and testing. For instance,
- In November 2024, the Michael J. Fox Foundation (U.S.), a non-profit organization working on the treatment of Parkinson’s disease, provided Octave Bioscience, Inc. (U.S.) with a USD 10 million grant to discover, develop, and validate a custom protein biomarker panel to measure Parkinson’s disease activity and progression in the clinic.
- In August 2024, the National Comprehensive Cancer Network (U.S.), an alliance of 33 cancer centers in the U.S. in partnership with Fight Colorectal Cancer (U.S.), a patient empowerment organization and Pfizer Inc. (U.S.), announced new grants awarded to improve initiatives focused on optimizing biomarker-directed therapy in metastatic colorectal cancer.
Table of contents
15 chapters · 133 sections · 350 pages · click to expandSegmental analysis
| Segment | Largest share (2025) | Fastest growth (2025–2032) |
|---|---|---|
| By Biomarker Type | Safety Biomarkers | Efficacy biomarkers |
| By Offering | Consumables | — |
| By Mechanism | Epigenetic Biomarkers | — |
| By Profiling Technology | Immunoassay | — |
| By Disease Type | Oncology | — |
| By Application | Drug Discovery & Development | Diagnostics |
| By End User | Pharmaceutical & Biotechnology Companies | — |
By Biomarker Type
- The safety biomarkers segment is expected to account for the largest share of 42.4% of the biomarkers market.
- Safety biomarkers are used to assess the safety or potential risks after and before exposure to a medical product or environmental agent.
- The large share of the segment is attributed to the increase in drug discovery research and availability of funding.
- The key pharmaceutical manufacturers heavily invest in R&D.
- The companies like Roche (Switzerland), Novartis AG (Switzerland), Abbott (U.S.), and Merck (U.S.) are investing 15%-30% of their revenue annually dedicated to R&D.
- Thus, high spending on drug discovery is accelerating the demand for safety biomarkers.
- However, the efficacy biomarkers segment is projected to witness the highest growth rate of 15.8% during the forecast period of 2025–2032.
- Efficacy biomarkers are used to assess the effectiveness or therapeutic response of a drug.
- These biomarkers help determine whether a treatment is producing desired effects or not.
- Growing number of clinical trials globally is driving the market growth.
- For instance, as per WHO data published in February 2024, the number of clinical trials in 2022 has reached 744,100 compared to 487,002 in 2019.
- Thus, the rise in the number of candidates in phases III and IV of clinical trials is driving market growth.
By Offering
- The Consumables Segment to Dominate the Biomarkers Market
- The consumables segment is expected to account for the largest share of the biomarkers market.
- The continuous advancements in terms of the development of reagents and kits, high adoption and recurring consumption of biomarker identification and testing kits, and wide availability of consumables support the largest share of the market.
- The adoption of biomarker kits in clinical diagnostics is high due to rising disease prevalence, thereby supporting the segment’s largest share.
By Mechanism
- The epigenetic biomarkers segment is expected to account for the largest share of the biomarkers market.
- Epigenetic biomarkers are used to assess biological processes such as disease development, progression, and response to the treatment.
- The rise in the prevalence of infectious and non-infectious diseases, coupled with the rising need to bring novel therapies to the market, is generating demand for epigenetic markets.
- The key players are also collaborating with other industry players to boost research in epigenetic markers.
- For instance, in November 2024, Bayer AG partnered with Hurdle (U.K.) to advance precision health and increase patients' access to novel epigenetic and multi-omics for at-home biomarker tests.
By Profiling Technology
- The Immunoassay Segment to Dominate the Biomarkers Market
- The immunoassay segment is expected to account for the largest share of the biomarkers market.
- Immunoassays are bioanalytical techniques that use the specificity of an antigen-antibody reaction to detect and quantify target molecules in biological samples.
- The wide utilization of immunoassays in clinical diagnostics, drug discovery, and drug monitoring for biomarker detection contributes to the largest share of the market.
- Immunoassays are fast, simple, and a cost-effective technique, with better sensitivity and specificity comparable to or better than the conventional methods, owing to which their adoption is the highest.
By Disease Type
- The Oncology Segment to Dominate the Biomarkers Market
- The oncology segment is expected to account for the largest share of the biomarkers market.
- In cancer research, biomarkers are used for wide applications such as early detection, diagnosis, prognosis, and treatment.
- Cancer (malignant tumor) is a major health concern globally and is one of the leading causes of morbidity and mortality across the world.
- According to GLOBOCAN, the number of all cancer types diagnosed in 2020 was 19.29 million, and it is expected to reach 24.59 million by 2032.
- The evolving landscape of biomarker research in cancer and the availability of funding to support cancer research are supporting the segment’s largest share.
By Application
- The drug discovery & development segment is expected to account for the largest share of 33% of the biomarkers market.
- The largest share of the segment is attributed to the wide applications of biomarkers in research & development, focus on developing precision therapeutics, and high growth in the cancer biomarker research supports the largest share of the market.
- The rising funding for drug discovery and the increasing need for developing novel therapies are supporting the largest share of the segment.
- For instance, in June 2024, the Commonwealth Government’s Medical Research Future Fund (MRFF) (Australia) invested USD 9.75 million in establishing MedChem Australia, a new national medicinal chemistry initiative, to accelerate the identification of early-stage drug candidates in clinical studies.
- However, the diagnostics segment is projected to witness the highest growth rate of 16.0% during the forecast period of 2025–2032.
- The high growth of the segment is attributed to the increasing use of biomarkers in disease risk assessment, staging to categorize disease severity, treatment selection, and patient monitoring.
- The rising prevalence of infectious and non-infectious diseases, coupled with the availability of funding for clinical diagnostics, are supporting the segment’s high growth.
- For instance, in April 2025, the U.S. National Science Foundation awarded a USD 275,000 Phase 1 Small Business Innovation Research (SBIR) grant to Amplified Sciences, a clinical-stage life sciences diagnostic company based in the U.S. The company is developing tests for early, more accurate detection of challenging diseases such as pancreatic cancer.
By End User
- The pharmaceutical & biotechnology companies segment is expected to account for the largest share of the biomarkers market.
- The largest share of the segment is attributed to high spending on R&D by pharmaceutical companies, a focus on developing novel therapies, and a growing focus on personalized medicines.
- Pharmaceutical and biotechnology companies allocate significant resources to their research activities.
- The rising spending on R&D by pharmaceutical companies is contributing to the largest share of the market.
- For instance, in 2021, Pharmaceutical Research and Manufacturers of America (PhRMA) member companies spent USD 102.3 billion in R&D, compared to USD 91.1 Billion in 2020 (Source: 2022 PhRMA member annual survey).
Geographic analysis
North America
Largest shareIn 2025, North America is expected to account for the largest share of the 49.2% of the biomarkers market. The large share of the region is attributed to the substantial R&D investments by pharmaceutical companies for drug discovery & development, the presence of key market players in the region, government initiatives supporting research and development, and the high adoption of advanced diagnostic products. The regional government is focusing on biomarker research, further supporting the largest share in the region. For instance, in June 2024, the FDA launched a voluntary pilot program using cancer biomarkers for certain oncology drug products with certain corresponding in-vitro diagnostic tests. The program aims to help clinicians select suitable cancer treatments for patients.
Asia-Pacific
Fastest growthMoreover, the market in Asia-Pacific is slated to register the highest growth rate of 17.2% during the forecast period. The countries in Asia-Pacific, including China, India, and South Korea, are projected to offer significant growth opportunities for the vendors in this market. The growing prevalence of diseases due to the growing geriatric population, increasing funding for drug discovery, and rising research initiatives for biomarkers in the country are driving the market growth. For instance, in October 2024, the Indian Institute of Technology (IIT), Madras, India, established a Centre of Excellence for research purposes to develop biomarkers for early detection of pancreatic cancer. Similarly, in May 2024, Fujitsu Limited (Japan), Kyoto University (Japan), and Chordia Therapeutics, Inc. (Japan) launched AI trials to discover biomarkers for new cancer drugs.
Competitive landscape
- March 2025
Labcorp (U.S.) launched a pTau217 blood biomarker test. The test helps diagnose Alzheimer's disease and monitor patients undergoing treatment with new therapies.
- January 2025
Merck KGaA (Germany) partnered with Quibim (Spain) to develop precision medicine technology for the treatment of a wide range of cancers. Both companies are using radiomics and biomarkers to predict a cancer patient’s response to immunotherapy.
- October 2024
Mindray (China) launched a high-sensitivity troponin I (hs-cTnI) and NT-proBNP cardiac biomarker assay for the diagnosis of cardiovascular diseases. The launch enhances Mindray’s diverse portfolio of cardiac biomarkers.
- July 2024
Quanterix Corp. (U.S.) launched a LucentAD biomarker blood test. The test evaluates patients experiencing cognitive symptoms consistent with the early signs of Alzheimer’s disease (AD).
- June 2024
Sysmex Corporation (Japan) launched a HISCL β-Amyloid 1-42 Assay Kit and the HISCL β-Amyloid 1-40 assay kit for the diagnosis of Alzheimer’s Disease. The product helps in detecting the level of accumulation of Aβ in the brain by measuring the ratio of Aβ peptides, which are blood biomarkers approved as in vitro diagnostics.
- F. Hoffmann-La Roche AG · Switzerland
- Merck KGaA · Germany
- Epigenomics AG · Germany
- Abbott Laboratories (U.S.)
- QIAGEN N.V. · Germany
- Bio-Rad Laboratories (U.S.)
- Revvity Inc. (U.S.)
- Siemens Healthineers AG · Germany
- Mindray · China
- Thermo Fisher Scientific Inc. (U.S.)
- Eurofins Scientific SE · France
- Agilent Technologies, Inc. (U.S.)
- Quanterix Corp. (U.S.)
Frequently asked questions
The Biomarkers Market focuses on identifying biological markers for disease detection, diagnosis, drug development, and personalized medicine approaches.
Cite this report
Meticulous Research. (2024). Biomarkers Market - Global Opportunity Analysis And Industry Forecast (2025-2032) (Report No. MRHC - 1041186). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/biomarkers-market-5869