Modular Data Center Market (2025-2032)
The Modular Data Center Market is expected to reach $90.3 billion by 2032, at a CAGR of 17.9% from 2025 to 2032.
- Published
- May 2024
- Pages
- 250
- Format
- PDF + Excel
- Report ID
- MR-1192
- Base year
- 2024
- 2032 · FORECAST
- $90.30B
- 2032
- $90.30B
- CAGR 2025–2032
- 17.9%
2024 baseline · 2025–2032 forecast at 17.9% CAGR · hover a bar for the value
Key highlights
By Offering: In 2025, the Solutions Segment to Dominate the Modular Data Center Market
By Organization Size: In 2025, the Small and Medium-sized Enterprises (SME) Segment to Dominate the Modular Data Center Market
By End User: In 2025, the IT & Telecom Segment to Dominate the Modular Data Center Market
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 250 |
| Format | |
| Forecast Period | 2025–2032 |
| Base Year | 2024 |
| CAGR (Value) | 17.9% |
| Market Size (Value) | USD 90.3 Billion by 2032 |
| Segments Covered | By Offering · Solutions · All-in-one Modules · Individual Modules · IT Modules · Power Modules · Cooling Modules · Services · Design & Consultancy Services · Integration & Deployment Services · Support & Maintenance Services · By Organization Size · Large Enterprises · Small and Medium-sized Enterprises (SME's) · By End User · BFSI · IT & Telecom · Government · Media & Entertainment · Healthcare · Retail · Education Institute's · Manufacturing · Other End Users |
| Countries Covered | Europe (U.K., Germany, France, Italy, Spain, Sweden, Switzerland, Netherlands, Norway, Austria, Denmark, Rest of Europe), Asia-Pacific (China, Japan, India, South Korea, Singapore, Australia, Malaysia, Rest of Asia-Pacific), North America (U.S., Canada), Latin America (Brazil, Mexico, Rest of Latin America), and the Middle East & Africa (Israel, UAE, Rest of Middle East & Africa) |
| Key Companies | Dell Technologies Inc. (U.S.), Schneider Electric SE (France), IBM Corporation (U.S.), Vertiv Group Corporation (U.S.), Huawei Technologies Co., Ltd. (China), Rittal GmbH & Co. KG (Germany), Eaton Corporation plc (Ireland), Hewlett Packard Enterprise Company (U.S.), Silent-Aire (Canada), PCX Holding LLC (U.S.), Cannon Technologies Ltd (U.K.), BladeRoom Group Limited (U.K.), Baselayer Technology, LLC (U.S.), Yondr Group (Netherlands), and Altron a.s. (Czech Republic). |
Report overview
Segments covered: offering, organization size. Regions: Europe, Asia-Pacific, North America, Latin America, Middle East & Africa.
The growth of the modular data center market is driven by increasing demand for massive data processing and computing power and increasing use of edge computing. However, data privacy & security concerns are a factor restraining the growth of this market.
Furthermore, the rapid growth in artificial intelligence applications and the increased adoption of micro data centers are expected to generate growth opportunities for the stakeholders in this market. However, integration with existing infrastructure is a major challenge impacting market growth. Additionally, the increasing use of green energy sources for powering modular data centers, hybrid cloud adoption, and integration of advanced cooling systems in modular data centers are prominent trends in the modular data center market.
Market dynamics
5 factors across 3 forcesIncreasing Demand for Massive Data Processing and Computing Power Boosting Market Growth
Agility has become vital for companies to accelerate innovation and future-proof their businesses. Recently, the volume of data generated has reached unprecedented levels, primarily due to the proliferation of IoT devices, big data applications, and digitization. This development is creating flexibility and extendibility challenges for traditional data centers due to their solid state. Traditional data center takes a long duration for planning, design, and installation of the systems in the data center and its operation. However, the modular data center requires a shorter planning and designing period. Modular data centers enable high expandability and easy deployment and provide multiple construction phases depending on the requirements. Hence, ongoing technological advancements are creating demand for data processing and computing power, which is expected to drive the adoption of modular data centers.
Increasing Use of Edge Computing is Driving the Demand for Modular Data Center Market
The growing use of edge computing is one of the most significant trends in data centers. Computing at the edge brings computational capacity and storage closer to the source of data generation. One key factor driving the momentum toward Edge computing is the surge in IoT devices and the need for real-time processing. Healthcare, energy, agriculture, and telecommunications are other sectors significantly benefiting from edge computing’s capabilities.
Modular data centers play a central role in empowering edge computing and meet the growing demand for greater data center capacity. In addition, several key players are focusing on the development of modular data centers to increase the use of edge computing. For instance, in March 2025, Eaton Corporation plc (Ireland) launched a new modular data center solution for organizations seeking to rapidly meet the growing requirements for edge computing, machine learning, and AI. These evolving needs of modern businesses are driving the demand for compact, modular data center units designed to meet specific site requirements.
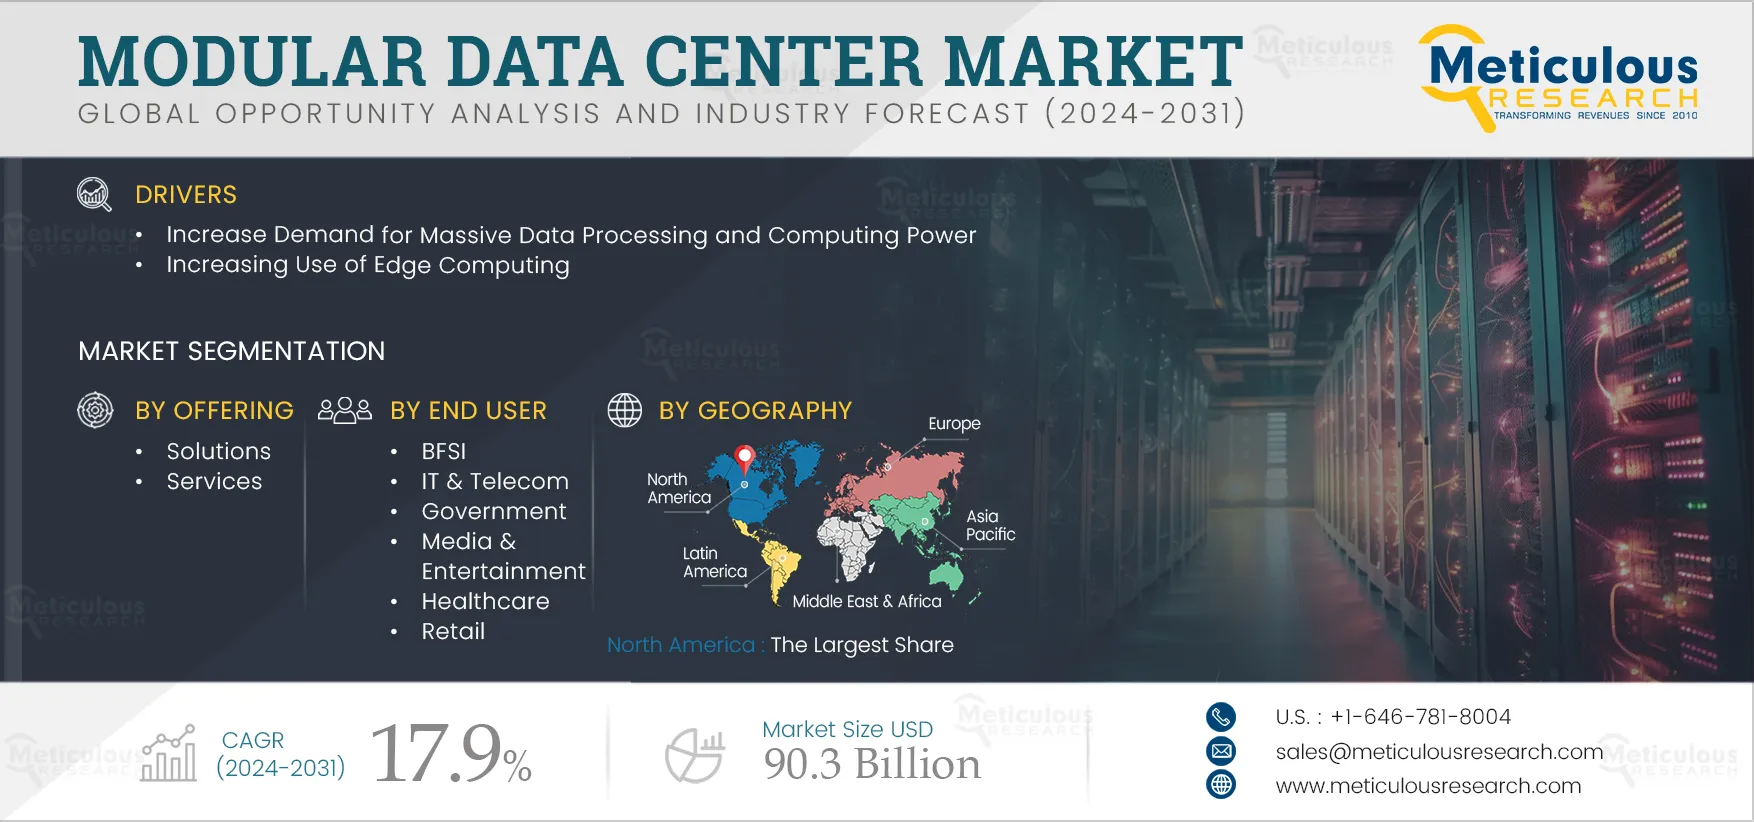
Table of contents
11 chapters · 128 sections · 250 pages · click to expandSegmental analysis
| Segment | Largest share (2025) | Fastest growth (2025–2032) |
|---|---|---|
| By Offering | Solutions | Services |
| By Organization Size | Small and Medium-sized Enterprises (SME) | Small and medium-sized enterprises (SMEs) |
| By End User | — | Healthcare |
By Offering
- The Solutions Segment to Dominate the Modular Data Center Market
- The solutions segment is expected to account for the larger share of above 70.0% of the modular data center market.
- The solutions segment is further segmented into all-in-one modules and individual modules.
- The segment’s large market share is mainly attributed to factors such as the excellent performance of modular data centers in energy consumption, advantages of modular data centers in the construction, planning, and required space, increasing data consumption, and digital transformation.
- However, the services segment is expected to record the highest CAGR during the forecast period.
- This segment's growth is mainly driven by the increasing demand for modular data centers for processing data generated by IoT devices and AI applications, the growing need for integrating and deploying modular data centers in traditional data centers to enhance operations scalability, and businesses' growing concern to streamline and enhance data center performance.
By Organization Size
- The small and medium-sized enterprises (SMEs) segment is expected to account for the larger share of above 55.0% of the modular data center market.
- The segment’s large share is mainly attributed to factors such as increased adoption of scalable IT infrastructure to facilitate growth, manage costs, and swiftly adapt to growing market needs; increased operational integration of AI and ML in SMEs; and lower upfront investment.
- Moreover, the small and medium-sized enterprises (SMEs) segment is expected to record the highest CAGR during the forecast period.
- This segment's growth is mainly driven by the rising demand for real-time data processing and localized data management and the increasing need to leverage localized computing resources without significant infrastructure investments.
By End User
- The IT & Telecom Segment to Dominate the Modular Data Center Market
- The IT & telecom segment is expected to account for the largest share of above 30.0% of the modular data center market.
- The segment’s large share is mainly attributed to factors such as increased use of edge computing and AI applications in the IT & telecom sector, growing data loads in the telecom sector, increased reliance on data, the crucial need for data storage for business operations, and increasing investment of companies on IT infrastructure.
- Moreover, the healthcare segment is expected to record the highest CAGR during the forecast period.
- This segment's growth is mainly driven by the growing digitalization of the healthcare sector, the increased need to store electronic health records (EHR), medical imagery, and patient information, the increasing spending of the healthcare sector on IT infrastructure to optimize functioning, and the growing use of medical IoT devices for collecting and analyzing patient information.
Geographic analysis
North America
Largest shareIn 2025, North America is expected to account for the largest share of above 35.0% of the modular data center market. The large market share of this segment is attributed to the increased adoption of modular data centers in the region’s IT & telecom industry, the presence of leading IT companies, the rising need for efficient data collection and management in the region, data storage compliance and regulations, and increased adoption of edge computing in the region. In 2025, North America to Dominate the Modular Data Center Market
Asia-Pacific
Fastest growthHowever, Asia-Pacific is projected to register the highest CAGR of 20.0% during the forecast period. This region's growth is due to increasing digitalization, government initiatives promoting digitalization across various industries, substantial investments in IoT and AI technologies, and government and private enterprise investments in IT infrastructure.
Competitive landscape
- April 2025
Vertiv Group Corporation (U.S.) launched the Vertiv SmartAisle 3, a micro modular data center system that utilizes the power of Artificial Intelligence (AI), providing enhanced intelligence and enabling efficient operations within the data center environment.
- November 2024
Schneider Electric SE (France) expanded its partnership with Compass Datacenters (U.S.). The partnership extends the companies’ existing relationship that integrates their respective supply chains to manufacture and deliver prefabricated modular data center solutions.
- November 2024
Vertiv Group Corporation (U.S.) launched the innovative Vertiv TimberMod variant of its Vertiv Power Module and Vertiv SmartMo™ families. This variant features mass timber as a key structural component instead of steel for prefabricated modular (PFM) data center solutions.
- Dell Technologies Inc. (U.S.)
- Schneider Electric SE · France
- IBM Corporation (U.S.)
- Vertiv Group Corporation (U.S.)
- Huawei Technologies Co., Ltd. · China
- Rittal GmbH & Co. KG · Germany
- Eaton Corporation plc · Ireland
- Hewlett Packard Enterprise Company (U.S.)
- Silent-Aire · Canada
- PCX Holding LLC (U.S.)
- Cannon Technologies Ltd (U.K.)
- BladeRoom Group Limited (U.K.)
- Baselayer Technology, LLC (U.S.)
- Yondr Group · Netherlands
- Altron a.s · Czech Republic
Frequently asked questions
The Modular Data Center Market consists of prefabricated, scalable data centers designed for rapid deployment and flexibility in data processing and computing.
Cite this report
Meticulous Research. (2024). Modular Data Center Market - Global Opportunity Analysis and Industry Forecast (2025-2032) (Report No. MR-1192). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/modular-data-center-market-5875