Green Data Center Market (2025-2032)
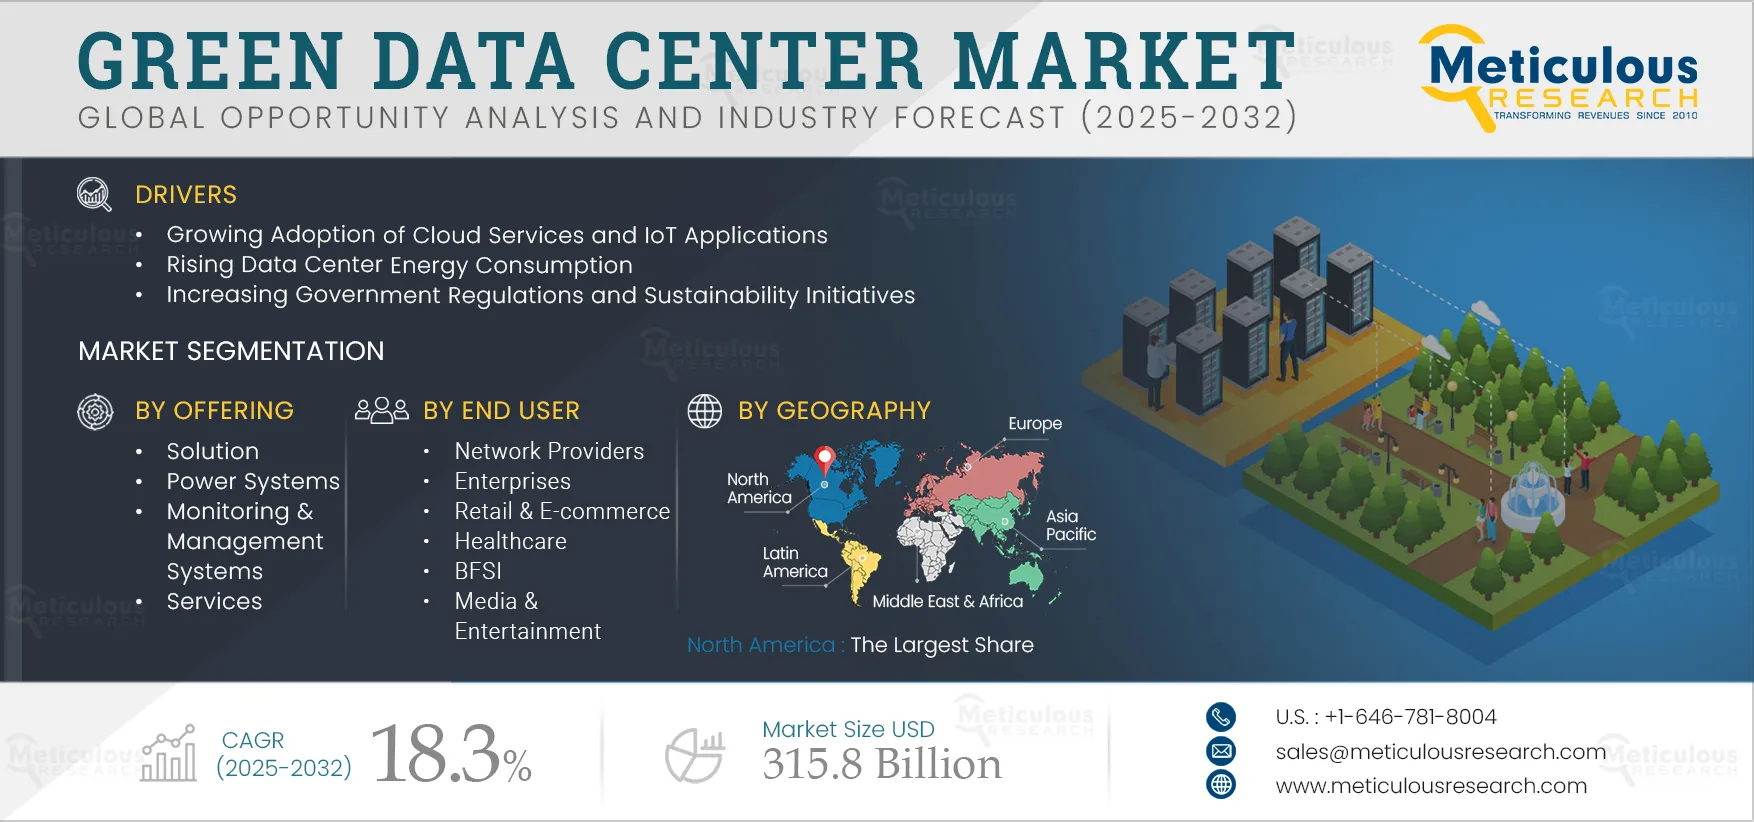
The green data center market was valued at $83.6 billion in 2024. This market is expected to reach $315.8 billion by 2032 from an estimated $97.6 billion in 2025, at a CAGR of 18.3% during the forecast period of 2025-2032. Green Data Center Market Size & Forecast The growth of this market can be attributed
- Published
- Oct 2024
- Pages
- 240
- Format
- PDF + Excel
- Report ID
- MRICT - 1041367
- Base year
- 2024
- 2024 · BASELINE
- $83.60B
- 2032
- $315.8B
- CAGR 2025–2032
- 18.3%
2024 baseline · 2025–2032 forecast at 18.3% CAGR · hover a bar for the value
Key highlights
By Offering: The Solution Segment is Expected to Dominate the Green Data Center Market in 2025
By Deployment Mode: the Cloud-based Deployments Segment is Expected to Dominate the Green Data Center Market in 2025
By Data Center Size: the Hyperscale Data Centers Segment is Expected to Dominate the Green Data Center Market in 2025
By End User: the Cloud Service Providers (CSPs) Segment is Expected to Dominate the Green Data Center Market in 2025
By Geography: North America to Dominate the Green Data Center Market in 2025
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 240 |
| Format | |
| Forecast Period | 2025–2032 |
| Base Year | 2024 |
| CAGR (Value) | 18.3% |
| Market Size (Value) | USD 315.8 Billion by 2032 |
| Segments Covered | By Offering · Solution · Power Systems · Monitoring & Management Systems · Cooling/HVAC Systems · Networking Systems · Server & Storage Systems · Services · Training & Support · Installation & Deployment · Maintenance & Support · By Deployment Mode · On-premise Deployments · Cloud-based Deployments · By Data Center Size · Small & Medium Data Centers · Large Data Centers · Hyperscale Data Centers · By End User · Network Providers · Cloud Service Providers (CSPs) · Enterprises · Retail & E-commerce · Healthcare · IT & Telecommunications · BFSI · Media & Entertainment · Other Enterprises · (Note: Other enterprises include the Government & Public Sector, Education, Agriculture & Food Industry, and Manufacturing.) |
| Countries Covered | Europe (Germany, U.K., Italy, France, Spain, Russia, Netherlands, and Rest of Europe), Asia-Pacific (Japan, China, India, South Korea, Thailand, Singapore, and Rest of Asia-Pacific), North America (U.S., Canada), Latin America (Brazil, Argentina, Mexico, and Rest of Latin America), and the Middle East & Africa (UAE, Saudi Arabia, South Africa, and Rest of the Middle East & Africa) |
| Key Companies | Dell Technologies Inc. (U.S.), Fujitsu Limited (Japan), Cisco Systems, Inc. (U.S.), Hewlett Packard Enterprise Company (U.S.), Hitachi Energy Ltd (Switzerland) (a subsidiary of Hitachi, Ltd. (Japan)), Schneider Electric SE (France), IBM Corporation (U.S.), Eaton Corporation plc (Ireland), Vertiv Group Corporation (U.S.), Green Revolution Cooling, Inc. (U.S.), ABB Ltd (Switzerland), GE Vernova Inc. (U.S.), Delta Electronics, Inc. (Taiwan), Digital Realty Trust Inc. (U.S.), Equinix, Inc. (U.S.), Huawei Technologies Co., Ltd. (China), Ark Data Centres Limited (U.K.), and Iron Mountain, Inc. (U.S.) |
Report overview
Segments covered: offering, deployment, data center size. Regions: Europe, Asia-Pacific, North America, Latin America, Middle East & Africa.
The growth of this market can be attributed to several factors, including the growing adoption of cloud services and IoT applications, rising data center energy consumption, and increasing government regulations and sustainability initiatives. Additionally, the increasing availability and affordability of renewable energy sources and the expansion of edge computing infrastructure is expected to create market growth opportunities. However, high initial capital investment may restrain the growth of this market. However, the implementation of energy-efficient cooling systems is a major challenge for the players operating in this market.
Additionally, the growing adoption of liquid cooling technologies and AI-powered energy management systems is a key trend in the Green Data Center market.
Report infographic
Market dynamics
5 factors across 3 forcesIncreasing Government Regulations and Sustainability Initiatives
As the world confronts the urgent need to reduce carbon emissions, organizations are facing increasing pressure to comply with stringent regulations. Governments worldwide, particularly in countries like Germany, the U.K., and the U.S., are setting ambitious targets for achieving carbon neutrality. For example, the U.K. has established a bold goal of reducing greenhouse gas emissions by 100% by 2050. To support this target, the U.K. government has implemented a range of policies outlined in two key publications: the Net Zero Strategy (2021) and Powering Up Britain: The Net Zero Growth Plan (2024). These policies compel organizations to take swift, decisive action to align their operations with environmental standards.
Many companies in this sector are now focused on developing innovative solutions to enhance energy efficiency, increase capacity, and reduce latency in data centers, contributing to the goal of a carbon-neutral society. This includes leveraging renewable energy sources such as wind and solar power, adopting advanced cooling technologies like liquid cooling, and utilizing modular infrastructure designs that support scalable and sustainable growth. These factors, combined with the rising sustainability initiatives and cross-sector collaboration to address the growing power consumption of data centers, are driving market growth.
Growing Adoption of Cloud Services and IoT Applications
Many organizations are increasingly migrating to cloud-based platforms, driving the demand for scalable and energy-efficient data infrastructure to manage fluctuating workloads. Cloud computing technology often utilizes densely packed server configurations optimized for large-scale data processing and storage, resulting in higher power densities and significant heat generation. To tackle these challenges, data center operators are adopting sustainable solutions, including advanced power systems, monitoring and management systems, networking systems, and cooling/HVAC systems.
For example, liquid cooling systems offer modular solutions that can be easily expanded or reconfigured to meet changing requirements, allowing cloud providers to optimize performance while reducing energy consumption. Additionally, IoT applications generate vast amounts of data from interconnected devices, necessitating data centers capable of efficiently processing and storing this information. Green data centers address these demands with energy-efficient technologies that minimize carbon footprints while ensuring secure and reliable operations. The integration of renewable energy sources such as solar, geothermal, hydroelectric, and wind power further enhances the sustainability of these facilities. Together, these factors, along with the rising energy consumption in data centers, are expected to accelerate the demand for green data centers in the coming years.
Table of contents
12 chapters · 130 sections · 240 pages · click to expandSegmental analysis
| Segment | Largest share (2025) | Fastest growth (2025–2032) |
|---|---|---|
| By Offering | Solution | Services |
By Offering
- The Solution Segment is Expected to Dominate the Green Data Center Market in 2025
- The solution segment is further segmented into power systems, monitoring & management systems, cooling/HVAC systems, networking systems, and server & storage systems.
- The serviced segment is further segmented into training & support, installation & deployment, and maintenance & support.
- The solution segment is estimated to account for the largest share of the green data center market.
- The substantial share of this segment is attributed to the growth of cloud computing and AI technologies, the rising demand for energy-efficient power systems to reduce operational costs, and the increasing need for scalable infrastructure.
- Additionally, the adoption of eco-friendly cooling and HVAC systems to comply with environmental regulations and the growing requirement for advanced real-time monitoring tools to optimize energy use and performance in data centers are significant factors driving this segment's expansion.
- However, the services segment is slated to register the highest CAGR during the forecast period.
- The growth of the services segment in the coming year is supported by the increasing complexity of data center systems, the need to ensure optimal performance and energy efficiency in green data centers, and the rising demand for installation and deployment services to ensure compliance with sustainability standards.
- Additionally, the growing need for maintenance and support services to keep data centers operational and energy-efficient further contributes to this segment's growth.
Geographic analysis
North America
Largest shareIn 2025, North America is estimated to account for the largest share of the global green data center market. Stringent government carbon emission regulations and sustainability mandates, high energy costs in the region, and the rapid expansion of cloud computing and AI-based services primarily drive this substantial share. Additionally, increasing investments in eco-friendly data center solutions, the integration of renewable energy into data centers, and growing government incentives for green infrastructure further contribute to this segment's dominance. North America Dominates the Green Data Center Market in 2025
Asia-Pacific
Fastest growthHowever, Asia-Pacific is slated to register the highest CAGR during the forecast period. The region is rapidly advancing in green initiatives and renewable energy, driven by rising investments from tech companies and government efforts focused on energy efficiency. Market growth is fueled by several factors, including increased investments in data center expansion, the need to lower operating costs through energy-efficient systems, greater availability of renewable energy sources, and the swift pace of digital transformation. Furthermore, government initiatives in countries such as China, Japan, Australia, and India aimed at reducing carbon emissions and promoting renewable energy adoption in data centers are significant contributors to this growth.
Competitive landscape
- August 2025
Singtel Group (Singapore) and Hitachi, Ltd. signed a Memorandum of Understanding (MOU) to collaborate on next-generation data centers and GPU Cloud in Japan, with potential expansion into the broader Asia Pacific region. This strategic partnership aims to leverage Singtel's extensive expertise in data centers and connectivity alongside Hitachi's unique capabilities for end-to-end data center integration, which includes green power solutions, cooling systems, storage infrastructure, and data management.
- November 2024
, Vertiv Group Corporation (U.S.) launched the Vertiv™ TimberMod variant of its Vertiv™ Power Module and SmartMod™ families. This variant features mass timber as a key structural component instead of steel for prefabricated modular (PFM) data center solutions. Vertiv™ TimberMod helps support customers' sustainability objectives by using a more environmentally friendly material that can minimize resource depletion and lower CO2 emissions.
- October 2024
Green Revolution Cooling, Inc. (U.S.), DCV Industries (UAE), and Dell Technologies Inc. (U.S.) partnered to deliver advanced immersion-cooled modular data centers to the Middle East region. This collaboration seeks to provide organizations with a comprehensive solution that significantly lowers data center construction, maintenance, and power costs compared to traditional air-cooled facilities.
- October 2024
ThermalWorks (U.S.) launched its waterless cooling system built for the fast-changing data center industry. It is designed to handle the ever-increasing density loads required by artificial intelligence and high-performance GPU-based computing. The system supports densities of up to 70 kW per rack with air cooling and up to 200 kW per rack with plug-and-play liquid cooling integration.
- May 2024
Sonic Edge (U.K.) partnered with Deep Green Technologies Limited (U.K.) to lower customers' power costs through immersion cooling technologies. This collaboration will support Sonic Edge in launching 50 new HPC/EdgePods across the U.K. by 2025.
- Dell Technologies Inc. (U.S.)
- Fujitsu Limited · Japan
- Cisco Systems, Inc. (U.S.)
- Hewlett Packard Enterprise Company (U.S.)
- Schneider Electric SE · France
- IBM Corporation (U.S.)
- Eaton Corporation plc · Ireland
- Vertiv Group Corporation (U.S.)
- Green Revolution Cooling, Inc. (U.S.)
- ABB Ltd · Switzerland
- GE Vernova Inc. (U.S.)
- Delta Electronics, Inc. · Taiwan
- Digital Realty Trust Inc. (U.S.)
- Equinix, Inc. (U.S.)
- Huawei Technologies Co., Ltd. · China
- Ark Data Centres Limited (U.K.)
- Iron Mountain, Inc. (U.S.)
Frequently asked questions
The global green data center market size was valued at $83.6 billion in 2024.
Cite this report
Meticulous Research. (2024). Green Data Center Market - Global Opportunity Analysis and Industry Forecast (2025-2032) (Report No. MRICT - 1041367). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/green-data-center-market-6050