Liquid Cooling Data Center Market (2025-2032)
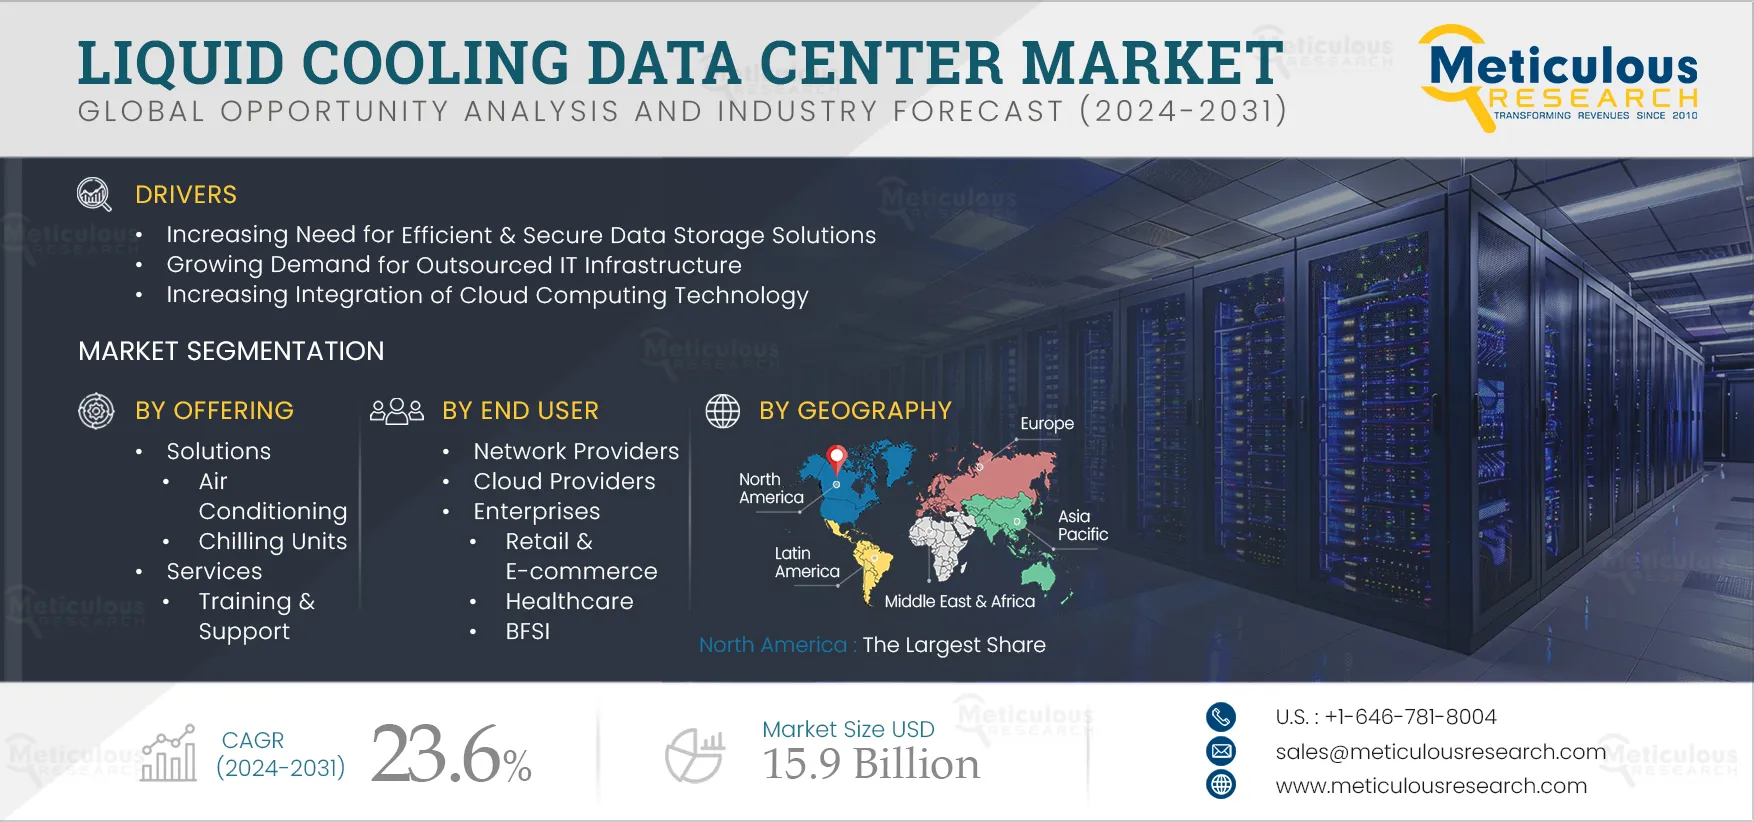
The Liquid Cooling Data Center Market is expected to reach $15.9 Billion by 2032, at a CAGR of 23.6% from 2025 to 2032.
- Published
- Jun 2024
- Pages
- 250
- Format
- PDF + Excel
- Report ID
- MRICT - 1041234
- Base year
- 2024
- 2032 · FORECAST
- $15.90B
- 2032
- $15.90B
- CAGR 2025–2032
- 23.6%
2024 baseline · 2025–2032 forecast at 23.6% CAGR · hover a bar for the value
Key highlights
By Offering: In 2025, the Solutions Segment to Dominate the Liquid Cooling Data Center Market
By Cooling Method: In 2025, the Immersion Cooling Segment to Dominate the Liquid Cooling Data Center Market
By Data Center Size: In 2025, the Medium-scale Data Centers Segment to Dominate the Liquid Cooling Data Center Market
By End User: In 2025, the Enterprises Segment to Dominate the Liquid Cooling Data Center Market
In 2025, North America to Dominate the Liquid Cooling Data Center Market
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 250 |
| Format | |
| Forecast Period | 2025–2032 |
| Base Year | 2024 |
| CAGR | 23.6% |
| Market Size | USD 15.9 Billion by 2032 |
| Segments Covered | By Offering · Solutions · Air Conditioning · Chilling Units · Cooling Towers · Economizer Systems · Liquid Cooling Systems · Control Systems · Others Solutions · Services · Training & Support · Installation & Deployment · Maintainance & Support · By Cooling Method · Direct-to-chip Liquid Cooling · Rack-level Liquid Cooling · Immersion Cooling · Rear-door Heat Exchange · Modular Liquid Cooling · Other Cooling Methods · By Data Center Size · Small-scale Data Centers · Medium-scale Data Centers · Hyperscale Data Centers · By End User · Network Providers · Cloud Providers · Enterprises · Retail & E-commerce · Healthcare · IT & Telecommunications · BFSI · Media & Entertainment · Other Enterprises |
| Countries Covered | Europe (Germany, U.K., France, Italy, Spain, Netherlands, Switzerland, Sweden, Denmark, and Rest of Europe), Asia-Pacific (China, Japan, India, South Korea, Australia & New Zealand, Indonesia, Thailand, Vietnam, Malaysia, Singapore, and Rest of Asia- Pacific), North America (U.S., Canada), Latin America (Brazil, Mexico, and Rest of Latin America), and the Middle East & Africa (UAE, Israel, and Rest of Middle East & Africa) |
| Key Companies | Alfa Laval AB (Sweden), Asperitas (Netherlands), Chilldyne, Inc. (U.S.), OptiCool Technologies (U.S.), Iceotope Technologies Limited (U.K.), Fujitsu Limited (Japan), LiquidStack Holding B.V. (U.S.), Motivair Corporation (U.S.), Schneider Electric SE (France), Submer Technologies SL (Spain), Wiwynn Corporation (Taiwan), RITTAL GmbH & Co. KG (Germany), Asetek A/S (Denmark), ZutaCore, Inc. (U.S.), and Parker-Hannifin Corporation (U.S.) |
Report overview
Segments covered: offering, cooling method, data center size, end user. Regions: Europe, Asia-Pacific, North America, Latin America, Middle East & Africa.
The growth of the liquid cooling data center market is driven by the Increasing need for efficient & secure data storage solutions, growing demand for outsourced IT infrastructure, and increasing integration of cloud computing technology. Furthermore, rising demand for green data center initiatives and rapid advancement of emerging technologies are expected to offer significant growth opportunities for players operating in the liquid cooling data center market.
Report infographic
Market dynamics
4 factors across 3 forcesGrowing Demand for Outsourced IT Infrastructure
The growing demand for outsourced IT infrastructure drives the demand for the liquid cooling data center market, as outsourced IT infrastructure providers offer scalable and flexible solutions that can adapt to the evolving needs of businesses. Liquid cooling data centers provide the scalability and flexibility required to support varying levels of demand, allowing providers to efficiently expand or contract their infrastructure in response to changing customer requirements. Liquid cooling data centers offer higher energy efficiency compared to traditional air-cooled data centers, resulting in lower operating costs and reduced environmental impact.
Outsourced IT infrastructure providers can leverage liquid cooling technologies to minimize energy consumption and deliver cost-effective services to their customers, thereby enhancing their competitiveness in the market. Additionally, outsourced IT infrastructure providers must ensure high levels of reliability and performance to meet service level agreements (SLAs) and customer expectations. Liquid cooling data centers contribute to improved reliability and performance by maintaining consistent operating temperatures and preventing thermal-related failures, resulting in higher uptime and customer satisfaction. Such factors help to drive the growth of the market.
Increasing Integration of Cloud Computing Technology
Cloud computing platforms require infrastructure that can scale rapidly and adapt to fluctuating workloads and customer demands. Liquid cooling data centers offer scalability and agility by providing modular cooling solutions that can be easily expanded or reconfigured to accommodate changing requirements. This flexibility allows cloud providers to respond quickly to shifting market dynamics and customer needs without compromising performance or efficiency. Cloud computing environments often involve densely packed server configurations to maximize resource utilization and meet the demands of large-scale data processing and storage. This results in higher power densities and increased heat generation, making efficient cooling solutions essential. Liquid cooling data centers excel at dissipating heat from high-density server deployments, enabling cloud providers to optimize performance and reliability while maintaining energy efficiency. Such factors help to drive the growth of the market.
Table of contents
12 chapters · 138 sections · 250 pages · click to expandSegmental analysis
| Segment | Largest share (2025) | Fastest growth (2025–2032) |
|---|---|---|
| By Offering | Solutions | Services |
| By Cooling Method | Immersion Cooling | Immersion cooling |
| By Data Center Size | Medium-scale Data Centers | Medium-scale data center |
| By End User | Enterprises | Enterprises |
By Offering
- The Solutions Segment to Dominate the Liquid Cooling Data Center Market
- Further, the solutions segment is segmented into air conditioning, chilling units, cooling towers, economizer systems, liquid cooling systems, control systems, and other solutions.
- The services segment is segmented into training & support, installation & deployment, and maintenance & support.
- The solutions segment is expected to account for the larger share of above 72.0% of the liquid cooling data center market.
- The growth of this segment is attributed to the various factors as liquid cooling can significantly improve energy efficiency in data centers by reducing the need for mechanical cooling systems.
- As energy costs continue to rise and environmental concerns grow, businesses are increasingly adopting liquid cooling to meet sustainability goals and reduce operating expenses.
- Such factors help to drive the market.
- However, the services segment is projected to register the highest CAGR during the forecast period.
- The growth of this segment can be attributed to various factors, as implementing and maintaining liquid cooling systems in data centers requires specialized expertise and resources.
- As liquid cooling technologies evolve and become more sophisticated, there is a growing demand for professional services to design, deploy, optimize, and manage these complex infrastructures.
- Liquid cooling solutions often need to be customized and integrated with existing data center infrastructure, including servers, racks, and networking equipment.
- Data center service providers play a crucial role in tailoring liquid cooling solutions to meet the unique requirements of each customer's environment and ensuring seamless integration with their existing systems.
By Cooling Method
- The immersion cooling segment is expected to account for the largest share of the liquid cooling data center market.
- Immersion cooling offers superior cooling efficiency compared to traditional air-based cooling methods.
- By directly immersing IT components in a dielectric fluid, heat can be efficiently dissipated from hotspots, leading to more uniform temperature distribution and better thermal management.
- This capability enables data centers to support higher power densities and achieve better overall cooling performance.
- Such factors are further expected to support the adoption of the immersion cooling segment, thereby fueling the growth of the overall liquid cooling data center market in the coming years.
- Additionally, the immersion cooling segment is projected to register the highest CAGR during the forecast period.
By Data Center Size
- The medium-scale data centers segment is expected to account for the largest share of above 61.0% of the liquid cooling data center market.
- Medium-scale data centers often operate in environments where space is at a premium.
- Liquid cooling solutions, including immersion cooling and direct-to-chip cooling, offer more efficient heat dissipation compared to traditional air cooling methods.
- This allows medium-scale data centers to maximize the use of available space by supporting higher power densities and denser server deployments without compromising on cooling effectiveness.
- Such factors are expected to support the growth of the medium-scale liquid cooling data center segment during the forecast period.
- Additionally, the medium-scale data center segment is projected to register the highest CAGR during the forecast period.
By End User
- The Enterprises Segment to Dominate the Liquid Cooling Data Center Market
- The enterprises segment is segmented into retail & e-commerce, healthcare, IT & telecommunications, BFSI, media & entertainment, and other enterprises.
- The enterprises segment is expected to account for the largest share of above 47.0% of the liquid cooling data center market.
- The large market share of this segment is attributed to the increasing use of colocation services to ensure reliable & scalable infrastructure, the increasing need for a secure and compliant environment to host sensitive patient data and critical applications, the growing need to support IT & telecommunications networks, data storage, and processing requirements.
- Also, liquid cooling solutions offer greater energy efficiency compared to traditional air cooling methods by reducing the need for mechanical cooling and optimizing thermal management.
- As energy costs continue to rise and environmental concerns grow, IT and telecommunications companies are increasingly turning to liquid cooling to reduce operational expenses and meet sustainability goals.
- Additionally, the enterprises segment is projected to register the highest CAGR during the forecast period.
Geographic analysis
North America
Largest shareIn 2025, North America is expected to account for the largest share of above 36.0% of the liquid cooling data center market. The high growth of this market is driven by stringent regulations and sustainability initiatives aimed at reducing energy consumption and carbon emissions in data center operations. Liquid cooling solutions offer greater energy efficiency compared to traditional air cooling methods, making them attractive options for data center operators looking to minimize their environmental footprint and comply with regulatory requirements. Moreover, several key players in this market have launched various initiatives in the development of the market. For instance, in November 2024, Vertiv (U.S.), a global provider of critical digital infrastructure and continuity solutions, launched Vertiv SmartMod Max CW, a prefabricated modular data center designed to address the growing demand for rapid deployment of compute. This configurable and scalable solution supports up to 200kW of total IT load in a single system and utilizes chilled water cooling for reduced environmental impact and energy efficiency. In 2025, North America to Dominate the Liquid Cooling Data Center Market
Asia-Pacific
Fastest growthHowever, Asia-Pacific is expected to record the highest CAGR of 25.0% during the forecast period. The Asia-Pacific region is experiencing rapid growth in data center infrastructure, driven by increasing internet penetration, digital transformation initiatives, and the adoption of cloud computing and edge computing technologies. As data center densities and workloads continue to grow, there is a greater need for efficient cooling solutions to manage heat dissipation and ensure reliable operation. Many countries in the Asia-Pacific region have tropical climates characterized by high temperatures and humidity levels, which pose challenges for traditional air cooling methods. Liquid cooling solutions, such as immersion cooling and direct-to-chip cooling, offer more efficient heat dissipation and thermal management, making them well-suited for data centers operating in hot and humid environments.
Competitive landscape
- April 2025
Accelsius Inc. (U.S.), an Innventure company, launched its two-phase, direct-to-chip liquid cooling technology designed for data centers. The NeuCoolTM system is expected to deliver best-in-class thermal performance for powerful processors that run AI, machine learning, high-performance computing, and other intensive workloads.
- February 2025
SK Enmove (South Kore) signed a Memorandum of Understanding (MOU) with UK-based Precision Liquid Cooling (PLC) specialist Iceotope and big data specialist SK Telecom (South Kore). Under this MOU, the three companies will engage in technical cooperation of data center liquid cooling technology. They plan to load SK Enmove’s thermal fluids into Iceotope’s Precision Liquid Cooling (PLC) solution and seek ways to apply them to SK Telecom’s AI Data Center Testbed (AI DC Testbed).
- January 2025
Aligned Data Centers (U.S.) launched a new liquid cooling technology called DeltaFlow. According to the company, this solution is designed to cater to the high-density computing requirements of next-generation applications and high-performance computing (HPC), including artificial intelligence (AI), machine learning (ML), and supercomputers.
- November 2024
LiquidStack (U.S.), a provider of data center liquid cooling solutions, launched its new single-phase liquid cooling solution to expand into the DataTank product portfolio.
- October 2024
ThermalWorks (U.S.) launched its waterless cooling system built for the fast-changing data center industry. It is designed to handle the ever-increasing density loads required by artificial intelligence and high-performance GPU-based computing. The system supports densities of up to 70 kW per rack with air cooling and up to 200 kW per rack with plug-and-play liquid cooling integration.
- Alfa Laval AB · Sweden
- Asperitas · Netherlands
- Chilldyne, Inc. (U.S.)
- OptiCool Technologies (U.S.)
- Iceotope Technologies Limited (U.K.)
- Fujitsu Limited · Japan
- LiquidStack Holding B.V. (U.S.)
- Motivair Corporation (U.S.)
- Schneider Electric SE · France
- Submer Technologies SL · Spain
- Wiwynn Corporation · Taiwan
- RITTAL GmbH & Co. KG · Germany
- Asetek A/S · Denmark
- ZutaCore, Inc. (U.S.)
- Parker-Hannifin Corporation (U.S.)
Frequently asked questions
The liquid cooling data center market is expected to reach $15.9 billion by 2032, at a CAGR of 23.6% from 2025 to 2032.
Cite this report
Meticulous Research. (2024). Liquid Cooling Data Center Market - Global Opportunity Analysis and Industry Forecast (2025-2032) (Report No. MRICT - 1041234). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/liquid-cooling-data-center-market-5917