Genomics Market (2026-2036)
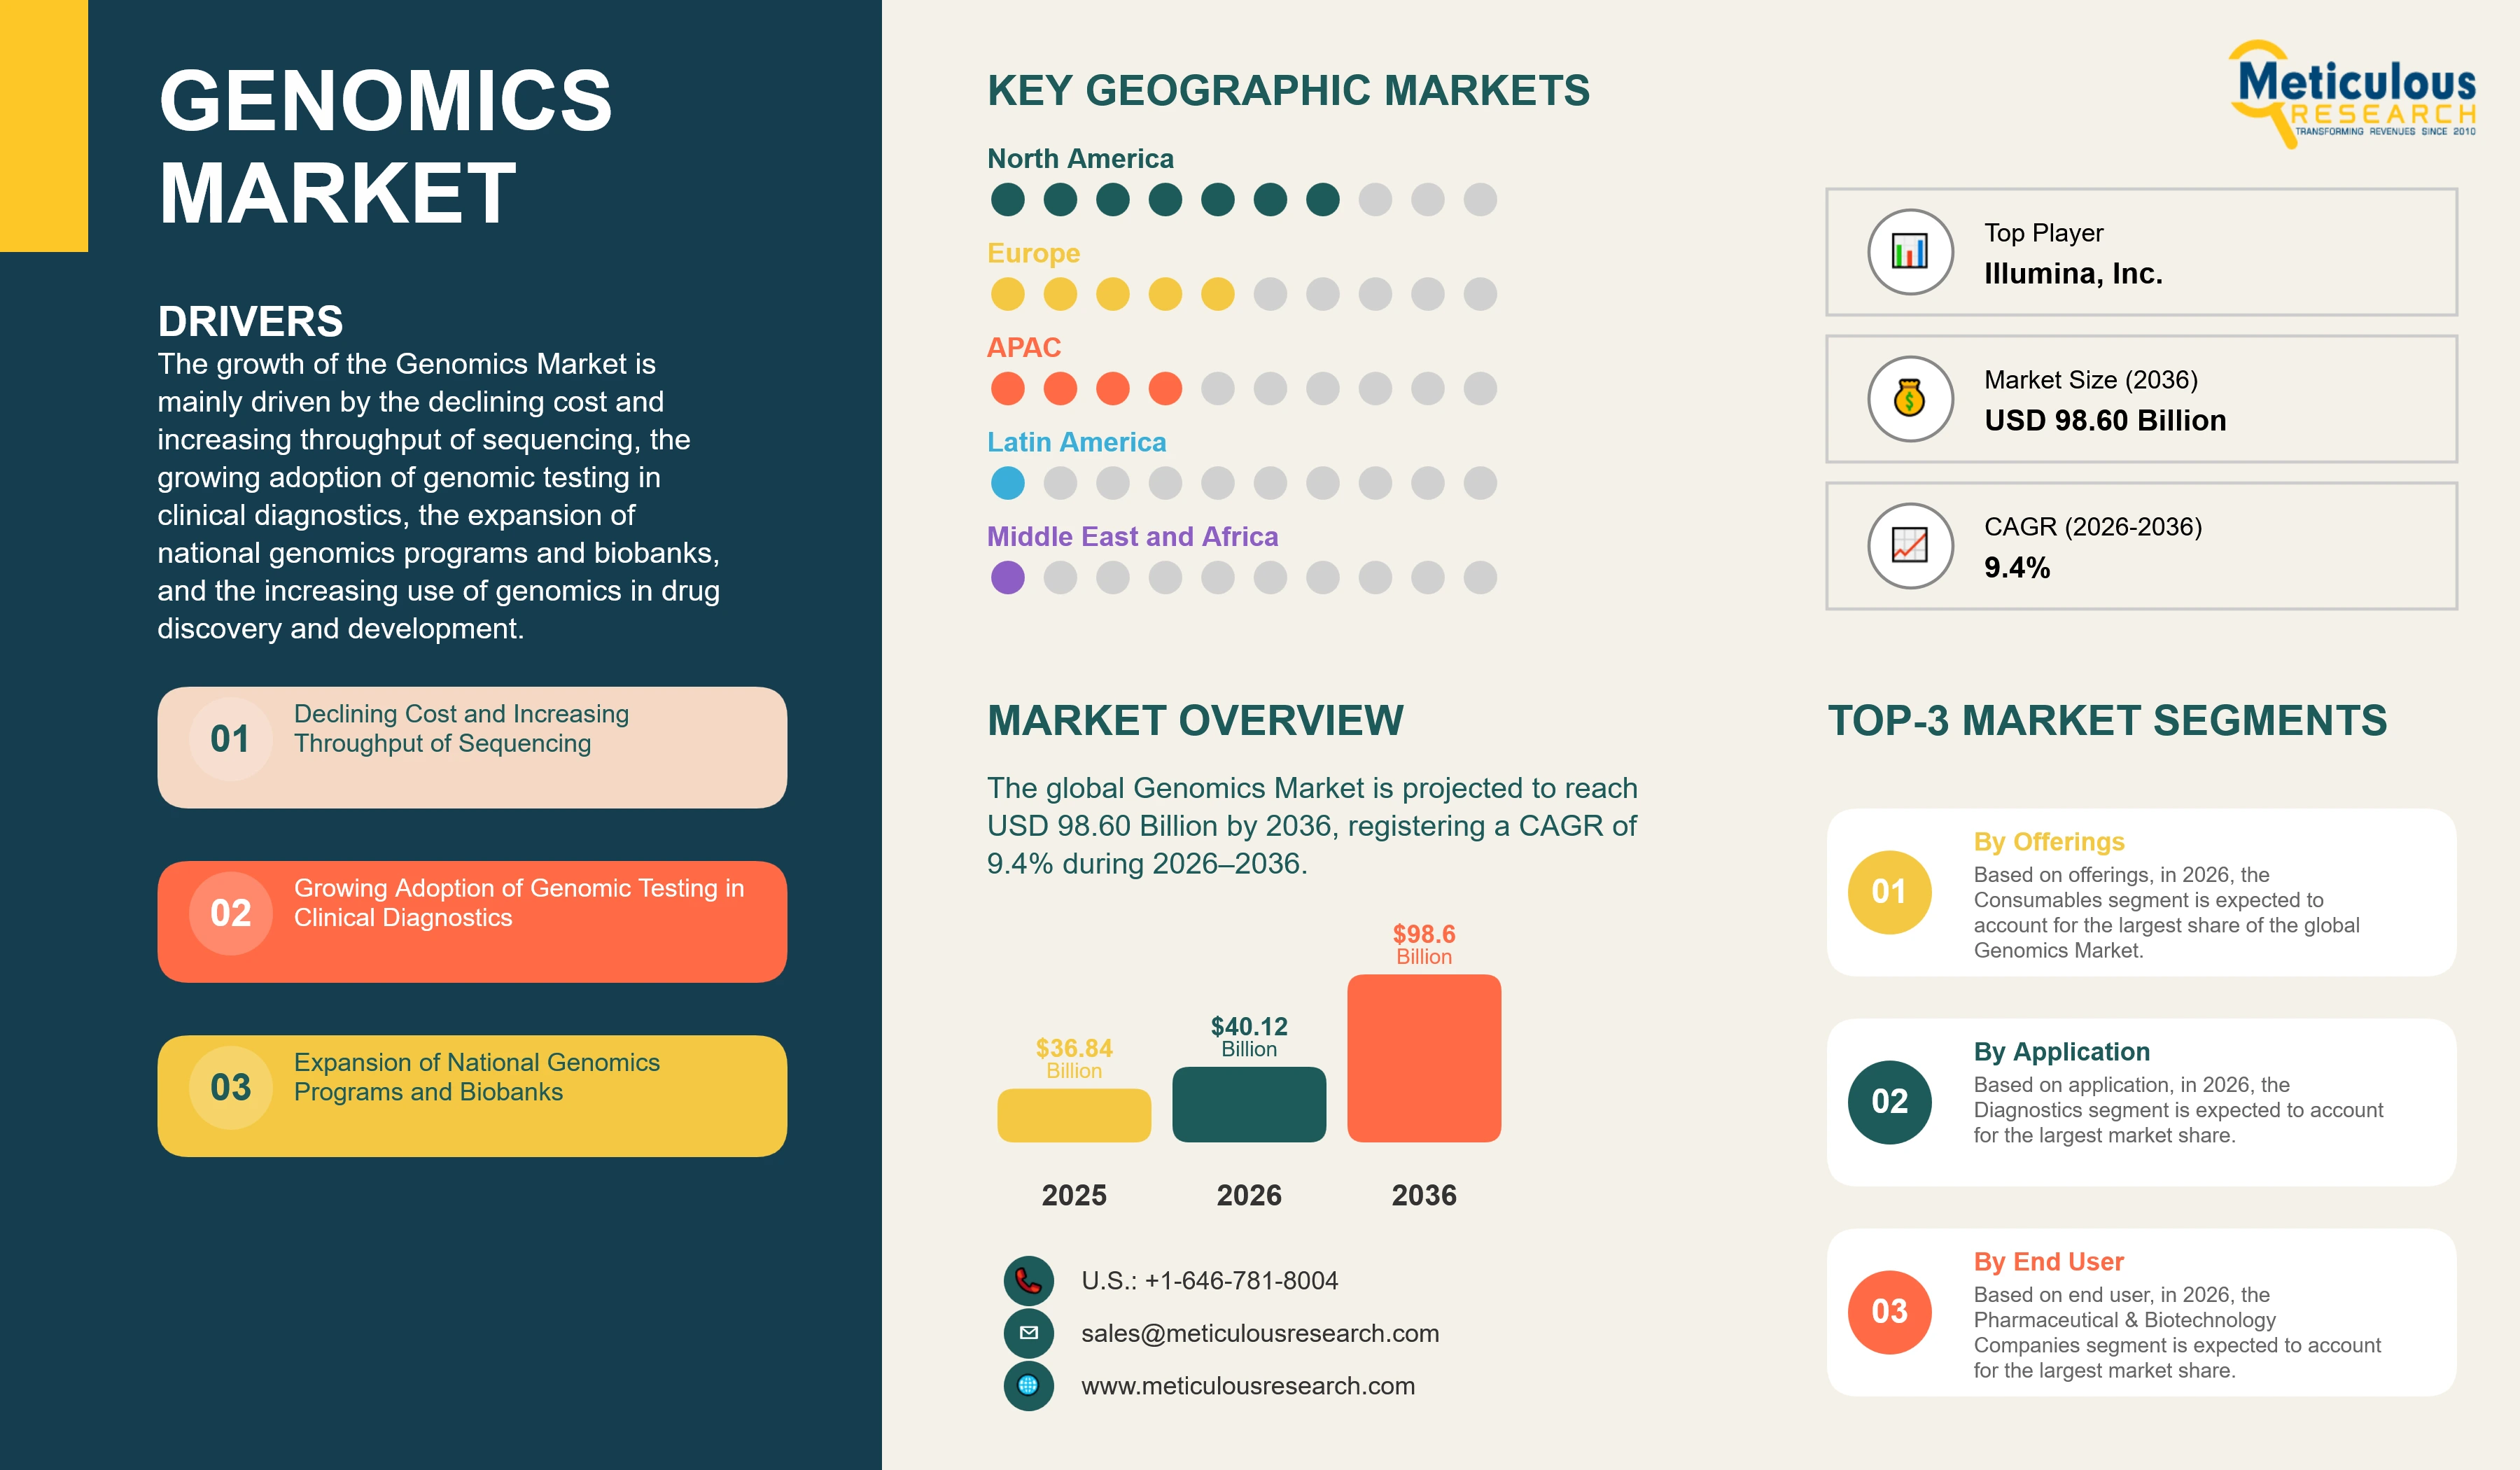
The global Genomics Market was valued at USD 36.84 billion in 2025. This market is expected to reach USD 98.60 billion by 2036 from an estimated USD 40.12 billion in 2026, registering a CAGR of 9.4% during the forecast period (2026-2036).
- Published
- Oct 2026
- Pages
- 320
- Format
- PDF + Excel
- Report ID
- MRHC - 104157
- Base year
- 2025
- 2025 · BASELINE
- $36.84B
- 2036
- $98.60B
- CAGR 2026–2036
- 9.4%
2025 baseline · 2026–2036 forecast at 9.4% CAGR · hover a bar for the value
Key highlights
The global Genomics Market is projected to reach USD 98.60 billion by 2036, driven by lower sequencing costs, clinical genomic testing, national genomics programs, genomics-driven drug development, and new sequencing technologies.
Sequencing demand continues to grow. In the second quarter of 2026, Illumina, Inc. reported revenue of USD 1.16 billion, up 9.5% year over year, including sequencing consumables revenue of USD 775 million, up 5%, and sequencing instrument revenue of USD 125 million, up 31%, and raised its full-year 2026 revenue guidance to USD 4.60-4.64 billion.
Competition in sequencing technology is intensifying. In June 2026, F. Hoffmann-La Roche Ltd launched AXELIOS 1, a high-throughput next-generation sequencing platform based on its sequencing by expansion (SBX) technology, for research use, capable of producing whole-genome results the same day and supporting whole-genome, exome, RNA, single-cell, spatial, and methylation applications.
North America is expected to account for the largest market share in 2026, supported by research funding, clinical genomic testing, and the presence of leading companies, while Asia-Pacific is projected to register the fastest growth during the forecast period.
By technology, Polymerase Chain Reaction (PCR) is expected to account for the largest market share in 2026, whereas Sequencing is projected to witness the fastest growth through 2036, as next-generation sequencing (NGS) expands from research into routine clinical, population, and applied use.
Report summary
| Particulars | Details |
|---|---|
| Forecast Period | 2026-2036 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| CAGR (Value) | 9.4% |
| Format | PDF, Excel & Cloud Portal · 320 pages |
| Market Size (Value) in 2026 | USD 40.12 Billion |
| Market Size (Value) in 2036 | USD 98.60 Billion |
| Segments Covered | By Offering: Instruments, Consumables, Software, Services. By Technology: Polymerase Chain Reaction (Real-Time PCR, Digital PCR, Conventional PCR), Sequencing (Next-Generation Sequencing, Other Sequencing Technologies), Nucleic Acid Extraction & Purification, Microarray, Other Technologies. By Application: Diagnostics (Oncology, Reproductive & Genetic Health, Infectious Diseases, Other Diagnostic Applications), Drug Discovery & Development, Life Science Research (Cancer Research, Stem Cell Research, Other Research Areas), Other Applications. By End User: Pharmaceutical & Biotechnology Companies, Hospitals & Clinics, Diagnostic Laboratories, Contract Research Organizations, Academic & Research Institutes, Other End Users. |
| Countries Covered | North America: U.S., Canada. Europe: Germany, France, U.K., Italy, Spain, Rest of Europe. Asia-Pacific: China, Japan, India, South Korea, Australia, Rest of Asia-Pacific. Latin America: Brazil, Mexico, Rest of Latin America. Middle East & Africa: Saudi Arabia, UAE, Rest of Middle East & Africa. |
| Key Companies | Illumina, Inc., Thermo Fisher Scientific Inc., F. Hoffmann-La Roche Ltd, QIAGEN N.V., Agilent Technologies, Inc., Bio-Rad Laboratories, Inc., Danaher Corporation, Pacific Biosciences of California, Inc., Oxford Nanopore Technologies plc, Eppendorf SE, Myriad Genetics, Inc., Revvity, Inc., and BGI Genomics Co., Ltd. |
Report overview
Segments covered: offering, technology, application, end user.
The growth of this market is mainly driven by the declining cost and increasing throughput of sequencing, the growing adoption of genomic testing in clinical diagnostics for oncology, hereditary disease, reproductive health, and infectious diseases, the expansion of national genomics programs and population-scale biobanks, and the increasing use of genomics in drug discovery and development, including target identification, biomarker discovery, and patient stratification. In addition, the commercialization of new sequencing technologies, including long-read and novel high-throughput platforms, the growth of single-cell, spatial, and multi-omic research, the application of artificial intelligence (AI) to genomic data, and the expanding use of genomics in agriculture, forensics, and environmental applications are further supporting the growth of this market.
The Genomics Market, also referred to as the genomic technologies market, genomics tools and services market, or DNA and RNA analysis market, comprises the instruments, consumables, software, and services used to analyze the structure, function, and variation of genomes for research, diagnostics, drug discovery and development, and applied applications. The market includes polymerase chain reaction (PCR) instruments and reagents, including real-time and digital PCR; sequencing platforms and consumables, including short-read and long-read NGS and Sanger sequencing; nucleic acid extraction and purification products; microarrays for genotyping and gene expression; other genomic technologies such as gene editing, transfection, and cell counting tools; bioinformatics and data analysis software; and sequencing, genotyping, and genomic testing services. The market ecosystem extends from manufacturers of genomic instruments and reagents, software developers, and service providers to academic and research institutes, pharmaceutical and biotechnology companies, contract research organizations (CROs), hospitals and diagnostic laboratories, national genomics programs, and agricultural, forensic, and environmental laboratories.
Genomics has become central to biomedical research and medicine. The cost of sequencing a human genome has fallen dramatically since the completion of the Human Genome Project, making it possible to sequence hundreds of thousands of genomes in national programs and to use genomic testing in routine clinical care. In the second quarter of 2026, Illumina, Inc. reported revenue of USD 1.16 billion, up 9.5% year over year, including sequencing consumables revenue of USD 775 million, up 5%, and sequencing instrument revenue of USD 125 million, up 31%, and raised its full-year 2026 revenue guidance to USD 4.60-4.64 billion. Sequencing, PCR, and other genomic technologies are used across basic research, translational research, clinical diagnostics, and drug development, and their combined use creates a large and diversified market.
Clinical genomics is a major driver of growth. Genomic testing is used for tumor profiling and treatment selection in oncology, hereditary cancer and cardiovascular risk testing, rare disease diagnosis, prenatal and carrier screening, pharmacogenomics, and infectious disease testing. In the second quarter of 2026, Tempus AI, Inc. reported revenue of USD 382.5 million, up 22% year over year, with oncology testing volume up 31%. At the same time, reimbursement remains an important factor; for example, Myriad Genetics reported revenue of USD 190.7 million in the second quarter of 2026, down 11% year over year, despite an 8% increase in hereditary cancer testing volume, reflecting reimbursement pressure.
National genomics programs and biobanks are generating genomic data at population scale. In June 2026, the All of Us Research Program of the NIH expanded its dataset to more than 747,000 participants, including 535,000 whole-genome sequences linked to nearly 482,000 electronic health records and more than 1.3 billion genetic variants. In the U.K., Our Future Health has recruited more than 2 million participants, Genomics England is sequencing the genomes of up to 100,000 newborns in its Generation Study, and in Europe, the 1+ Million Genomes initiative is building a cross-border genomic data infrastructure. Programs in the Middle East and Asia-Pacific are also expanding, creating demand for sequencing, genotyping, and data analysis.
The technology landscape is becoming more competitive. Illumina remains the leading provider of short-read sequencing, while Pacific Biosciences and Oxford Nanopore Technologies provide long-read sequencing, and new entrants and established companies are launching new platforms. In June 2026, F. Hoffmann-La Roche Ltd launched AXELIOS 1, a high-throughput next-generation sequencing platform based on its sequencing by expansion (SBX) technology, for research use, capable of producing whole-genome results the same day and supporting whole-genome, exome, RNA, single-cell, spatial, and methylation applications. In the first half of 2026, Oxford Nanopore Technologies plc reported revenue of approximately GBP 116.5 million, up about 10%, with clinical revenue up 35%, biopharma revenue up 25%, and applied markets revenue up 22%, while revenue declined in China and the Middle East due to stricter export controls and geopolitical tensions. Thermo Fisher Scientific, QIAGEN, Bio-Rad Laboratories, Danaher, Agilent Technologies, Revvity, and Eppendorf provide PCR, extraction, library preparation, and other genomic products, and BGI Genomics is a major provider in China.
Research funding and geopolitical factors affect the market. In February 2026, the U.S. Consolidated Appropriations Act, 2026 set the National Institutes of Health (NIH) program level at USD 47.49 billion for fiscal year 2026, an increase of 1.0% over fiscal year 2025, after the administration had proposed a cut of more than 40%. While the final appropriation reduced uncertainty, academic research spending remained cautious during the year. In addition, trade tensions between the U.S. and China have affected the genomics industry. In March 2025, China barred Illumina from exporting sequencers to the country and placed the company on its Unreliable Entity List; although China announced in November 2025 that it would lift the export ban, Illumina remained on the list, and sales outside China accounted for approximately 97% of Illumina revenue.
At the same time, the market faces challenges, including variability in research funding, reimbursement pressure on clinical genomic tests, the high cost of sequencing instruments for smaller laboratories, the complexity of managing and interpreting large genomic datasets, data privacy and ethical concerns, and trade restrictions. As a result, companies that combine competitive cost per sample, strong clinical and regulatory capabilities, integrated workflows from sample to insight, data analysis and AI capabilities, and broad geographic presence are expected to capture the largest share of growth over the forecast period.
Report infographic
Market dynamics
15 factors across 5 forcesDeclining Cost and Increasing Throughput of Sequencing
The declining cost and increasing throughput of sequencing is a major factor driving the Genomics Market, as lower costs expand the range of applications in which sequencing is economically viable. High-throughput sequencers allow large laboratories and genome centers to sequence many thousands of genomes per year, and new platforms continue to increase speed and reduce costs. In the second quarter of 2026, Illumina, Inc. reported revenue of USD 1.16 billion, up 9.5% year over year, including sequencing consumables revenue of USD 775 million, up 5%, and sequencing instrument revenue of USD 125 million, up 31%, and raised its full-year 2026 revenue guidance to USD 4.60-4.64 billion. The 31% growth in Illumina sequencing instrument revenue in the second quarter of 2026 indicates continued investment in sequencing capacity.
Lower costs are also enabling new applications such as whole-genome sequencing in clinical care, population-scale sequencing, single-cell and spatial genomics, and the use of sequencing in agriculture and environmental monitoring. As costs continue to decline with competition from new platforms, such as the AXELIOS 1 platform launched by Roche in June 2026, sequencing is expected to become even more widely used.
Growing Adoption of Genomic Testing in Clinical Diagnostics
The growing adoption of genomic testing in clinical diagnostics is significantly driving market growth. Comprehensive genomic profiling and liquid biopsy are increasingly used to guide cancer treatment, hereditary cancer testing is expanding, rare disease diagnosis increasingly uses exome and genome sequencing, and prenatal, carrier, and newborn screening use genomic methods. In the second quarter of 2026, Tempus AI, Inc. reported revenue of USD 382.5 million, up 22% year over year, with oncology testing volume up 31%. Oxford Nanopore reported 35% growth in clinical revenue in the first half of 2026, reflecting the adoption of long-read sequencing in clinical applications.
Expansion of National Genomics Programs and Biobanks
The expansion of national genomics programs and biobanks is an important driver of demand. In June 2026, the All of Us Research Program of the NIH expanded its dataset to more than 747,000 participants, including 535,000 whole-genome sequences linked to nearly 482,000 electronic health records and more than 1.3 billion genetic variants. Programs such as Our Future Health, Genomics England, UK Biobank, and the 1+ Million Genomes initiative in Europe, and national genome programs in the Middle East and Asia-Pacific, require large volumes of sequencing, genotyping, extraction, and data analysis. These programs also generate data that drive research and drug discovery.
Biobanks are expanding beyond genotyping and short-read sequencing to long-read sequencing, proteomics, and single-cell analysis. UK Biobank plans releases in 2027 that include long-read whole-genome sequencing with epigenetic data for up to 50,000 participants and single-cell RNA sequencing, creating demand for advanced genomic technologies.
Increasing Use of Genomics in Drug Discovery and Development
The increasing use of genomics in drug discovery and development supports market growth. Drug targets supported by human genetic evidence are more likely to succeed in clinical development, and pharmaceutical companies use genomic data for target identification, biomarker discovery, patient stratification, and companion diagnostic development. Oxford Nanopore reported 25% growth in biopharma revenue in the first half of 2026, and Illumina is expanding its data and insights offering for pharmaceutical customers. Cell and gene therapy development also relies heavily on genomic technologies for vector characterization, quality control, and gene editing.
Table of contents
12 chapters · 151 sections · 320 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Offering | Consumables | Services |
| By Technology | PCR | Sequencing |
| By Application | Diagnostics | Drug Discovery & Development |
| By End User | Pharmaceutical & Biotechnology Companies | Contract Research Organizations |
By Offering
- Consumables include reagents, kits, and assay products, while Services include sequencing services, genotyping services, genomic testing services, and data analysis services.
- The Consumables segment is expected to account for the largest share of the global Genomics Market.
- The large share of this segment is mainly due to the recurring use of reagents and kits for every sequencing, PCR, extraction, and microarray run, the large installed base of genomic instruments, and the growth of testing volumes.
- Sequencing consumables accounted for USD 775 million of the USD 1.16 billion in revenue reported by Illumina in the second quarter of 2026.
- However, the Services segment is projected to register the highest CAGR during the forecast period.
- The rapid growth of this segment is attributed to the outsourcing of sequencing and genomic analysis by pharmaceutical companies and research institutions, the growth of clinical genomic testing services, the demand for bioinformatics and data analysis expertise, and the growth of genomic data and insights services.
- The Software segment is also expected to record strong growth.
By Technology
- PCR is further segmented into Real-Time PCR, Digital PCR, and Conventional PCR, while Sequencing is further segmented into Next-Generation Sequencing, including short-read and long-read sequencing, and Other Sequencing Technologies, including Sanger sequencing, pyrosequencing, chromatin immunoprecipitation sequencing, and methylation sequencing.
- Other Technologies include gene editing, transfection, and cell counting.
- The PCR segment is expected to account for the largest share of the market.
- The large share of this segment is mainly due to the widespread use of real-time PCR in molecular diagnostics, infectious disease testing, gene expression analysis, and research, the large installed base of PCR instruments in research and clinical laboratories, and the growth of digital PCR for oncology, liquid biopsy, and cell and gene therapy applications.
- However, the Sequencing segment is projected to register the highest CAGR during the forecast period.
- The rapid growth of this segment is attributed to the declining cost of sequencing, the growth of clinical genome and exome sequencing, comprehensive genomic profiling, national genomics programs, single-cell and spatial genomics, and the commercialization of new long-read and high-throughput platforms.
- Long-read sequencing is expected to be the fastest-growing area within sequencing.
By Application
- Diagnostics is further segmented into Oncology, Reproductive & Genetic Health, Infectious Diseases, and Other Diagnostic Applications, while Life Science Research is further segmented into Cancer Research, Stem Cell Research, and Other Research Areas, including cardiovascular disease, immunology, neurobiology, and diabetes.
- Other Applications include agriculture, forensics, and environmental applications.
- The Diagnostics segment is expected to account for the largest share of the market.
- The large share of this segment is mainly due to the widespread use of PCR and sequencing for infectious disease, oncology, hereditary disease, and reproductive testing, the growth of comprehensive genomic profiling and liquid biopsy, and the large volume of clinical genomic tests performed by hospitals and diagnostic laboratories.
- However, the Drug Discovery & Development segment is projected to register the highest CAGR during the forecast period.
- The rapid growth of this segment is attributed to the use of human genetic evidence for target selection, the growth of biomarker-driven and precision medicine drug development, the use of genomics in cell and gene therapy development, the growth of pharmaceutical partnerships with biobanks and genomic data providers, and the 25% growth in biopharma revenue reported by Oxford Nanopore in the first half of 2026.
By End User
- Other End Users include food and beverage, agricultural, and forensic organizations.
- The Pharmaceutical & Biotechnology Companies segment is expected to account for the largest share of the market.
- The large share of this segment is mainly due to the extensive use of genomic technologies in drug discovery, development, and manufacturing quality control, the significant research and development budgets of these companies, and their investment in genomic data and partnerships with biobanks.
- However, the Contract Research Organizations segment is projected to register the highest CAGR during the forecast period.
- The rapid growth of this segment is attributed to the increasing outsourcing of sequencing, genomic analysis, and biomarker services by pharmaceutical and biotechnology companies, the demand for specialized expertise and capacity, and the growth of genomics in clinical trials.
- Diagnostic Laboratories are also expected to grow strongly, supported by clinical genomic testing.
Geographic analysis
North America
Largest shareIn 2026, North America is expected to account for the largest share of the global Genomics Market. The large share of this region is mainly attributed to substantial research funding, large pharmaceutical and biotechnology industries, the high adoption of clinical genomic testing, major programs such as All of Us, and the presence of leading companies such as Illumina, Thermo Fisher Scientific, Pacific Biosciences, Agilent Technologies, Bio-Rad Laboratories, Danaher, Revvity, and Myriad Genetics. In February 2026, the U.S. Consolidated Appropriations Act, 2026 set the National Institutes of Health (NIH) program level at USD 47.49 billion for fiscal year 2026, an increase of 1.0% over fiscal year 2025, after the administration had proposed a cut of more than 40%.
Europe
Europe is expected to account for a significant share of the market, supported by national genomics programs and biobanks, such as Genomics England, Our Future Health, and UK Biobank, the 1+ Million Genomes initiative, strong research institutions, and the presence of companies such as Roche, QIAGEN, Oxford Nanopore Technologies, and Eppendorf. Oxford Nanopore reported 23% constant-currency growth in Europe, the Middle East, Africa, and India in the first half of 2026.
Asia-Pacific
Fastest growthAsia-Pacific is projected to register the highest CAGR during the forecast period. The growth of this region is driven by investment in genomics and precision medicine in China, Japan, India, South Korea, Singapore, and Australia, national genome programs, the growth of clinical genomic testing and pharmaceutical research, and the presence of domestic companies such as BGI Genomics in China. At the same time, trade restrictions affect the market in China, where domestic suppliers are gaining share.
Latin America
Latin America and the Middle East & Africa are expected to account for smaller shares of the market.
Middle East & Africa
In the Middle East, national genome programs in Saudi Arabia, the UAE, and Qatar are driving demand for sequencing and analysis, although geopolitical tensions affected some suppliers in 2026, while in Latin America, research and clinical genomics in Brazil and Mexico are expected to support growth.
Competitive landscape
The global Genomics Market is moderately consolidated, with a group of leading companies holding significant shares in sequencing, PCR, extraction, and microarrays, alongside long-read sequencing companies, new sequencing entrants, genomic testing companies, and regional manufacturers. Market participants compete primarily on cost per sample, accuracy, throughput, read length, speed, workflow integration, regulatory approvals for clinical use, software and data analysis capabilities, and global presence.
Leading companies are launching new sequencing platforms, expanding long-read and multi-omic capabilities, developing clinical products and workflows, building data and AI capabilities, and pursuing acquisitions and partnerships. Recent examples include the launch of the Roche AXELIOS 1 sequencing platform in June 2026, the 31% growth in Illumina sequencing instrument revenue in the second quarter of 2026, and the acquisition of Parse Biosciences by QIAGEN.
The report provides a comprehensive competitive assessment of the leading companies operating in the global Genomics Market. The key players profiled in the report include Illumina, Inc. (U.S.), Thermo Fisher Scientific Inc. (U.S.), F. Hoffmann-La Roche Ltd (Switzerland), QIAGEN N.V. (Netherlands), Agilent Technologies, Inc. (U.S.), Bio-Rad Laboratories, Inc. (U.S.), Danaher Corporation (U.S.), Pacific Biosciences of California, Inc. (U.S.), Oxford Nanopore Technologies plc (U.K.), Eppendorf SE (Germany), Myriad Genetics, Inc. (U.S.), Revvity, Inc. (U.S.), and BGI Genomics Co., Ltd (China).
- Illumina, Inc.
- Thermo Fisher Scientific Inc.
- F. Hoffmann-La Roche Ltd
- QIAGEN N.V.
- Agilent Technologies, Inc.
- Bio-Rad Laboratories, Inc.
- Danaher Corporation
- Pacific Biosciences of California, Inc.
- Oxford Nanopore Technologies plc
- Eppendorf SE
- Myriad Genetics, Inc.
- Revvity, Inc.
- BGI Genomics Co., Ltd
Expert perspectives
The Genomics Market is entering a phase in which growth is increasingly driven by clinical, biopharma, and applied markets rather than academic research alone. With Illumina reporting continued growth in sequencing and raising its 2026 guidance, Oxford Nanopore reporting 35% growth in clinical revenue in the first half of 2026, and national programs such as All of Us reaching 535,000 whole genomes, genomics is becoming part of routine healthcare and drug development. The binding constraint is shifting from the cost of generating genomic data to the ability to interpret it, reimburse it, and use it in clinical and commercial decisions.
Three structural changes are expected to shape competitive positions through 2036. First, competition in sequencing is intensifying with new platforms such as AXELIOS 1 and the growth of long-read sequencing, which is expected to reduce costs and broaden adoption. Second, clinical genomics is expected to become the largest source of growth, favoring companies with regulatory-approved products and strong reimbursement strategies. Third, data, software, and AI are expected to account for a growing share of value, favoring companies that integrate instruments with analysis and insights.
For companies planning entry or expansion, the most defensible positions over the forecast period are likely to be found in long-read and high-throughput sequencing, clinical genomic workflows, single-cell and spatial genomics, genomic data and AI services for pharmaceutical companies, and genomics in emerging markets and applied fields. For established providers, the principal priorities are maintaining cost competitiveness, expanding clinical applications, managing trade risks, and building data capabilities.
Overall, the market is expected to grow strongly, with consumables, PCR, diagnostics, pharmaceutical and biotechnology companies, and North America providing the core of demand and services, sequencing, drug discovery and development, contract research organizations, and Asia-Pacific providing the fastest growth.
Customer perspectives
Insights gathered during primary interviews with genome center directors, clinical laboratory directors, and pharmaceutical genomics leaders operating in this market highlight where procurement priorities are shifting. The following perspectives reflect recurring themes raised across these discussions.
“This reflects increasing competition in sequencing technology.”
“This indicates the importance of efficiency in clinical genomics.”
“This points to the growing role of genomics in drug discovery.”
Frequently asked questions
The global Genomics Market is estimated at USD 40.12 billion in 2026.
Cite this report
Meticulous Research. (2026). Genomics Market - Global Opportunity Analysis And Industry Forecast (2026-2036) (Report No. MRHC - 104157). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/genomics-market-1262