Veterinary Molecular Diagnostics Market (2026-2036)
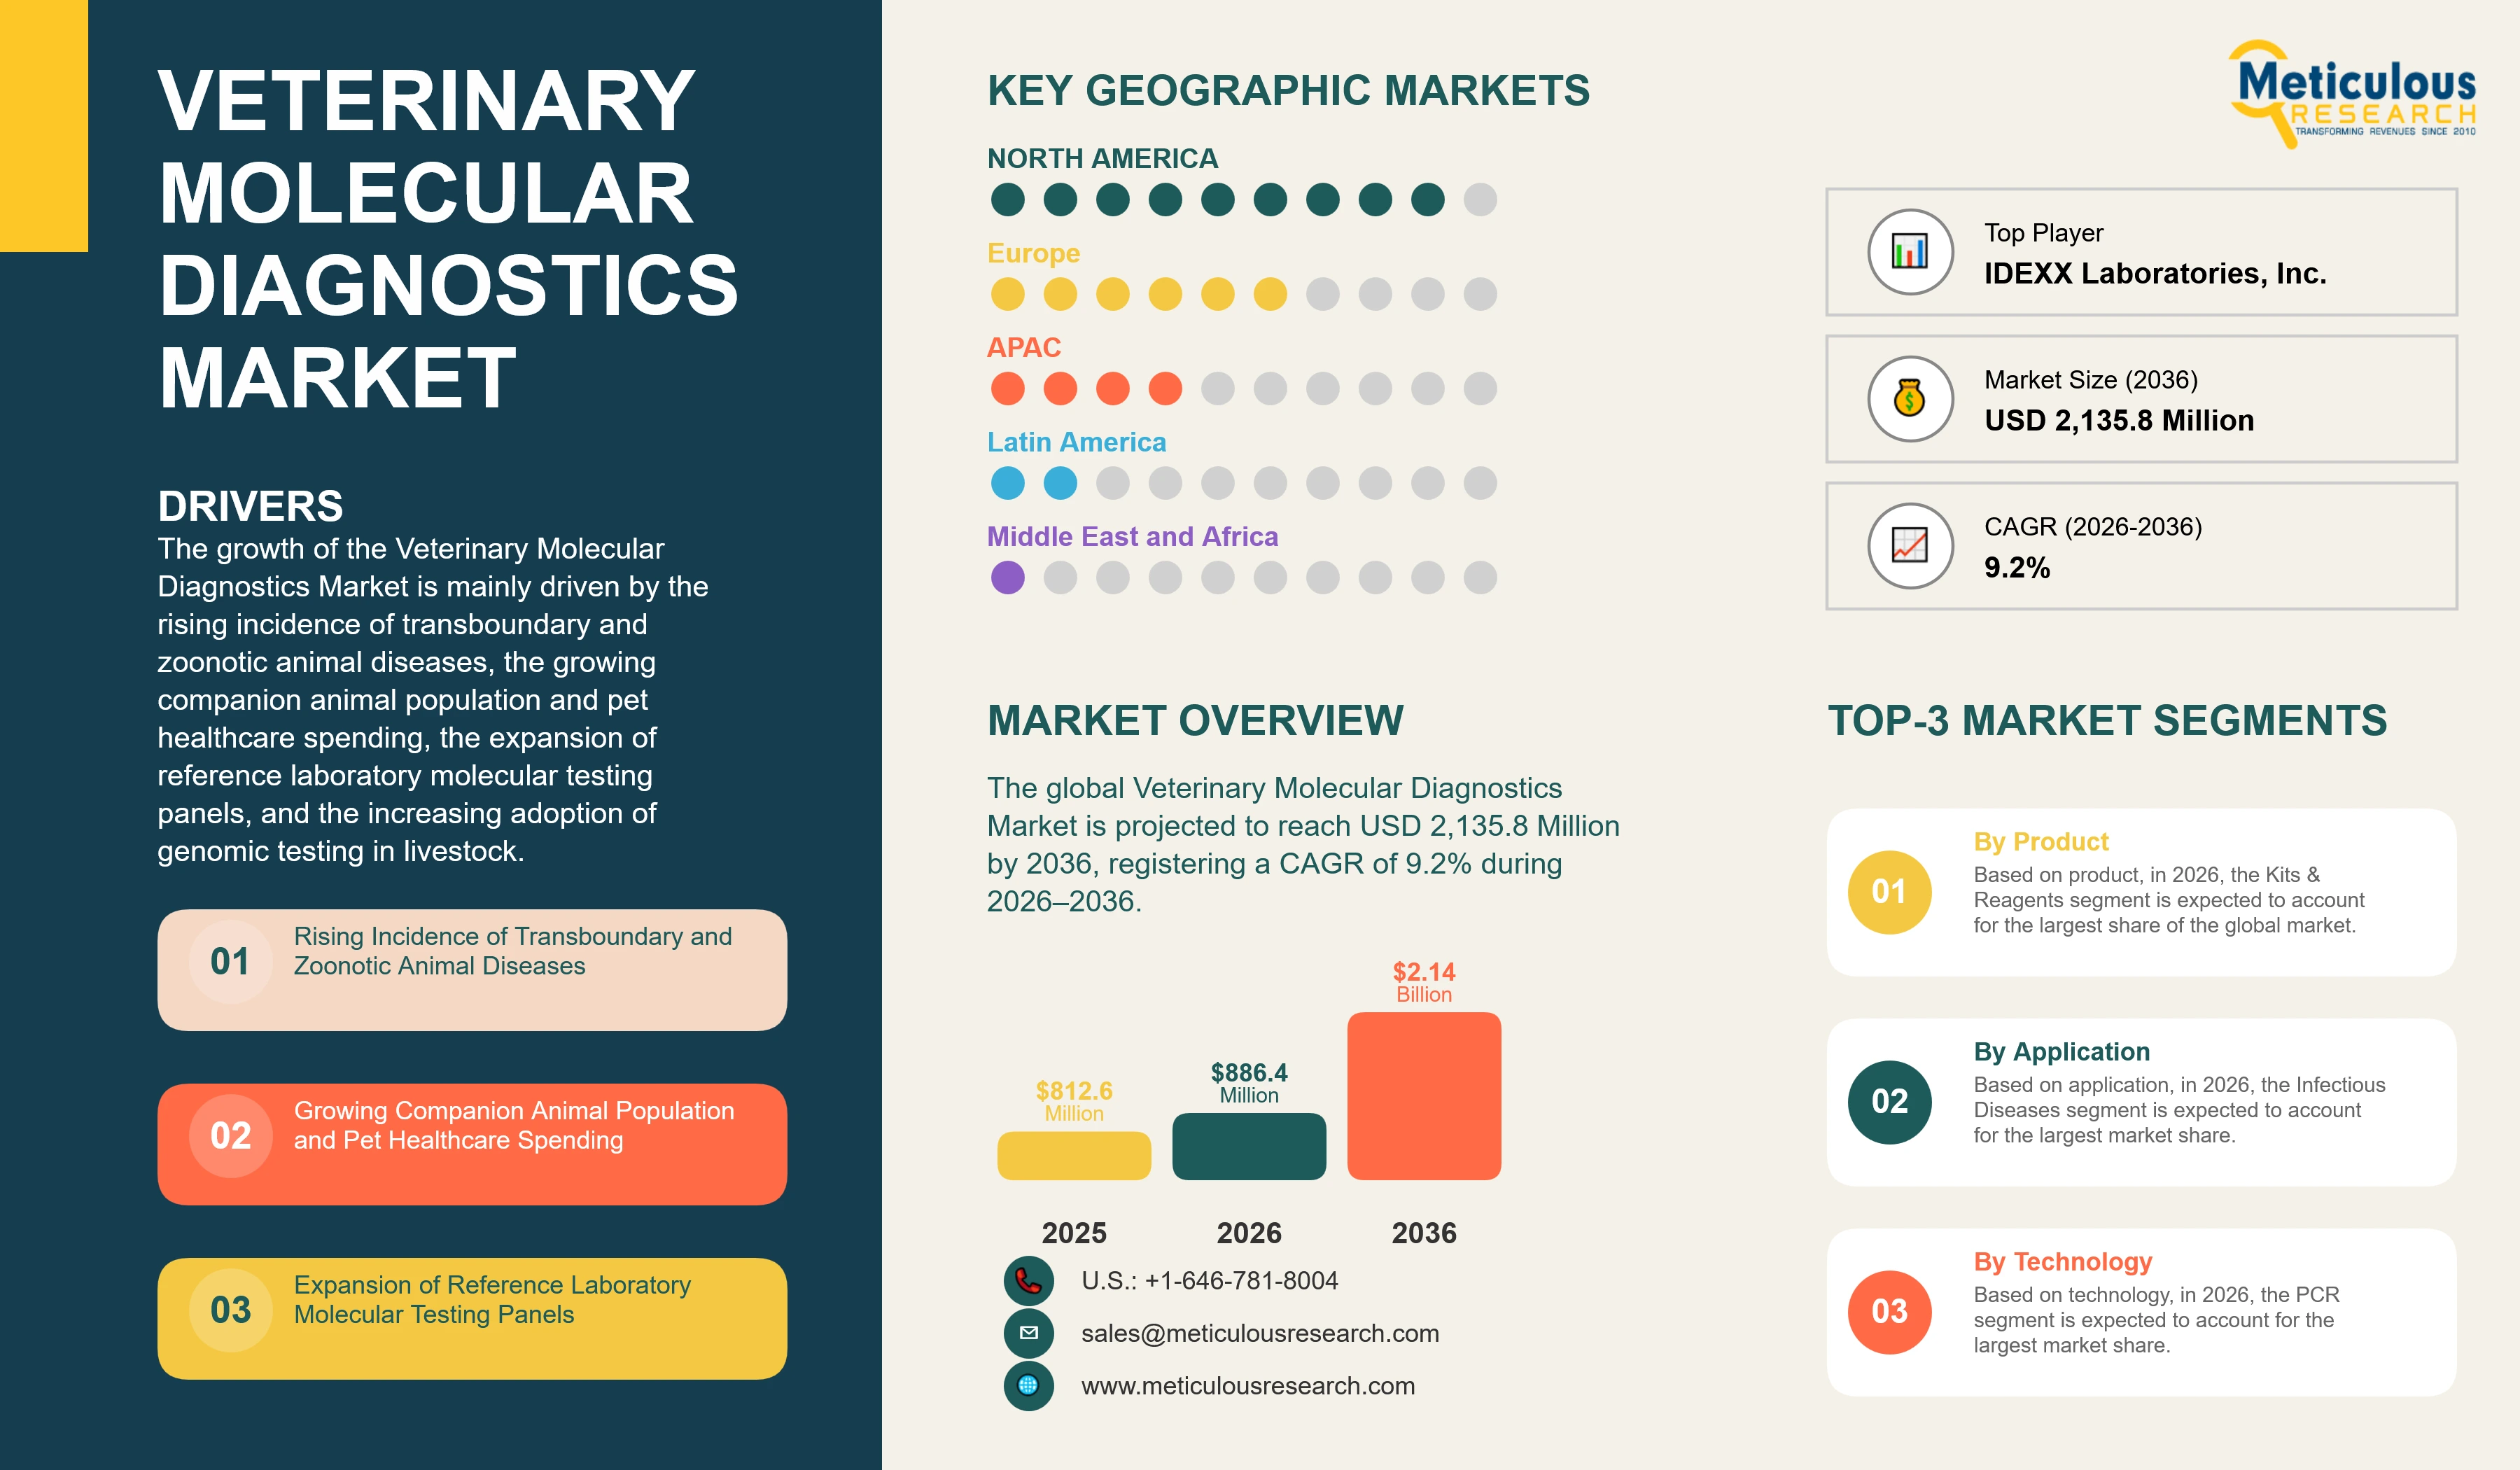
The global Veterinary Molecular Diagnostics Market was valued at USD 812.6 million in 2025. This market is expected to reach USD 2,135.8 million by 2036 from an estimated USD 886.4 million in 2026, registering a CAGR of 9.2% during the forecast period (2026-2036).
- Published
- Oct 2026
- Pages
- 250
- Format
- PDF + Excel
- Report ID
- MRHC - 104598
- Base year
- 2025
- 2025 · BASELINE
- $812.6M
- 2036
- $2.14B
- CAGR 2026–2036
- 9.2%
2025 baseline · 2026–2036 forecast at 9.2% CAGR · hover a bar for the value
Key highlights
The global Veterinary Molecular Diagnostics Market is projected to reach USD 2, 135.8 million by 2036, driven by transboundary animal disease surveillance, companion animal infectious disease testing, livestock genomics, and point-of-care molecular testing.
Transboundary animal diseases continue to drive molecular testing demand. According to the World Organisation for Animal Health (WOAH), 76 countries and territories reported African swine fever (ASF) between January 2022 and June 2026, with 14,951 outbreaks in domestic pigs, 2.74 million animal losses, and 34,388 outbreaks in wild boar, and in July 2026 Finland reported its first-ever occurrence of the disease in wild boar.
Companion animal diagnostics continue to grow. In the second quarter of 2026, IDEXX Laboratories, Inc. reported revenue of USD 1,217 million, up 10% year over year, with Companion Animal Group (CAG) Diagnostics recurring revenue of USD 974.7 million, up 11%, reference laboratory diagnostic and consulting services revenue of USD 406.7 million, up 11%, and Livestock, Poultry and Dairy revenue of USD 35.2 million, up 11%, and the company raised its full-year 2026 revenue guidance to USD 4,700-4,745 million.
North America is expected to account for the largest market share in 2026, supported by high companion animal healthcare spending, large reference laboratory networks, and H5N1 surveillance in dairy cattle, while Asia-Pacific is projected to register the fastest growth during the forecast period.
By technology, Polymerase Chain Reaction (PCR) is expected to account for the largest market share in 2026, whereas DNA Sequencing is projected to witness the fastest growth through 2036, as laboratories adopt sequencing for pathogen genotyping, outbreak tracing, antimicrobial resistance detection, and genomic selection.
Report summary
| Particulars | Details |
|---|---|
| Forecast Period | 2026-2036 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| CAGR (Value) | 9.2% |
| Format | PDF, Excel & Cloud Portal · 250 pages |
| Market Size (Value) in 2026 | USD 886.4 Million |
| Market Size (Value) in 2036 | USD 2,135.8 Million |
| Segments Covered | By Product: Kits & Reagents (PCR Assay Kits, Nucleic Acid Extraction Kits, Sequencing Kits & Reagents, Other Reagents), Instruments (PCR Systems, Sequencing Systems, Nucleic Acid Extraction Systems, Point-of-Care Molecular Analyzers), Software. By Technology: Polymerase Chain Reaction (Real-Time PCR, Digital PCR, Conventional PCR), DNA Sequencing (Next-Generation Sequencing, Sanger Sequencing), Microarray, Other Technologies. By Application: Infectious Diseases (Viral Diseases, Bacterial Diseases, Parasitic Diseases, Fungal Diseases), Genetics (Genetic Disease Testing, Genomic Selection & Trait Testing, Parentage & Identity Testing), Metabolic Diseases, Other Applications. By Animal Type: Companion Animals (Dogs, Cats, Horses, Other Companion Animals), Livestock Animals (Cattle, Swine, Poultry, Small Ruminants, Other Livestock Animals). By End User: Veterinary Reference & Diagnostic Laboratories, Veterinary Hospitals & Clinics, Research Institutes. |
| Countries Covered | North America: U.S., Canada. Europe: Germany, France, U.K., Italy, Spain, Netherlands, Poland, Rest of Europe. Asia-Pacific: China, Japan, India, South Korea, Australia, Vietnam, Rest of Asia-Pacific. Latin America: Brazil, Mexico, Argentina, Rest of Latin America. Middle East & Africa: Saudi Arabia, South Africa, Rest of Middle East & Africa. |
| Key Companies | IDEXX Laboratories, Inc., Antech Diagnostics, Inc. (Mars, Incorporated), Zoetis Inc., Thermo Fisher Scientific Inc., QIAGEN N.V., Bio-Rad Laboratories, Inc., Neogen Corporation, Indical Bioscience GmbH, and Innovative Diagnostics SAS. |
Report overview
Segments covered: product, technology, application, animal type, end user.
The growth of this market is mainly driven by the rising incidence of transboundary and zoonotic animal diseases such as African swine fever, highly pathogenic avian influenza, and bluetongue, which require rapid and sensitive PCR testing for surveillance and outbreak control; the growing companion animal population and rising spending on pet healthcare; the expansion of reference laboratory molecular testing panels for companion animals; and the increasing adoption of genomic testing in livestock breeding and production. In addition, the shift toward point-of-care molecular testing in veterinary clinics, the growing use of sequencing for pathogen characterization and genomic surveillance, the One Health approach to zoonotic disease monitoring, and the expansion of veterinary laboratory infrastructure in emerging economies are further supporting the growth of this market.
The Veterinary Molecular Diagnostics Market, also referred to as the animal molecular diagnostics market, veterinary PCR testing market, or veterinary nucleic acid testing market, comprises the kits and reagents, instruments, and software used to detect and analyze the DNA and RNA of pathogens and animals for the diagnosis, surveillance, and management of animal diseases and for genetic testing. The market includes real-time PCR, digital PCR, and conventional PCR assays for viral, bacterial, parasitic, and fungal pathogens; multiplex syndromic panels for respiratory, gastrointestinal, vector-borne, and reproductive diseases; nucleic acid extraction kits and automated extraction systems; PCR thermal cyclers and point-of-care molecular analyzers; DNA sequencing for pathogen characterization, genomic surveillance, and genotyping; microarrays for genotyping and genomic selection; and laboratory information and data analysis software. The market ecosystem extends from manufacturers of molecular assays, instruments, and sequencing platforms to veterinary reference laboratories, national and state veterinary diagnostic laboratories, veterinary hospitals and clinics, livestock producers and breeding organizations, and research institutes.
Molecular diagnostics has become an essential part of veterinary medicine because of its sensitivity, specificity, and speed. PCR can detect very small amounts of pathogen genetic material, often before clinical signs appear or antibodies develop, and can distinguish closely related pathogens and strains. These capabilities make molecular testing the method of choice for confirming outbreaks of notifiable diseases, screening animals before movement and trade, monitoring herds and flocks, and diagnosing infectious diseases in companion animals. Multiplex PCR panels now allow veterinarians to test for many pathogens in a single sample, supporting faster and more targeted treatment.
Transboundary and zoonotic animal diseases are a major source of demand. According to the World Organisation for Animal Health (WOAH), 76 countries and territories reported African swine fever (ASF) between January 2022 and June 2026, with 14,951 outbreaks in domestic pigs, 2.74 million animal losses, and 34,388 outbreaks in wild boar, and in July 2026 Finland reported its first-ever occurrence of the disease in wild boar. Because there is no widely available vaccine for ASF in most countries, control depends on early detection, culling, and movement restrictions, all of which rely on PCR testing by national and regional laboratories. Highly pathogenic avian influenza (HPAI) H5N1 has spread widely in wild birds and poultry and, since 2024, in dairy cattle in the U.S. In the U.S., the U.S. Department of Agriculture (USDA) Animal and Plant Health Inspection Service (APHIS) continues to implement the National Milk Testing Strategy with State veterinarians for H5N1 surveillance of the national milk supply and dairy herds, alongside the Federal Order of April 2024 requiring testing of lactating dairy cattle before interstate movement. In the U.K., the Department for Environment, Food and Rural Affairs (Defra) confirmed 270 cases of bluetongue virus serotype 3 (BTV-3) on farm holdings in England and Wales by August 7, 2026, less than a month after the first case of the 2026-2027 season was confirmed on July 10, 2026, following 348 cases in Great Britain in the 2025-2026 season. These outbreaks create sustained demand for PCR kits, extraction reagents, and high-throughput laboratory instruments.
The companion animal segment is the other major driver of the market. Pet ownership and spending on veterinary care have grown strongly, and veterinarians increasingly use molecular testing to diagnose respiratory, gastrointestinal, vector-borne, and other infectious diseases in dogs and cats. In the second quarter of 2026, IDEXX Laboratories, Inc. reported revenue of USD 1,217 million, up 10% year over year, with Companion Animal Group (CAG) Diagnostics recurring revenue of USD 974.7 million, up 11%, reference laboratory diagnostic and consulting services revenue of USD 406.7 million, up 11%, and Livestock, Poultry and Dairy revenue of USD 35.2 million, up 11%, and the company raised its full-year 2026 revenue guidance to USD 4,700-4,745 million. Reference laboratories offer extensive PCR panels, and the development of point-of-care molecular analyzers is beginning to bring PCR testing into the veterinary clinic.
Genetics is an increasingly important application. Livestock producers use DNA genotyping for genomic selection, parentage verification, and the identification of genetic defects and traits, and companion animal owners and breeders use DNA tests for genetic disease screening and breed identification. In March 2026, Neogen Corporation announced the sale of its global genomics business, operating under the GeneSeek brand and including the Igenity and GGP portfolios, to Zoetis Inc. for USD 160 million; the business generated approximately USD 90 million in sales in fiscal 2025. This transaction reflects the strategic importance of animal genomics and the convergence of diagnostics and genetics in animal health.
The market includes leading animal health and diagnostics companies such as IDEXX Laboratories, Antech Diagnostics (part of Mars, Incorporated), and Zoetis, life science companies such as Thermo Fisher Scientific, QIAGEN, and Bio-Rad Laboratories, and specialized veterinary molecular diagnostics providers such as Indical Bioscience, Innovative Diagnostics, and Neogen. These companies compete on the breadth of assay menus, regulatory approvals and validations, sensitivity and specificity, laboratory throughput and automation, turnaround time, and the integration of testing with practice management and data systems.
At the same time, the market faces challenges, including the high cost of molecular testing relative to rapid antigen and antibody tests, limited laboratory infrastructure and skilled personnel in many developing countries, the need for regulatory approval or validation of veterinary assays in different countries, and the interpretation of PCR results, as the detection of nucleic acid does not always indicate active infection. Price sensitivity in livestock production and fluctuations in demand linked to outbreak cycles also affect the market. As a result, companies that combine broad and validated assay menus, high-throughput and point-of-care platforms, sequencing capabilities, and strong relationships with reference laboratories and national veterinary authorities are expected to capture the largest share of growth over the forecast period.
Report infographic
Market dynamics
15 factors across 5 forcesRising Incidence of Transboundary and Zoonotic Animal Diseases
The rising incidence of transboundary and zoonotic animal diseases is a major factor driving the Veterinary Molecular Diagnostics Market, as governments and producers depend on rapid and sensitive PCR testing to detect, contain, and monitor outbreaks. According to the World Organisation for Animal Health (WOAH), 76 countries and territories reported African swine fever (ASF) between January 2022 and June 2026, with 14,951 outbreaks in domestic pigs, 2.74 million animal losses, and 34,388 outbreaks in wild boar, and in July 2026 Finland reported its first-ever occurrence of the disease in wild boar. The spread of ASF to new countries in Europe requires national laboratories to test large numbers of domestic pigs and wild boar, and countries free of the disease maintain surveillance programs to detect any introduction.
Avian influenza and vector-borne diseases add further demand. HPAI H5N1 continues to affect poultry and wild birds globally and has affected dairy cattle in the U.S., where national milk testing and pre-movement testing rely on PCR. In the U.K., the Department for Environment, Food and Rural Affairs (Defra) confirmed 270 cases of bluetongue virus serotype 3 (BTV-3) on farm holdings in England and Wales by August 7, 2026, less than a month after the first case of the 2026-2027 season was confirmed on July 10, 2026, following 348 cases in Great Britain in the 2025-2026 season. Each outbreak requires testing to confirm cases, define restricted zones, and support movement and trade, creating recurring demand for molecular kits, reagents, and laboratory capacity.
Growing Companion Animal Population and Pet Healthcare Spending
The growing companion animal population and rising spending on pet healthcare are significantly driving market growth. Pet owners increasingly treat pets as family members and are willing to spend more on diagnostics and treatment, and veterinarians are using more diagnostic testing to support accurate diagnosis. In the second quarter of 2026, IDEXX Laboratories, Inc. reported revenue of USD 1,217 million, up 10% year over year, with Companion Animal Group (CAG) Diagnostics recurring revenue of USD 974.7 million, up 11%, reference laboratory diagnostic and consulting services revenue of USD 406.7 million, up 11%, and Livestock, Poultry and Dairy revenue of USD 35.2 million, up 11%, and the company raised its full-year 2026 revenue guidance to USD 4,700-4,745 million. Growth in reference laboratory testing, which includes PCR panels for infectious diseases, reflects increasing diagnostic use per clinical visit.
Expansion of Reference Laboratory Molecular Testing Panels
The expansion of reference laboratory molecular testing panels is an important driver of demand. Veterinary reference laboratories offer real-time PCR panels for canine and feline respiratory disease, diarrhea, vector-borne diseases, and other conditions, allowing veterinarians to test for multiple pathogens from a single sample with rapid turnaround. Large reference laboratory networks operated by IDEXX and Antech Diagnostics serve veterinary practices across many countries, and the continued addition of new targets and panels is increasing the use of molecular testing in routine practice.
Reference laboratories are also investing in automation and high-throughput molecular platforms to manage growing test volumes and reduce turnaround times. Automated nucleic acid extraction, liquid handling, and real-time PCR systems allow laboratories to process large numbers of samples efficiently, and integration with practice management software allows veterinarians to order tests and receive results electronically. These investments support the adoption of molecular testing in routine companion animal practice.
Increasing Adoption of Genomic Testing in Livestock
The increasing adoption of genomic testing in livestock is supporting market growth. Dairy and beef cattle, swine, and poultry breeders use DNA genotyping for genomic selection, which improves the accuracy of breeding decisions and accelerates genetic progress in traits such as productivity, health, and fertility. Parentage verification, traceability, and the identification of genetic diseases also rely on DNA testing. In March 2026, Neogen Corporation announced the sale of its global genomics business, operating under the GeneSeek brand and including the Igenity and GGP portfolios, to Zoetis Inc. for USD 160 million; the business generated approximately USD 90 million in sales in fiscal 2025. As producers seek to improve productivity, animal health, and sustainability, demand for livestock genomic testing is expected to grow.
Table of contents
13 chapters · 168 sections · 250 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Product | Kits & Reagents | Software |
| By Technology | PCR | DNA Sequencing |
| By Application | Infectious Diseases | Genetics |
| By Animal Type | Companion Animals | Livestock Animals |
| By End User | Veterinary Reference & Diagnostic Laboratories | Veterinary Hospitals & Clinics |
By Product
- Veterinary Molecular Diagnostics Market Analysis by Product
- Kits & Reagents are further segmented into PCR Assay Kits, Nucleic Acid Extraction Kits, Sequencing Kits & Reagents, and Other Reagents, while instruments are further segmented into PCR Systems, Sequencing Systems, Nucleic Acid Extraction Systems, and Point-of-Care Molecular Analyzers.
- The Kits & Reagents segment is expected to account for the largest share of the global Veterinary Molecular Diagnostics Market.
- The large share of this segment is mainly due to the recurring use of PCR kits and extraction reagents in every test, the high volume of testing for transboundary animal diseases such as ASF, avian influenza, and bluetongue, and the growth of reference laboratory molecular panels for companion animals.
- Outbreaks such as the spread of ASF in Europe, H5N1 in U.S. dairy cattle, and BTV-3 in the U.K. require large volumes of testing, driving demand for kits and reagents.
- However, the Software segment is projected to register the highest CAGR during the forecast period.
- The rapid growth of this segment is attributed to the increasing integration of molecular testing with laboratory information systems, practice management software, and surveillance platforms, the growth of sequencing data requiring bioinformatics analysis, and the adoption of data-driven disease surveillance.
- The Instruments segment is expected to record steady growth, supported by laboratory automation and the adoption of point-of-care molecular analyzers.
By Technology
- Veterinary Molecular Diagnostics Market Analysis by Technology
- PCR is further segmented into Real-Time PCR, Digital PCR, and Conventional PCR, while DNA Sequencing is further segmented into Next-Generation Sequencing and Sanger Sequencing.
- Other Technologies include isothermal amplification methods such as loop-mediated isothermal amplification (LAMP).
- The PCR segment is expected to account for the largest share of the market.
- The large share of this segment is mainly due to the established role of real-time PCR as the standard method for detecting and confirming viral and bacterial pathogens, its recommendation in WOAH diagnostic standards for many notifiable diseases, its use in national surveillance programs for ASF, avian influenza, and bluetongue, and its widespread use in reference laboratory panels for companion animals.
- However, the DNA Sequencing segment is projected to register the highest CAGR during the forecast period.
- The rapid growth of this segment is attributed to the declining cost of sequencing, the increasing use of whole-genome sequencing for pathogen characterization, outbreak tracing, and antimicrobial resistance detection, and the use of sequencing-based genotyping in livestock and companion animal genetics.
- The Microarray segment is expected to remain important for livestock genomic selection.
By Application
- Veterinary Molecular Diagnostics Market Analysis by Application
- Infectious Diseases are further segmented into Viral Diseases, Bacterial Diseases, Parasitic Diseases, and Fungal Diseases, while Genetics is further segmented into Genetic Disease Testing, Genomic Selection & Trait Testing, and Parentage & Identity Testing.
- Other Applications include oncology and pharmacogenetics.
- The Infectious Diseases segment is expected to account for the largest share of the market.
- The large share of this segment is mainly due to the importance of PCR for the diagnosis and surveillance of viral, bacterial, and parasitic diseases in livestock and companion animals, the impact of ASF, avian influenza, bluetongue, and other transboundary diseases, and the wide use of infectious disease panels in companion animal practice.
- However, the Genetics segment is projected to register the highest CAGR during the forecast period.
- The rapid growth of this segment is attributed to the increasing adoption of genomic selection in dairy and beef cattle, swine, and poultry, the growing use of DNA testing for genetic diseases and traits in dogs and cats, and investment by animal health companies in genomics, including the agreement of Zoetis to acquire the genomics business of Neogen.
By Animal Type
- Veterinary Molecular Diagnostics Market Analysis by Animal Type
- Companion Animals are further segmented into Dogs, Cats, Horses, and Other Companion Animals, while Livestock Animals are further segmented into Cattle, Swine, Poultry, Small Ruminants, and Other Livestock Animals.
- The Companion Animals segment is expected to account for the largest share of the market.
- The large share of this segment is mainly due to high spending on pet healthcare, the extensive use of reference laboratory PCR panels for dogs and cats, and the strong growth of companion animal diagnostics, reflected in the 11% growth in CAG Diagnostics recurring revenue reported by IDEXX in the second quarter of 2026.
- However, the Livestock Animals segment is projected to register the highest CAGR during the forecast period.
- The rapid growth of this segment is attributed to the spread of ASF, avian influenza, bluetongue, and other transboundary diseases, the expansion of national surveillance and pre-movement testing programs, and the growing adoption of genomic testing in livestock breeding.
- The Cattle segment is expected to account for a major share within livestock animals, supported by H5N1 testing in dairy cattle, bluetongue surveillance, and genomic selection.
By End User
- Veterinary Molecular Diagnostics Market Analysis by End User
- Veterinary Reference & Diagnostic Laboratories include commercial reference laboratories and national, state, and university veterinary diagnostic laboratories.
- The Veterinary Reference & Diagnostic Laboratories segment is expected to account for the largest share of the market.
- The large share of this segment is mainly due to the concentration of molecular testing in laboratories with the required instruments and expertise, the large companion animal reference laboratory networks of IDEXX and Antech Diagnostics, and the role of national and state laboratories in testing for notifiable diseases such as ASF, HPAI, and bluetongue.
- However, the Veterinary Hospitals & Clinics segment is projected to register the highest CAGR during the forecast period.
- The rapid growth of this segment is attributed to the development of point-of-care molecular analyzers, the demand of veterinarians for faster results during the clinical visit, and the growth of large veterinary hospital groups investing in in-house diagnostic capabilities.
Geographic analysis
North America
Largest shareIn 2026, North America is expected to account for the largest share of the global Veterinary Molecular Diagnostics Market. The large share of this region is mainly attributed to high spending on companion animal healthcare, the large reference laboratory networks of IDEXX and Antech Diagnostics, the presence of leading companies such as IDEXX, Zoetis, Thermo Fisher Scientific, and Neogen, and extensive livestock disease surveillance. In the U.S., the U.S. Department of Agriculture (USDA) Animal and Plant Health Inspection Service (APHIS) continues to implement the National Milk Testing Strategy with State veterinarians for H5N1 surveillance of the national milk supply and dairy herds, alongside the Federal Order of April 2024 requiring testing of lactating dairy cattle before interstate movement. The U.S. is also the largest market for livestock genomic testing.
Europe
Europe is expected to account for a significant share of the market, supported by the spread of ASF in wild boar and domestic pigs, outbreaks of bluetongue and avian influenza, strong national veterinary laboratory systems, and growing companion animal healthcare spending. In the U.K., the Department for Environment, Food and Rural Affairs (Defra) confirmed 270 cases of bluetongue virus serotype 3 (BTV-3) on farm holdings in England and Wales by August 7, 2026, less than a month after the first case of the 2026-2027 season was confirmed on July 10, 2026, following 348 cases in Great Britain in the 2025-2026 season. Specialized veterinary molecular diagnostics providers such as Indical Bioscience in Germany and Innovative Diagnostics in France, and QIAGEN in the Netherlands and Germany, are based in the region.
Asia-Pacific
Fastest growthAsia-Pacific is projected to register the highest CAGR during the forecast period. The growth of this region is driven by large pig and poultry populations, the impact of ASF and avian influenza in China, Vietnam, the Philippines, and other countries, investment in veterinary diagnostic laboratories, and the rapid growth of pet ownership and pet healthcare spending in China, Japan, South Korea, and India. China is the largest pig-producing country in the world, and ASF control and the growth of large commercial farms are driving demand for PCR testing.
Latin America
Latin America and the Middle East & Africa are expected to account for smaller shares of the market. In Latin America, large livestock industries in Brazil, Argentina, and Mexico and the growing companion animal market are expected to support demand, while in the Middle East & Africa, investment in veterinary services and disease control programs is expected to support growth.
Competitive landscape
The global Veterinary Molecular Diagnostics Market is moderately consolidated, with leading animal health and diagnostics companies, life science and molecular diagnostics companies, and specialized veterinary molecular diagnostics providers participating across regions and applications. Market participants compete primarily on the breadth of assay menus, regulatory approvals and validations, sensitivity and specificity, laboratory throughput and automation, turnaround time, point-of-care capabilities, and relationships with reference laboratories and national veterinary authorities.
Leading companies are expanding assay menus, developing multiplex panels and point-of-care molecular platforms, investing in automation and sequencing, integrating diagnostics with software and data platforms, and pursuing acquisitions. Recent examples include the continued growth of IDEXX reference laboratory revenue, the agreement of Zoetis to acquire the genomics business of Neogen in March 2026, and the integration of Heska into Antech Diagnostics under Mars, Incorporated.
The report provides a comprehensive competitive assessment of the leading companies operating in the global Veterinary Molecular Diagnostics Market. The key players profiled in the report include IDEXX Laboratories, Inc. (U.S.), Antech Diagnostics, Inc. (Mars, Incorporated) (U.S.), Zoetis Inc. (U.S.), Thermo Fisher Scientific Inc. (U.S.), QIAGEN N.V. (Netherlands), Bio-Rad Laboratories, Inc. (U.S.), Neogen Corporation (U.S.), Indical Bioscience GmbH (Germany), and Innovative Diagnostics SAS (France).
- IDEXX Laboratories, Inc.
- Antech Diagnostics, Inc. (Mars, Incorporated)
- Zoetis Inc.
- Thermo Fisher Scientific Inc.
- QIAGEN N.V.
- Bio-Rad Laboratories, Inc.
- Neogen Corporation
- Indical Bioscience GmbH
- Innovative Diagnostics SAS
Expert perspectives
The Veterinary Molecular Diagnostics Market is being shaped by two powerful demand sources: recurring transboundary animal disease outbreaks and the steady growth of companion animal healthcare. With ASF reported in 76 countries and territories since 2022 and reaching Finland in July 2026, H5N1 surveillance continuing in U.S. dairy herds, and bluetongue cases rising in the U.K., molecular testing has become central to animal disease control, while reference laboratory molecular panels are growing with companion animal diagnostics. The binding constraint is shifting from the availability of PCR assays to the capacity, speed, and integration of molecular testing, as laboratories and veterinarians seek faster results, broader panels, and data that support decisions.
Three structural changes are expected to shape competitive positions through 2036. First, point-of-care molecular testing is expected to move some testing from reference laboratories into clinics and farms, favoring companies with easy-to-use platforms and broad assay menus. Second, sequencing is expected to become a routine tool for pathogen characterization, surveillance, and genetics, favoring companies with sequencing and bioinformatics capabilities. Third, consolidation of diagnostics and genetics is strengthening large animal health companies with integrated offerings.
For companies planning entry or expansion, the most defensible positions over the forecast period are likely to be found in validated assays for transboundary and emerging diseases, point-of-care molecular platforms, sequencing and bioinformatics for veterinary laboratories, livestock and companion animal genetic testing, and laboratory capacity building in Asia-Pacific and other emerging regions. For established providers, the principal priorities are expanding multiplex panels, integrating testing with software and surveillance data, and maintaining strong relationships with national veterinary authorities.
Overall, the market is expected to grow steadily, with kits and reagents, PCR, infectious diseases, companion animals, reference and diagnostic laboratories, and North America providing the core of demand and software, sequencing, genetics, livestock animals, veterinary hospitals and clinics, and Asia-Pacific providing the fastest growth.
Customer perspectives
Insights gathered during primary interviews with veterinary laboratory directors, companion animal veterinarians, and livestock production veterinarians operating in this market highlight where procurement priorities are shifting. The following perspectives reflect recurring themes raised across these discussions.
“This reflects the importance of surge capacity in disease surveillance.”
“This indicates the demand for point-of-care molecular testing.”
“This points to the balance between surveillance and cost in livestock.”
Frequently asked questions
The global Veterinary Molecular Diagnostics Market is estimated at USD 886.4 million in 2026.
Cite this report
Meticulous Research. (2026). Veterinary Molecular Diagnostics Market - Global Opportunity Analysis And Industry Forecasts (2026-2036) (Report No. MRHC - 104598). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/veterinary-molecular-diagnostics-market-5284