Functional Safety Microcontrollers (MCUs) Market (2026-2036)
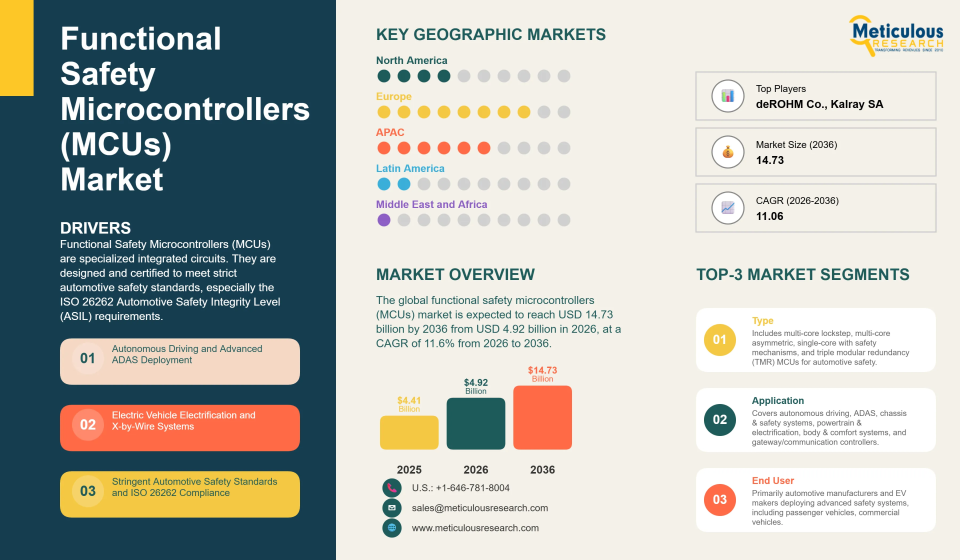
The global functional safety microcontrollers (MCUs) market is expected to reach USD 14.73 billion by 2036 from USD 4.92 billion in 2026, at a CAGR of 11.6% from 2026 to 2036.
- Published
- Jan 2026
- Pages
- 261
- Format
- PDF + Excel
- Report ID
- MRAUTO - 1041662
- Base year
- 2025
- 2026 · ESTIMATED
- $4.92B
- 2036
- $14.73B
- CAGR 2026–2036
- 11.6%
2025 baseline · 2026–2036 forecast at 11.6% CAGR · hover a bar for the value
Key highlights
In 2026, Europe accounts for the largest share of the global functional safety microcontrollers market, driven by stringent automotive safety regulations, strong presence of premium automotive manufacturers implementing advanced safety systems, and established automotive safety culture requiring ISO 26262 compliance.
Asia-Pacific is projected to register the highest CAGR during the forecast period, fueled by rapidly growing automotive production, increasing adoption of ADAS and autonomous driving technologies, expanding electric vehicle segment requiring safety-certified control systems, and rising safety awareness in emerging automotive markets.
Based on ASIL level, the ASIL D segment holds the largest share of the market in 2026, driven by the highest safety integrity requirements for mission-critical systems including autonomous driving, brake control, and steering control that demand the most stringent functional safety certification.
Based on core architecture, the multi-core lockstep segment dominates the market in 2026, owing to its superior fault detection capabilities through redundant core operation and ability to meet ASIL D requirements for safety-critical applications.
Based on peripherals, the integrated safety peripherals segment is expected to witness significant growth during the forecast period, driven by demand for comprehensive on-chip safety mechanisms reducing external component requirements and system complexity.
Based on software support, the AUTOSAR-compliant segment accounts for the largest share of the market in 2026, fueled by industry-wide adoption of standardized automotive software architecture and requirement for interoperability across multi-supplier automotive systems.
The ASIL C segment is expected to grow at a significant CAGR during the forecast period, driven by expanding adoption in ADAS features, electric vehicle powertrain control, and advanced chassis systems requiring high but not maximum safety integrity levels.
The U.S. functional safety microcontrollers market is projected to grow at a CAGR of around 10% during the forecast period 2026 to 2036, driven by increasing deployment of autonomous driving systems, NHTSA safety initiatives, and strong automotive technology innovation ecosystem.
China is expected to lead the Asia-Pacific functional safety microcontrollers market, driven by massive automotive production volumes, government mandates for ADAS and autonomous driving safety features, rapid electric vehicle adoption, and growing domestic capability in automotive semiconductor design.
In 2026, Germany is projected to account for the largest share of the European functional safety microcontrollers market, driven by its automotive industry leadership, concentration of tier-1 automotive suppliers, and pioneering development of autonomous driving and advanced safety systems by manufacturers like BMW, Mercedes-Benz, and Audi.
Report summary
| Particulars | Details |
|---|---|
| Market Size Value in 2026 | USD 4.92 Billion |
| Revenue Forecast in 2036 | USD 14.73 Billion |
| Growth Rate | CAGR of 11.6% from 2026 to 2036 |
| Format | PDF, Excel & Cloud Portal · 261 pages |
| Base Year for Estimation | 2025 |
| Historical Data | 2021–2025 |
| Forecast Period | 2026–2036 |
| Quantitative Units | Revenue in USD Billion and CAGR from 2026 to 2036 |
| Report Coverage | Revenue forecast, company ranking, competitive landscape, growth factors, and trends |
| Segments Covered | ASIL Level, Core Architecture, Peripherals, Software Support, Application, Vehicle Type, Region |
| Regional Scope | North America, Europe, Asia-Pacific, Latin America, Middle East & Africa |
| Countries Covered | U.S., Canada, Germany, U.K., France, Italy, Spain, Japan, China, South Korea, India, Taiwan, Brazil, Mexico, Saudi Arabia, UAE |
| Key Companies Profiled | Infineon Technologies AG, NXP Semiconductors N.V., Renesas Electronics Corporation, STMicroelectronics N.V., Texas Instruments Incorporated, Microchip Technology Inc., Analog Devices Inc., ON Semiconductor Corporation, Cypress Semiconductor Corporation (Infineon), ROHM Co. Ltd., Toshiba Electronic Devices & Storage Corporation, Fujitsu Limited, Hitachi Automotive Systems Ltd., Kalray SA, Nordic Semiconductor ASA, Telechips Inc., SiEngine Technology, Horizon Robotics, Black Sesame Technologies, Arm Holdings plc |
Report overview
Segments covered: asil level, core architecture, peripheral, software support, application.
Functional Safety Microcontrollers (MCUs) are specialized integrated circuits. They are designed and certified to meet strict automotive safety standards, especially the ISO 26262 Automotive Safety Integrity Level (ASIL) requirements. This ensures reliable and safe operation in safety-critical automotive applications.
These microcontrollers include hardware-level safety features. They have error detection and correction (EDAC) for memory, redundant processing cores for lockstep operation, built-in self-test (BIST) capabilities, safety monitors and watchdogs, and fail-safe state management. These features help detect, diagnose, and respond to potential failures that could threaten vehicle safety.
By using fault-tolerant designs and extensive diagnostic coverage, functional safety MCUs support critical automotive systems. These systems include advanced driver assistance systems (ADAS), electronic stability control, electric power steering, brake-by-wire, steer-by-wire, and autonomous driving functions. These features help achieve the safety integrity levels required by international standards and regulations.
Functional Safety Microcontrollers represent an important development in automotive semiconductor technology. They move from basic reliability methods to carefully designed and certified safety systems that provide measurable and verifiable safety. These microcontrollers form the core of safety-critical automotive systems. If they malfunction, it could cause serious injury or death. Therefore, designers must create hardware and software that can detect failures, keep systems operating safely during faults, and switch to fail-safe modes as needed. By embedding safety features directly into their silicon design and supporting structured safety development processes, functional safety MCUs allow automakers to implement more complex electronic control systems while adhering to strict international safety standards.
Several key trends are changing the functional safety microcontrollers market. These include rapid advancements in autonomous driving technology that need ASIL D-certified computing platforms. The electrification of vehicle powertrains is creating new safety-critical applications for battery management and motor control. The rise of advanced driver assistance systems is broadening the range of safety-critical electronic functions. Additionally, automotive electrical and electronic systems are evolving toward centralized domain controllers and zone controllers, which consolidate safety functions and require higher-performance safety MCUs. The combined effects of regulatory pressure from safety standards like ISO 26262, advancements in fault-tolerant semiconductor design, the safety needs of autonomous vehicles, and a commitment across the industry to a vision of zero fatalities have made functional safety MCUs essential for next-generation automotive systems.
The functional safety microcontrollers market is shifting toward more sophisticated and higher-performance safety systems. There is a deeper integration of safety features across all system levels. Advanced functional safety MCUs are progressing beyond basic dual-core lockstep setups. They now include complex safety ecosystems with multi-core lockstep clusters that support heterogeneous processing for AI, extensive on-chip safety monitors, diagnostics, hardware virtualization, and the ability to manage mixed-criticality tasks. They also integrate with external safety elements like safety companion chips and system basis chips. The combination of multiple safety features—redundant cores, memory protection units, error correction codes, built-in self-test, cross-checking paths, and fail-safe state management—allows these MCUs to achieve ASIL D certification with measurable diagnostic coverage and fault management capabilities.
Automotive Safety Integrity Level (ASIL) requirements are pushing architectural changes in functional safety MCUs. ASIL D, the highest level, requires an extremely low chance of safety violations (less than 10^-8 failures per hour) and extensive fault detection, isolation, and handling abilities. Modern ASIL D MCUs use multiple layers of redundancy, such as dual-core or triple-core lockstep for processing, along with duplicated or triplicated safety-critical peripherals, robust memory protection, error detection and correction, and comprehensive diagnostics for all safety-critical functions. The complexity and verification needed for ASIL D certification create considerable technical and financial challenges, concentrating the market among established semiconductor suppliers with significant automotive safety knowledge and the resources to execute rigorous certification processes.
The shift to autonomous driving is fundamentally altering the requirements for functional safety MCUs. As vehicles move through the Society of Automotive Engineers (SAE) automation levels from Level 2 to Level 4, the criticality of computing platforms increases significantly, as human drivers are no longer constantly monitoring the system and ready to step in. This has led to a higher demand for high-performance ASIL D-certified MCUs and system-on-chips (SoCs) capable of executing complex perception, decision-making, and control tasks while ensuring thorough fault detection and safe operation. Many autonomous driving systems use safety architectures that combine primary computing platforms with independent safety MCUs that supervise system behavior and can safely halt the vehicle if issues arise.
Report infographic
Market dynamics
4 factors across 2 forcesAutonomous Driving and Advanced ADAS Deployment
The rapid growth and rollout of autonomous driving technologies and advanced driver assistance systems are the main factors fueling the adoption and development of functional safety microcontrollers. As vehicles move through SAE automation levels, the importance of electronic safety systems increases significantly because human drivers take on fewer supervisory roles or none at all. Level 2 and Level 3 systems are quickly becoming common in mainstream vehicle segments and need ASIL C or ASIL D certification for crucial functions like adaptive cruise control, lane keeping assist, automatic emergency braking, and traffic jam assist. Level 4 and Level 5 autonomous systems operate without human intervention in specific or all conditions, respectively, and require ASIL D certification for nearly all perception, planning, and control functions. McKinsey & Company reports that advanced driver assistance systems are expected to be in over 70% of new vehicles worldwide by 2030, up from about 40% in 2025. This increase will create a huge demand for functional safety MCUs. Each autonomous or ADAS feature needs its own safety-certified compute capability. Vehicles often have multiple safety MCUs tailored for different functions, such as camera processing, radar processing, sensor fusion, path planning, vehicle control, and backup safety monitoring. The architectural complexity of these autonomous systems, which may include primary compute platforms along with redundant backup systems, increases the need for more MCUs per vehicle.
Electric Vehicle Electrification and X-by-Wire Systems
The global shift to electric vehicles is driving significant demand for functional safety microcontrollers in safety-critical powertrain and chassis applications. Electric vehicles use high-voltage battery systems, traction inverters, and electric motors that need advanced electronic control with strong safety measures to avoid dangerous situations like thermal runaway, short circuits, and unintended acceleration or braking. Battery management systems (BMS) for EV high-voltage batteries must use ASIL C or ASIL D functional safety MCUs to track individual cell voltages and temperatures, control contactors and safety interlocks, and ensure safe operation under all conditions. Traction inverter control modulates high-power transistors that switch hundreds of amperes at high voltages and requires functional safety MCUs with precise real-time control and thorough fault detection. The International Energy Agency states that global electric vehicle sales reached 14 million units in 2023, with projections to surpass 40 million by 2030. Each vehicle requires multiple functional safety MCUs for powertrain applications. Beyond electrification, the automotive industry is moving traditional mechanical and hydraulic systems to electronic "X-by-wire" systems, including brake-by-wire, steer-by-wire, and shift-by-wire. These systems eliminate mechanical backup systems and depend entirely on electronic control, necessitating ASIL D functional safety certification. X-by-wire systems require redundant functional safety MCUs with independent power sources and communication paths to maintain safe operation during single-point failures.
Table of contents
15 chapters · 203 sections · 261 pages · click to expandGeographic analysis
Europe
Germany is a leader in the regional market due to its automotive industry, with manufacturers at the forefront of autonomous driving development and advanced safety systems requiring the most sophisticated functional safety MCUs. European automotive OEMs and suppliers have extensive functional safety expertise and dedicated safety engineering teams, fostering continuous improvements in functional safety technology and strong demand for certified MCU solutions.
Asia-Pacific
Fastest growthThe Asia-Pacific region is anticipated to grow at the highest CAGR during the forecast period. This growth is due to the expanding automotive production in China, Japan, and South Korea, which accounts for over 50% of global vehicle manufacturing. China's vast automotive market and push for ADAS and autonomous driving features are significant factors. The Chinese government mandates advanced safety systems, while the country's growing electric vehicle production leads global EV sales. There is also an increase in domestic automotive semiconductor capabilities, with Chinese companies like Horizon Robotics and Black Sesame working on safety MCUs. Rising safety awareness is driving ADAS adoption in emerging markets. China will contribute significantly to regional growth through government policies such as the Made in China 2025 semiconductor initiative and new energy vehicle mandates. The large scale of automotive production creates a substantial addressable market. Domestic autonomous driving programs like Baidu Apollo and others are making rapid advancements, requiring functional safety compute platforms, with strong government support for local semiconductor industries reducing reliance on imported automotive chips. Japan has a solid market presence as its automotive manufacturers (Toyota, Honda, Nissan) increasingly adopt advanced safety systems, and leading semiconductor suppliers (Renesas, Toshiba, Rohm) provide functional safety MCUs. South Korea also plays a role through its automotive manufacturers (Hyundai, Kia) and leadership in the semiconductor industry.
North America
North America represents a significant market, driven by advancements in autonomous driving, including programs from GM Cruise and Ford Argo AI (now dissolved), which require extensive functional safety computing. There is strong ADAS adoption fueled by IIHS and NHTSA safety ratings and insurance incentives. Major automotive semiconductor companies like Texas Instruments, Microchip, and ON Semiconductor play a vital role in the market. The region has a cutting-edge automotive technology development ecosystem in Silicon Valley and Detroit, along with a high-value vehicle market that sees significant uptake of premium safety features. The U.S. market is marked by rapid advancements in autonomous driving technology, especially in California and Arizona, where many test programs are based. There is a strong regulatory focus on safety, with NHTSA investigating functional safety requirements for automated systems. The domestic automotive industry (GM, Ford, Stellantis) is heavily investing in electrification and automation, which requires extensive functional safety MCUs.
Competitive landscape
- Infineon Technologies AG · Germany
- NXP Semiconductors N.V. · Netherlands
- Renesas Electronics Corporation · Japan
- STMicroelectronics N.V. · Switzerland
- Texas Instruments Incorporated (U.S.)
- Microchip Technology Inc. (U.S.)
- Analog Devices Inc. (U.S.)
- ON Semiconductor Corporation (U.S.)
- ROHM Co. Ltd. · Japan
- Toshiba Electronic Devices & Storage Corporation · Japan
- Fujitsu Limited · Japan
- Hitachi Automotive Systems Ltd. · Japan
- Kalray SA · France
- Nordic Semiconductor ASA · Norway
- Telechips Inc. · South Korea
- SiEngine Technology · China
- Horizon Robotics · China
- Black Sesame Technologies · China
- Arm Holdings plc (U.K.)
Frequently asked questions
The functional safety microcontrollers market is expected to grow from USD 4.92 billion in 2026 to USD 14.73 billion by 2036.
Cite this report
Meticulous Research. (2026). Functional Safety Microcontrollers (MCUs) Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MRAUTO - 1041662). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/functional-safety-microcontrollers-market-6345