Hardware Security Module (HSM) Market (2026-2036)
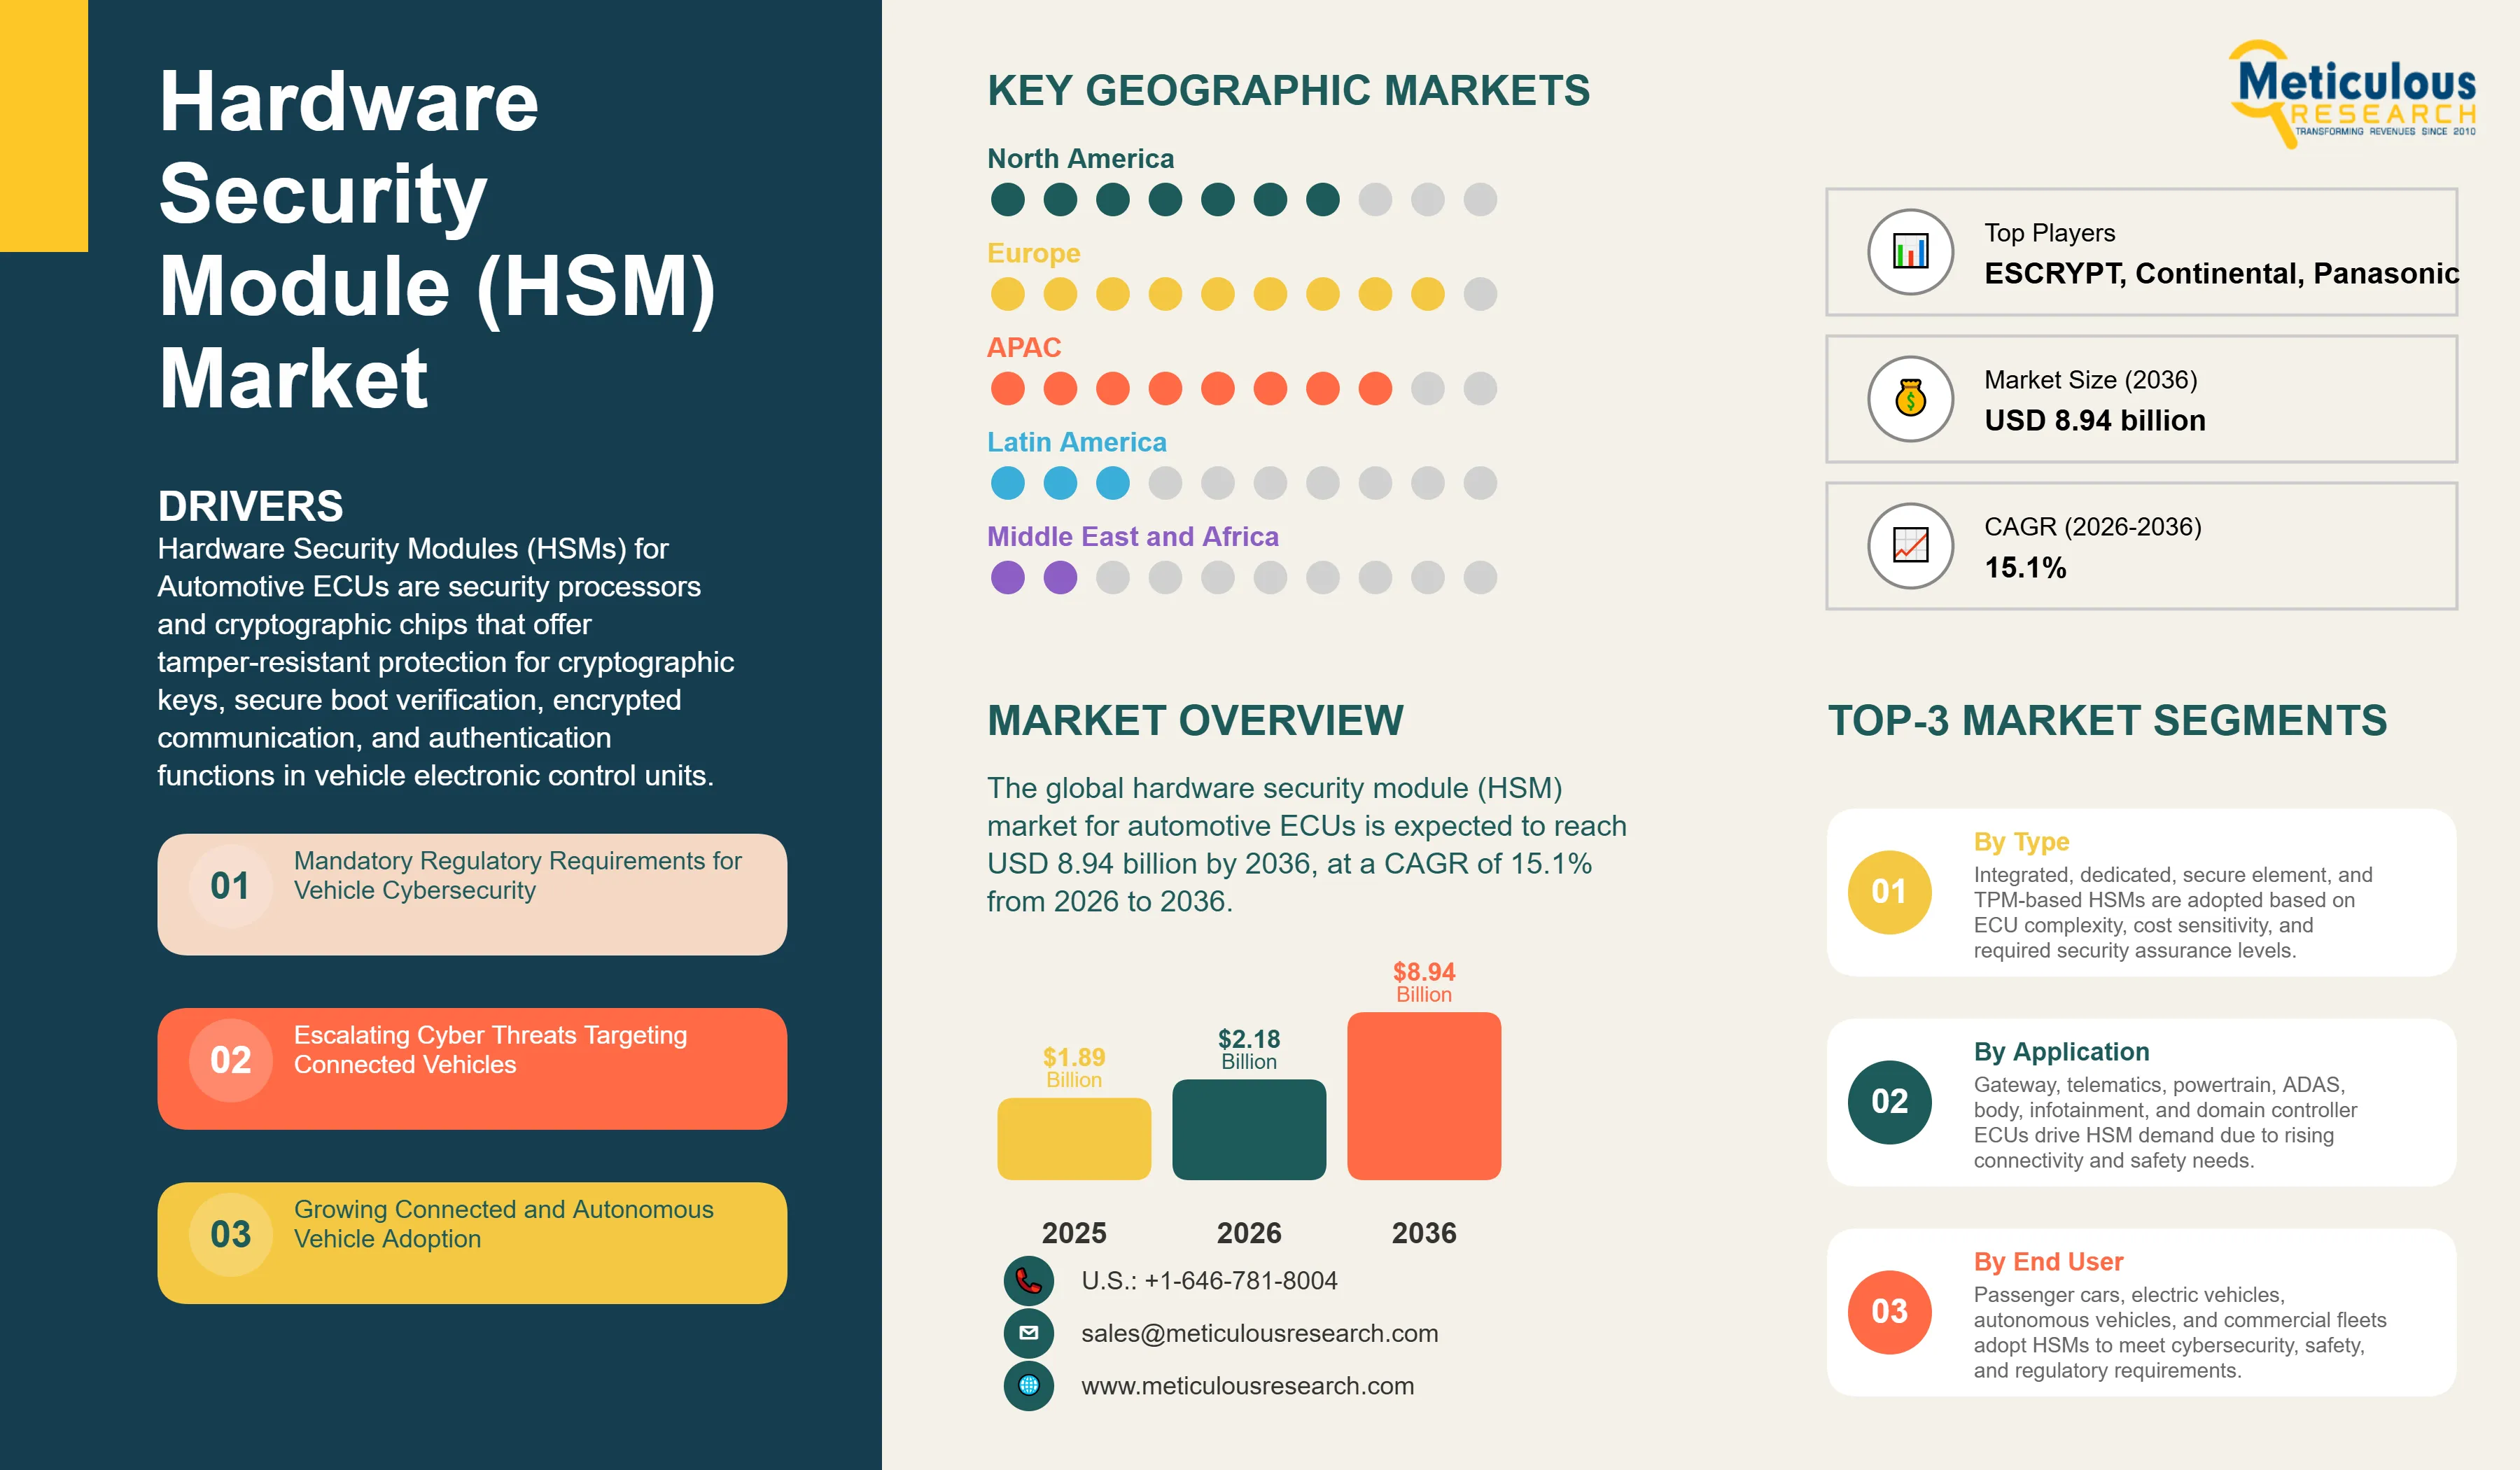
The global hardware security module (HSM) market for automotive ECUs is expected to reach USD 8.94 billion by 2036 from USD 2.18 billion in 2026, at a CAGR of 15.1% from 2026 to 2036.
- Published
- Jan 2026
- Pages
- 272
- Format
- PDF + Excel
- Report ID
- MRAUTO - 1041659
- Base year
- 2025
- 2026 · ESTIMATED
- $2.18B
- 2036
- $8.94B
- CAGR 2026–2036
- 15.1%
2025 baseline · 2026–2036 forecast at 15.1% CAGR · hover a bar for the value
Key highlights
In 2026, Europe is estimated to account for the largest share of the global HSM market for automotive ECUs, driven by stringent UNECE WP.29 cybersecurity regulations requiring comprehensive vehicle security, high premium vehicle concentration, and strong automotive security engineering capabilities.
Asia-Pacific is projected to register the highest CAGR during the forecast period, fueled by massive automotive production volumes, rapidly growing connected and electric vehicle segments requiring enhanced security, and strong regional semiconductor manufacturing ecosystem.
Based on HSM type, the integrated HSM segment is estimated to hold the largest share of the market in 2026, driven by cost-effectiveness, space efficiency in compact ECUs, and sufficient security for most automotive applications.
Based on security level, the automotive-grade security (EVITA Medium/High) segment is estimated to dominate the market in 2026, owing to balanced security capabilities meeting regulatory requirements while maintaining cost feasibility for volume production.
Based on cryptographic algorithms, the symmetric encryption (AES) segment is expected to account for substantial share, driven by high-speed operation, lower computational overhead, and suitability for real-time automotive communication encryption.
Based on ECU application, the gateway and telematics ECU segment is expected to witness significant growth during the forecast period, fueled by critical role in vehicle cybersecurity architecture and external connectivity exposure.
The powertrain and ADAS ECU segment is expected to grow at a significant CAGR during the forecast period, driven by increasing connectivity of safety-critical systems and autonomous driving cybersecurity requirements.
The U.S. HSM market for automotive ECUs is projected to grow at a CAGR of around 14% during the forecast period 2026 to 2036, driven by NHTSA cybersecurity guidelines, increasing connected vehicle adoption, and autonomous vehicle development.
China is expected to lead the Asia-Pacific HSM market for automotive ECUs, driven by massive EV production with extensive connectivity, government intelligent connected vehicle initiatives, domestic semiconductor industry development, and cybersecurity regulations.
In 2026, Germany is projected to account for the largest share of the European HSM market for automotive ECUs, driven by premium automakers BMW, Mercedes-Benz, Audi, and Porsche implementing comprehensive security architectures and early UNECE WP.29 compliance.
Report summary
| Particulars | Details |
|---|---|
| Market Size Value in 2026 | USD 2.18 Billion |
| Revenue Forecast in 2036 | USD 8.94 Billion |
| Growth Rate | CAGR of 15.1% from 2026 to 2036 |
| Format | PDF, Excel & Cloud Portal · 272 pages |
| Base Year for Estimation | 2025 |
| Historical Data | 2021–2025 |
| Forecast Period | 2026–2036 |
| Quantitative Units | Revenue in USD Billion and CAGR from 2026 to 2036 |
| Report Coverage | Revenue forecast, company ranking, competitive landscape, growth factors, and trends |
| Segments Covered | HSM Type, Security Level, Cryptographic Algorithms, ECU Application, Vehicle Architecture, OEM Adoption, Region |
| Regional Scope | North America, Europe, Asia-Pacific, Latin America, Middle East & Africa |
| Countries Covered | U.S., Canada, Germany, U.K., France, Italy, Spain, Sweden, China, Japan, South Korea, India, Australia, Brazil, Mexico, Saudi Arabia, UAE, South Africa |
| Key Companies Profiled | Infineon Technologies AG, NXP Semiconductors N.V., STMicroelectronics N.V., Renesas Electronics Corporation, Texas Instruments Inc., Microchip Technology Inc., Qualcomm Technologies Inc., Samsung Electronics Co. Ltd., ESCRYPT GmbH (ETAS), Thales Group, INSIDE Secure (Viaccess-Orca), Rambus Inc., Maxim Integrated (Analog Devices), Cypress Semiconductor (Infineon), Gemalto (Thales), Continental AG, Robert Bosch GmbH, Aptiv PLC, Denso Corporation, Panasonic Automotive Systems Co. Ltd. |
Report overview
Segments covered: hsm type, security level, cryptographic algorithm, ecu application, vehicle architecture, oem adoption.
Hardware Security Modules (HSMs) for Automotive ECUs are security processors and cryptographic chips that offer tamper-resistant protection for cryptographic keys, secure boot verification, encrypted communication, and authentication functions in vehicle electronic control units. Their goal is to shield vehicles from cyber attacks, prevent unauthorized software changes, secure vehicle-to-everything (V2X) communications, and ensure data integrity across connected vehicle systems. These hardened modules use technologies like secure cryptographic co-processors, tamper-detection circuits, true random number generators (TRNG), secure key storage with physical protection, and hardware support for encryption and decryption operations. HSMs can secure boot processes to block malware injection, authenticate ECU software and over-the-air updates, safeguard cryptographic keys for secure communications, enable secure vehicle access and immobilization, and provide a hardware root of trust for vehicle security systems. The system meets automotive security standards (ISO/SAE 21434, UNECE WP.29), speeds up cryptographic tasks without straining main processors, defends against physical and side-channel attacks, and creates trusted execution environments. This helps automakers fulfill regulatory cybersecurity requirements, protect vehicles from more complex cyber threats, secure connected and autonomous vehicle systems, and maintain consumer trust in vehicle safety and data privacy.
Hardware Security Modules for Automotive ECUs are essential for securing modern connected, electric, and autonomous vehicles against growing cybersecurity threats. As vehicles evolve from simple mechanical systems to complex software-defined computers with extensive connections to cloud services, smartphones, infrastructure, and other vehicles, the potential for cyber threats increases significantly. Traditional software-based security methods fall short against determined attackers. These attackers can exploit weaknesses, extract cryptographic keys from memory, inject harmful code, or alter critical vehicle functions. HSMs solve these issues by offering hardware-based security. They isolate and protect cryptographic operations, keys, and sensitive data within tamper-resistant silicon, creating trusted points for vehicle security architectures that software alone cannot secure.
Several important trends are changing the automotive HSM market. These trends include new regulatory requirements for vehicle cybersecurity (UNECE WP.29, ISO/SAE 21434) pushing for widespread HSM adoption. There is a shift from protecting individual ECUs to building complete security architectures with layered HSM deployment. Rapid progress in quantum-resistant cryptographic algorithms is preparing for post-quantum security. Additionally, the integration of HSMs with secure over-the-air update systems is vital for managing connected vehicle lifecycles. The combination of increasing cyber threat sophistication targeting connected vehicles, regulatory demands for clear cybersecurity measures, expanding attack surfaces due to greater vehicle connectivity, and advancements in semiconductor technology for budget-friendly HSM integration has turned HSMs from optional features into necessary parts across all vehicle types and ECU categories.
The automotive HSM market is quickly moving toward complete, layered security architectures where multiple HSMs work together across vehicle networks to provide robust protection. Modern vehicle security now extends far beyond single HSM chips in individual ECUs. It includes sophisticated security ecosystems with master HSMs in central gateways managing security domains, distributed HSMs in domain controllers and critical ECUs providing targeted protection, hierarchical key management systems for secure key distribution, and certificate-based authentication frameworks for verifying ECUs. This shift from isolated security measures to integrated security architectures marks a significant change in the approach to automotive cybersecurity and HSM deployment.
Cryptographic technology and security standards are progressing rapidly. This advancement allows HSMs to combat emerging threats while meeting stricter regulatory and industry standards. Modern automotive HSMs can implement multiple cryptographic algorithms simultaneously. These include symmetric encryption (AES-128/256), asymmetric encryption (RSA, ECC), hash functions (SHA-256/384), and message authentication codes (HMAC), along with support for quantum-resistant algorithms (lattice-based, hash-based signatures) in preparation for post-quantum cryptography. They comply with automotive security standards (EVITA, SHE, HSM+) and achieve Common Criteria EAL certification for recognized security assurance. State-of-the-art features include hardware security extensions like physical unclonable functions (PUF) for unique device identification, true random number generators for reliable cryptographic randomness, and tamper detection circuits that guard against physical attacks.
The integration of HSMs with over-the-air (OTA) update systems and software-defined vehicle architectures is creating new demands and opportunities. Modern HSMs must verify the authenticity of software updates securely, prevent downgrade attacks through rollback protection, support A/B update methods with secure boot verification, coordinate multi-ECU update efforts while keeping security intact, and facilitate secure software supply chain validation. This convergence positions HSMs as critical components in software-defined vehicles that require regular updates throughout their lifecycles while maintaining security.
Report infographic
Market dynamics
4 factors across 2 forcesMandatory Regulatory Requirements for Vehicle Cybersecurity
Global regulatory initiatives require comprehensive vehicle cybersecurity measures, pushing for universal HSM adoption across all vehicle segments and regions. The UNECE WP.29 regulations, effective from July 2024 in Europe, Japan, Korea, and other markets, demand that automakers show comprehensive cybersecurity management systems throughout the vehicle's lifecycle, including design, production, and post-production phases. These rules specifically require protection against unauthorized access to vehicle systems, secure software updates, monitoring for cyber attacks, and incident response capabilities, all needing HSM-based security implementations. The EU's proposed Cyber Resilience Act extends these requirements to aftermarket components and connected services. Similar efforts are appearing worldwide, including China's automotive cybersecurity standards, US NHTSA cybersecurity best practices, and international coordination. To comply with regulations, automakers must adopt security-by-design principles, using HSMs for foundational hardware security. Failure to comply leads to type approval denial, blocking vehicle sales, which creates unavoidable market drivers that are independent of cost. The regulatory landscape ensures that HSM deployment will become standard across all vehicle types, markets, and price segments.
Escalating Cyber Threats Targeting Connected Vehicles
The growing complexity and frequency of cyber attacks on automotive systems create urgent demand for strong hardware-based security. Security researchers and malicious actors have shown many vehicle vulnerabilities, including remote vehicle control via telematics systems, CAN bus manipulation that affects braking and steering, key fob relay attacks that enable theft, ransomware targeting infotainment systems, and OTA update manipulation that injects malicious code. High-profile automotive cyber incidents and recalls have caused significant financial and reputational harm to affected automakers. The increased connectivity of vehicles through cellular telematics, Wi-Fi, Bluetooth, V2X communications, and cloud services greatly expands potential attack surfaces. Software-only security measures are inadequate as attackers create advanced techniques to extract keys from memory, exploit firmware vulnerabilities, and conduct side-channel attacks. HSMs provide essential protection by isolating cryptographic operations in tamper-resistant hardware, securely storing keys in physically protected memory, implementing countermeasures in silicon, and establishing hardware roots of trust that software-based attacks cannot compromise. As cyber threats continue to evolve and vehicle connectivity increases, HSM-based protection becomes necessary rather than optional.
Table of contents
15 chapters · 177 sections · 272 pages · click to expandGeographic analysis
Europe
Largest shareIn 2026, Europe is expected to have the largest share of the global automotive HSM market. This is due to strict UNECE WP.29 cybersecurity regulations that require comprehensive vehicle security, a high concentration of premium and luxury vehicles needing advanced security, strong automotive security engineering expertise, especially in Germany, an early market for connected vehicle technologies that need security, and an established automotive semiconductor supplier ecosystem. Germany leads the European market with automakers like BMW, Mercedes-Benz, Audi, Porsche, and the Volkswagen Group implementing extensive security systems that meet and exceed regulatory needs. European tier-one suppliers such as Continental, Bosch, ZF, and Aptiv are at the forefront of developing security-by-design ECUs. Semiconductor suppliers like Infineon, STMicroelectronics, and NXP maintain a strong presence in the European automotive HSM market. The regulatory-driven focus on security and emphasis on premium vehicles ensure that Europe remains a leader in this market.
Asia-Pacific
The Asia-Pacific region is expected to grow at the highest rate during the forecast period. This impressive growth is fueled by large automotive production volumes mainly in China, Japan, and South Korea, rapidly expanding connected and electric vehicle segments that include significant connectivity needing security, and a strong regional semiconductor manufacturing ecosystem that supports cost-effective HSM production. Increasing Chinese automotive cybersecurity regulations are promoting domestic adoption, and government initiatives for intelligent connected vehicles are advancing automotive technologies. China, in particular, will drive regional growth as automakers implement connectivity in high volumes. Domestic semiconductor firms such as HiSilicon and SMIC are also developing automotive security solutions in response to regulatory frameworks that require cybersecurity measures. Japan and South Korea contribute to this growth with their advanced automotive industries and leading semiconductor suppliers like Renesas, Toshiba, Panasonic, Samsung, and SK Hynix.
North America
North America has a significant market driven by the rising adoption of connected vehicles across mainstream segments. This growth is supported by NHTSA cybersecurity guidelines and industry best practices, development of autonomous vehicles requiring high security levels, a strong presence of automotive semiconductor design firms, and heightened cybersecurity awareness from publicized vehicle hacking incidents. The U.S. market particularly values security innovation and is open to adopting advanced technologies in premium vehicles.
Competitive landscape
- Infineon Technologies AG · Germany
- NXP Semiconductors N.V. · Netherlands
- STMicroelectronics N.V. · Switzerland
- Renesas Electronics Corporation · Japan
- Texas Instruments Inc. (U.S.)
- Microchip Technology Inc. (U.S.)
- Qualcomm Technologies Inc. (U.S.)
- Samsung Electronics Co. Ltd. · South Korea
- ESCRYPT GmbH (ETAS) · Germany
- Thales Group · France
- INSIDE Secure (Viaccess-Orca) · France
- Rambus Inc. (U.S.)
- Maxim Integrated (Analog Devices) (U.S.)
- Cypress Semiconductor (Infineon) (U.S.)
- Gemalto (Thales) · France/Netherlands
- Continental AG · Germany
- Robert Bosch GmbH · Germany
- Aptiv PLC · Ireland
- Denso Corporation · Japan
- Panasonic Automotive Systems Co. Ltd. · Japan
Frequently asked questions
The hardware security module market for automotive ECUs is expected to grow from USD 2.18 billion in 2026 to USD 8.94 billion by 2036.
Cite this report
Meticulous Research. (2026). Hardware Security Module (HSM) Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MRAUTO - 1041659). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/hardware-security-module-market-6342