Secure Boot & Over-the-Air (OTA) Update Firmware Market (2026-2036)
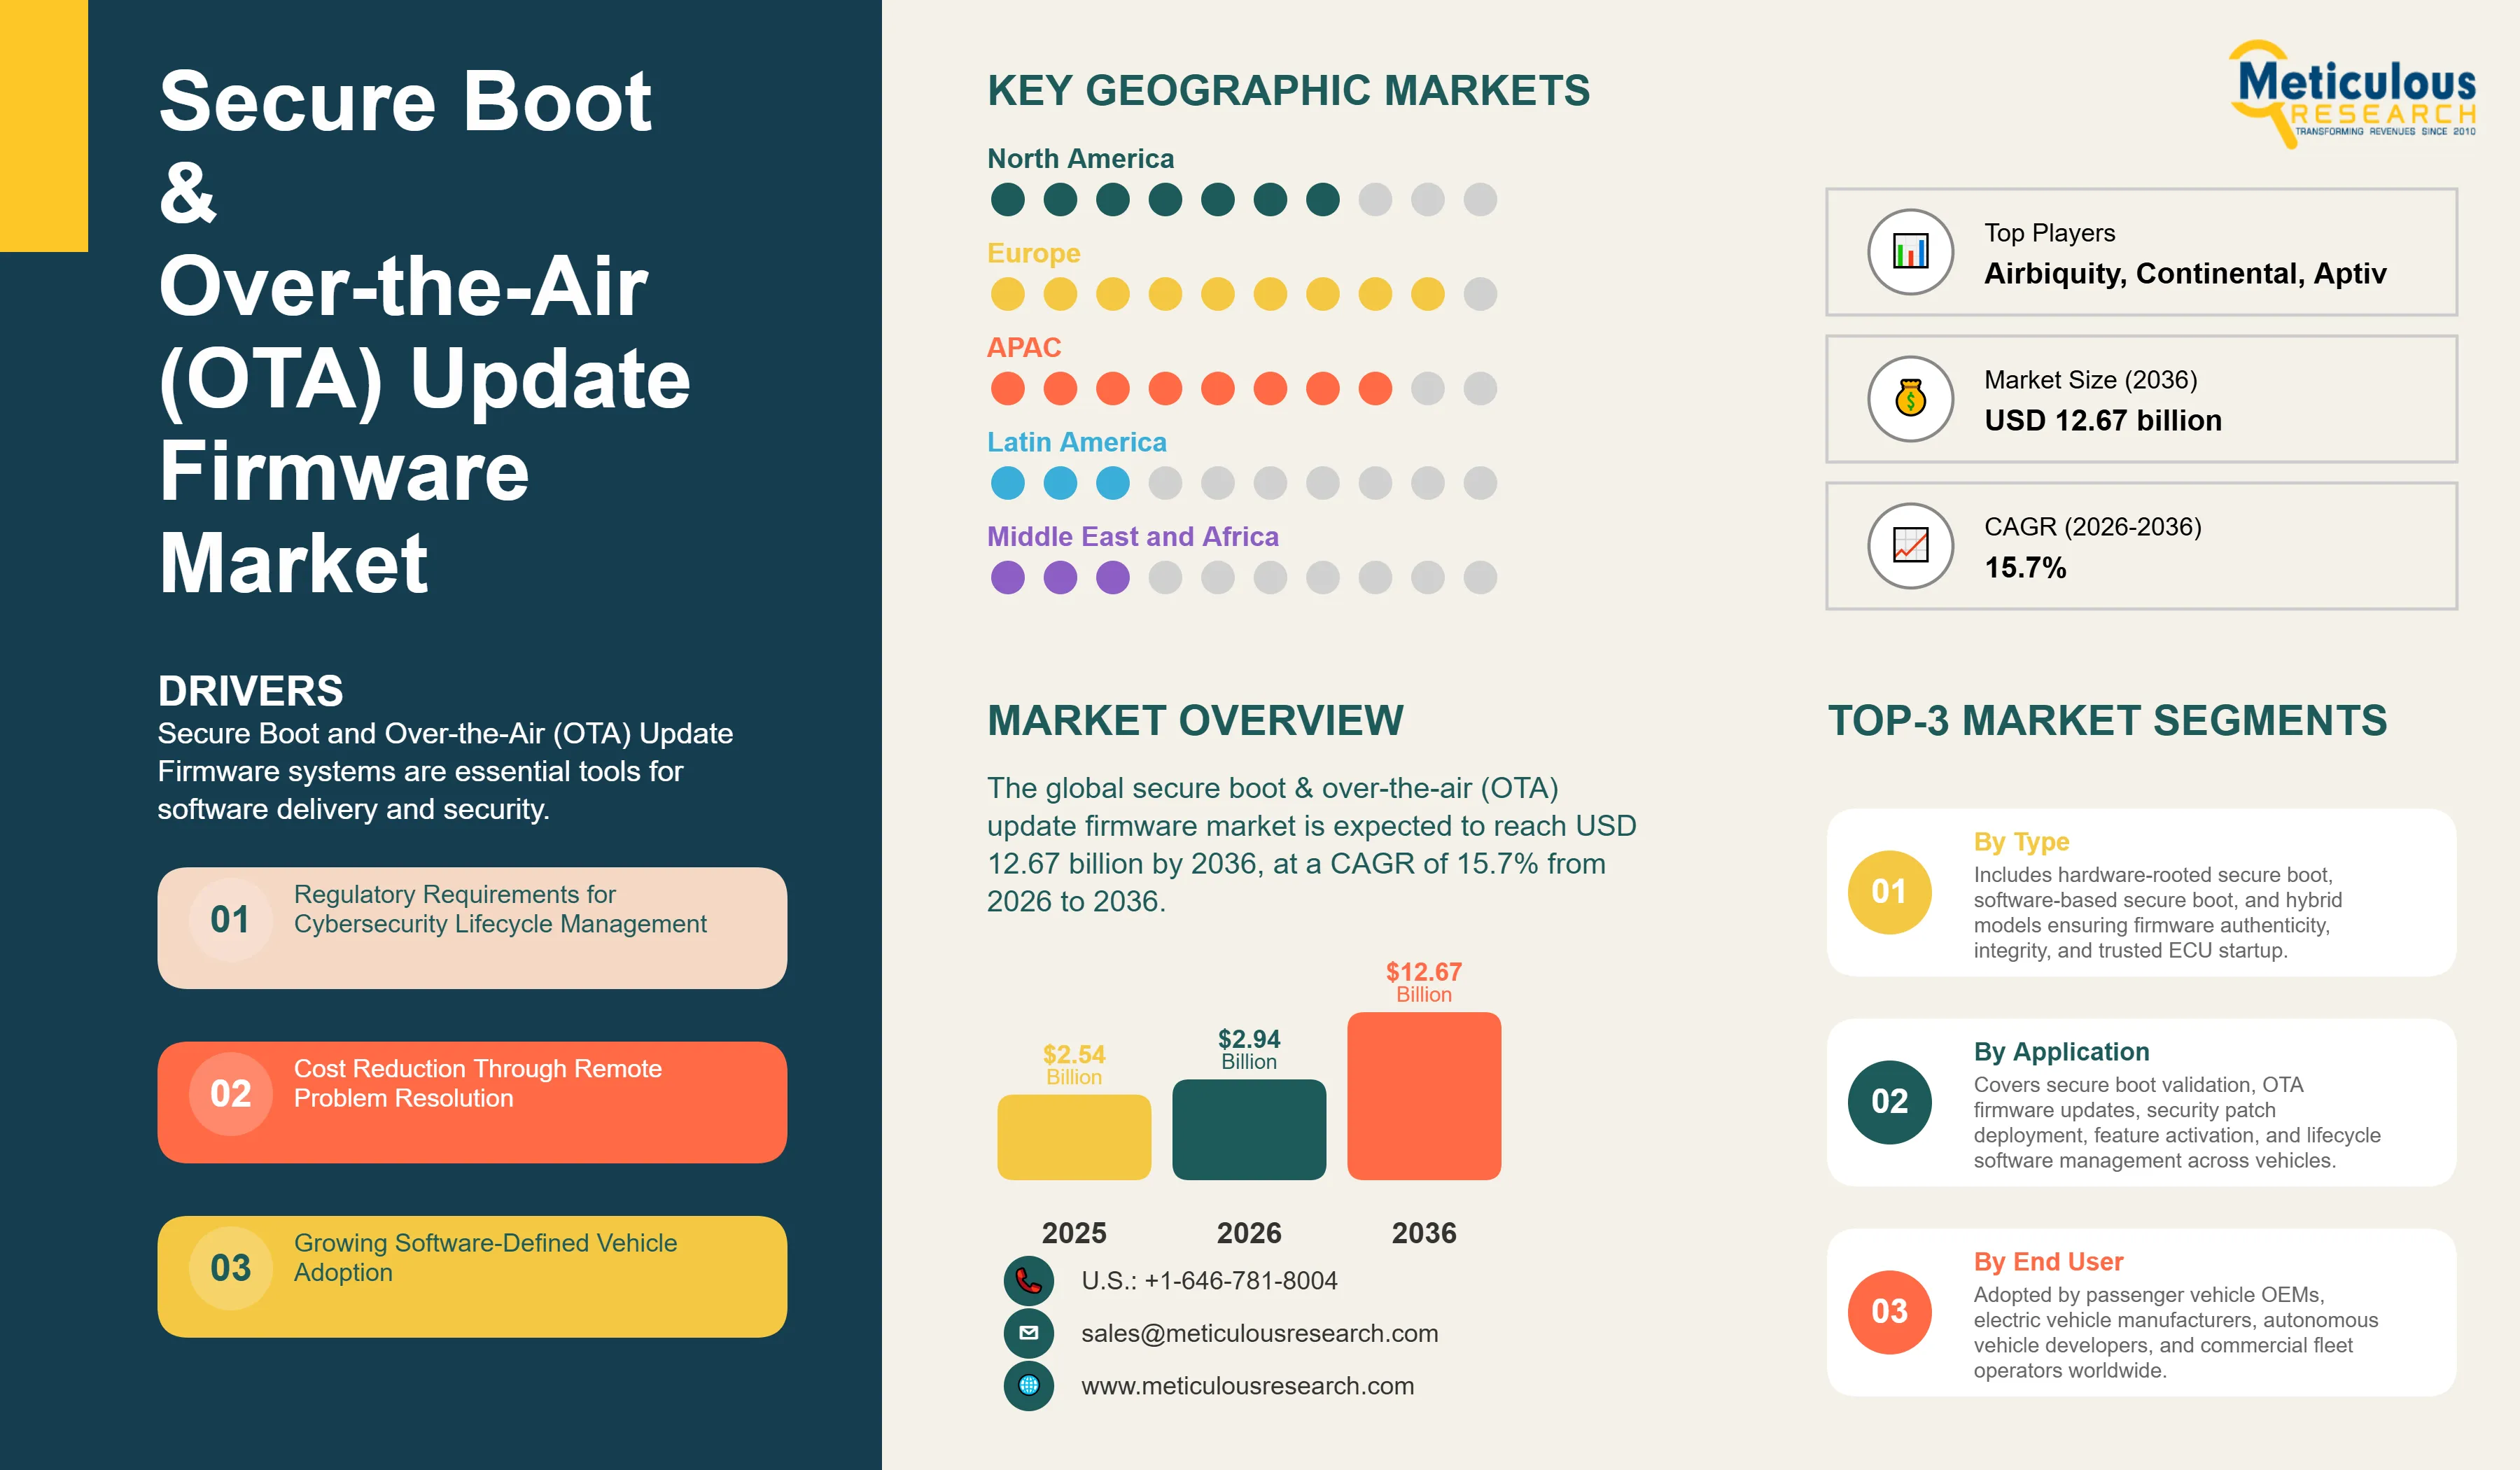
The global secure boot & over-the-air (OTA) update firmware market is expected to reach USD 12.67 billion by 2036 from USD 2.94 billion in 2026, at a CAGR of 15.7% from 2026 to 2036.
- Published
- Jan 2026
- Pages
- 268
- Format
- PDF + Excel
- Report ID
- MRAUTO - 1041660
- Base year
- 2025
- 2026 · ESTIMATED
- $2.94B
- 2036
- $12.67B
- CAGR 2026–2036
- 15.7%
2025 baseline · 2026–2036 forecast at 15.7% CAGR · hover a bar for the value
Key highlights
In 2026, Europe is estimated to account for the largest share of the global secure boot & OTA update firmware market, driven by UNECE WP.29 regulations mandating secure software update capabilities, premium vehicle concentration with advanced connected services, and early OTA adoption by luxury automakers.
Asia-Pacific is projected to register the highest CAGR during the forecast period, fueled by massive electric vehicle production with integrated OTA capabilities, Chinese automakers' aggressive OTA deployment as standard features, and strong regional connectivity infrastructure.
Based on secure boot implementation, the hardware-rooted secure boot segment is estimated to hold the largest share of the market in 2026, driven by superior security through HSM/TPM integration and regulatory preference for hardware-based roots-of-trust.
Based on OTA update mechanism, the full firmware update segment is estimated to dominate the market in 2026, owing to comprehensive update capabilities enabling complete ECU software replacement for major changes.
Based on cryptographic protection, the PKI-based code signing segment is expected to account for substantial share, driven by robust authentication through public key infrastructure and multi-party signing workflows.
Based on ECU type, the telematics and gateway ECU segment is expected to witness significant growth during the forecast period, fueled by critical role in OTA update orchestration and external connectivity management.
The ADAS and autonomous driving ECU segment is expected to grow at a significant CAGR during the forecast period, driven by rapid algorithm improvements requiring frequent updates and safety-critical nature demanding secure update mechanisms.
The U.S. secure boot & OTA update firmware market is projected to grow at a CAGR of around 15% during the forecast period 2026 to 2036, driven by Tesla's pioneering OTA adoption, traditional automakers' accelerated deployment, and NHTSA encouragement of OTA security patching capabilities.
China is expected to lead the Asia-Pacific secure boot & OTA update firmware market, driven by domestic EV manufacturers implementing sophisticated OTA systems, government intelligent connected vehicle policies, and consumer expectation for smartphone-like update experiences.
In 2026, Germany is projected to account for the largest share of the European secure boot & OTA update firmware market, driven by premium automakers BMW, Mercedes-Benz, Audi, and Porsche deploying comprehensive OTA capabilities across vehicle lines.
Report summary
| Particulars | Details |
|---|---|
| Market Size Value in 2026 | USD 2.94 Billion |
| Revenue Forecast in 2036 | USD 12.67 Billion |
| Growth Rate | CAGR of 15.7% from 2026 to 2036 |
| Format | PDF, Excel & Cloud Portal · 268 pages |
| Base Year for Estimation | 2025 |
| Historical Data | 2021–2025 |
| Forecast Period | 2026–2036 |
| Quantitative Units | Revenue in USD Billion and CAGR from 2026 to 2036 |
| Report Coverage | Revenue forecast, company ranking, competitive landscape, growth factors, and trends |
| Segments Covered | Secure Boot Implementation, OTA Update Mechanism, Cryptographic Protection, Update Scope, ECU Type, Delivery Method, Vehicle Segment, Region |
| Regional Scope | North America, Europe, Asia-Pacific, Latin America, Middle East & Africa |
| Countries Covered | U.S., Canada, Germany, U.K., France, Italy, Spain, Sweden, China, Japan, South Korea, India, Australia, Brazil, Mexico, Saudi Arabia, UAE, South Africa |
| Key Companies Profiled | Airbiquity Inc., Harman International (Samsung Electronics), Continental AG, Robert Bosch GmbH, Aptiv PLC, Denso Corporation, Excelfore Corporation, Wind River Systems (TPG Capital), BlackBerry Limited (QNX, Jarvis), Red Bend Software (Harman), ABUP Inc., Thunder Software Technology Co. Ltd., Movement (Joyson Electronics), Carota Technology, ATS Advanced Telematic Systems GmbH (HERE Technologies), ESCRYPT GmbH (ETAS/Bosch), Infineon Technologies AG, NXP Semiconductors N.V., Renesas Electronics Corporation, Vector Informatik GmbH |
Report overview
Segments covered: secure boot implementation, ota update mechanism, cryptographic protection, ecu type.
Secure Boot and Over-the-Air (OTA) Update Firmware systems are essential tools for software delivery and security. They allow for remote wireless updating of vehicle electronic control unit (ECU) firmware, ensuring authenticity, integrity, and security during the process. The goal is to improve vehicles continuously with software updates, fix bugs and security issues remotely, add new features without needing dealer visits, and protect vehicles from harmful software.
These systems use complex technologies such as cryptographic signature verification, secure boot chains of trust, differential update methods, rollback protection, multi-ECU update coordination, and fail-safe recovery processes. Secure boot systems check firmware authenticity before running it, using digital signatures and hardware roots of trust. OTA update methods manage the entire vehicle software lifecycle, including creating update packages, securely delivering them over cellular or Wi-Fi networks, coordinating multi-ECU installations, verifying updates, and recovering from failures.
The systems offer automakers the chance to continually improve, cut warranty costs through remote fixes, monetize features via software subscriptions, and boost customer satisfaction by reducing dealer visits. They also help protect vehicles through fast deployment of security patches. This supports automakers in moving to software-defined vehicle business models, maintaining cybersecurity throughout vehicle lifecycles, quickly responding to identified vulnerabilities, and providing ongoing value to customers through new features and improvements.
Secure Boot and Over-the-Air Update Firmware systems are changing the game for software-defined vehicles and modern automotive business models. In the past, automotive software development used strict waterfall processes. Once software went into production, it was locked in. This made recalls expensive and added features impossible. This approach does not meet today’s consumer expectations, which have been shaped by smartphones that receive regular updates and improvements. OTA update technology allows automotive software to undergo similar continuous development. Secure boot ensures that only verified and authorized software runs on vehicle ECUs. Together, these technologies lay the groundwork for software-defined vehicles, where functionality, performance, and features improve through software rather than needing hardware changes.
Several key trends are changing the secure boot and OTA update market. These include moving from isolated ECU updates to full vehicle-wide update campaigns that coordinate dozens of ECUs. There’s a rapid advancement in differential update algorithms that reduce data transmission needs. AI-driven update scheduling is optimizing the timing based on connectivity and usage patterns. Expansion is happening from luxury vehicles to mainstream models due to electric vehicle architectures and competition. The mix of security patch regulations, automakers seeing OTA as a way to stand out and cut costs, and consumer demand for ongoing improvements has sped up adoption. What started as premium features is now becoming standard across different segments.
The secure boot and OTA update market is evolving toward software lifecycle management platforms that allow continuous vehicle improvement throughout ownership. Modern implementations offer more than just firmware updates. They provide advanced systems, including cloud-based update package creation and testing, AI-driven campaign management for optimizing deployment timing and sequences, comprehensive vehicle software inventories tracking every ECU firmware version, automated compatibility checks to avoid problematic updates, A/B update methods for safe rollbacks from failed updates, delta compression that reduces update data sizes by 80-95%, and detailed analytics that provide feedback on success rates and issues. The shift from isolated updates to integrated software lifecycle platforms marks a significant change in automotive software management.
Security systems and cryptographic protections are progressing quickly to meet changing threats and regulations. Modern systems use several security layers. These include hardware-rooted secure boot with HSM/TPM chips that create chains of trust, multi-party code signing requiring several authorized signers to prevent unauthorized updates, certificate-based authentication that validates update package sources, encrypted transmissions to guard against interception and tampering, secure storage for update packages to prevent local changes, version monotonicity to stop rollbacks to outdated firmware, and thorough audit logging to track all update activities. The adoption of post-quantum cryptographic algorithms prepares systems for future threats from quantum computing.
The merging of OTA update capabilities with the development of autonomous vehicles brings new requirements and opportunities. Autonomous vehicles need frequent algorithm updates that incorporate better perception models, updated HD maps to reflect infrastructure changes, improved decision-making logic from fleet learning, and quick security patches for identified vulnerabilities. The safety-critical nature of autonomous driving software requires strict validation and safe update processes. These include thorough pre-deployment testing, phased rollout strategies for controlled deployment, real-time monitoring to catch update-related issues, and reliable rollback features to restore previous working software.
Report infographic
Market dynamics
4 factors across 2 forcesRegulatory Requirements for Cybersecurity Lifecycle Management
Global automotive cybersecurity regulations increasingly require over-the-air (OTA) update capabilities as vital vehicle security features. UNECE WP.29 regulations ask automakers to show they can manage cybersecurity throughout the vehicle's lifecycle. This includes detecting vulnerabilities, deploying security updates, and keeping security measures as threats change. These regulations understand that cybersecurity is dynamic. Vulnerabilities found after production need quick patching, and threats evolve continuously. OTA update capability is the only practical way to deal with security issues post-production without costly recalls. ISO/SAE 21434 automotive cybersecurity standards also stress that managing software updates is a key security measure. Regulatory frameworks now expect secure boot as a basic security control to stop unauthorized software from running. Compliance requires clear update capabilities, which include secure delivery, authentication, installation, and verification. Automakers that lack OTA update capabilities may face challenges with type approval and could encounter market access restrictions. This regulatory demand ensures that OTA deployment will become standard across vehicle types and markets, regardless of other business concerns.
Cost Reduction Through Remote Problem Resolution
OTA update capabilities offer significant cost savings by allowing remote resolution of software issues that would otherwise need dealer visits or recalls. Traditional automotive recalls for software problems involve huge costs. These costs include dealer labor for vehicle inspections, customer inconvenience, loaner vehicle expenses, notifying affected customers, potential liability from unresolved issues, and reputational harm from public recalls. Software-related recalls are increasingly common as vehicle software becomes more complex, with major automakers recalling millions of vehicles for software fixes. OTA updates cut most recall costs by applying fixes remotely. Customers receive notifications, updates install automatically or with simple confirmation, fixes occur without dealer involvement, and resolution happens quickly across the affected fleet. Cost savings can be substantial, with estimates indicating that OTA deployment saves $50 to $200 per vehicle compared to dealer-based software updates. For large-scale software updates impacting millions of vehicles, savings can reach hundreds of millions of dollars. Beyond recalls, OTA enables remote diagnosis and repair of customer complaints, reducing unnecessary dealer visits and improving first-time fix rates. These operational cost benefits provide strong reasons for investing in OTA, even before considering revenue opportunities.
Table of contents
16 chapters · 188 sections · 268 pages · click to expandGeographic analysis
Europe
Largest shareIn 2026, Europe is expected to have the largest share of the global secure boot and OTA update firmware market. European leadership comes from UNECE WP.29 regulations that require secure software update capabilities, a high concentration of premium vehicles with advanced connected services, early OTA adoption by companies like Mercedes-Benz (MBUX), BMW (iDrive), and Audi (MMI), strong automotive software engineering skills, and established expertise in automotive cybersecurity. German automakers have led European OTA deployment, with Mercedes-Benz providing extensive OTA updates across the E-Class and S-Class ranges. BMW offers OTA for iDrive and vehicle systems, while the Volkswagen Group implements OTA across multiple brands using E3 1.2 electrical architecture. European implementations focus on security and privacy compliance with GDPR, utilizing privacy-preserving architectures and providing thorough user consent mechanisms.
Asia-Pacific
Fastest growthAsia-Pacific is projected to grow at the fastest rate during the forecast period due to the aggressive OTA deployment by Chinese EV manufacturers. Companies like NIO, XPeng, Li Auto, BYD, and others implement advanced OTA systems as standard features even in mid-priced vehicles. Their update frequency and scope often surpass those of Western automakers. Chinese implementations benefit from strong domestic cellular connectivity, consumer expectations influenced by smartphones, and integrated digital ecosystems that link vehicles with mobile apps and services. Government policies on intelligent connected vehicles promote OTA capabilities as key characteristics of intelligent vehicles. Japanese automakers, including Toyota, Honda, and Nissan, are also speeding up OTA deployment in response to competitive pressures. South Korean manufacturers Hyundai and Kia provide extensive OTA across their Hyundai Motor Group brands.
North America
North America represents a significant market, driven by Tesla's pioneering OTA adoption that sets consumer expectations. Traditional automakers are accelerating their own deployment due to competition from Tesla and Chinese manufacturers. GM's Ultifi platform supports comprehensive OTA updates, while Ford offers Power-Up updates. Strong connectivity infrastructure also supports large update downloads. American consumers especially value continuous improvement and new features through OTA updates.
Competitive landscape
- Airbiquity Inc. (U.S.)
- Harman International (Samsung Electronics) (South Korea/U.S.)
- Continental AG · Germany
- Robert Bosch GmbH · Germany
- Aptiv PLC · Ireland
- Denso Corporation · Japan
- Excelfore Corporation (U.S.)
- Wind River Systems (TPG Capital) (U.S.)
- BlackBerry Limited (QNX, Jarvis) · Canada
- Red Bend Software (Harman) (Israel/U.S.)
- ABUP Inc. · China
- Thunder Software Technology Co. Ltd. · China
- Movement (Joyson Electronics) · China
- Carota Technology · China
- ATS Advanced Telematic Systems GmbH (HERE Technologies) · Germany
- ESCRYPT GmbH (ETAS/Bosch) · Germany
- Infineon Technologies AG · Germany
- NXP Semiconductors N.V. · Netherlands
- Renesas Electronics Corporation · Japan
- Vector Informatik GmbH · Germany
Frequently asked questions
The secure boot & over-the-air (OTA) update firmware market is expected to grow from USD 2.94 billion in 2026 to USD 12.67 billion by 2036.
Cite this report
Meticulous Research. (2026). Secure Boot & Over-the-Air (OTA) Update Firmware Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MRAUTO - 1041660). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/secure-boot-and-over-the-air-update-firmware-market-6343