Automotive Secure Element (eSE) Market (2026-2036)
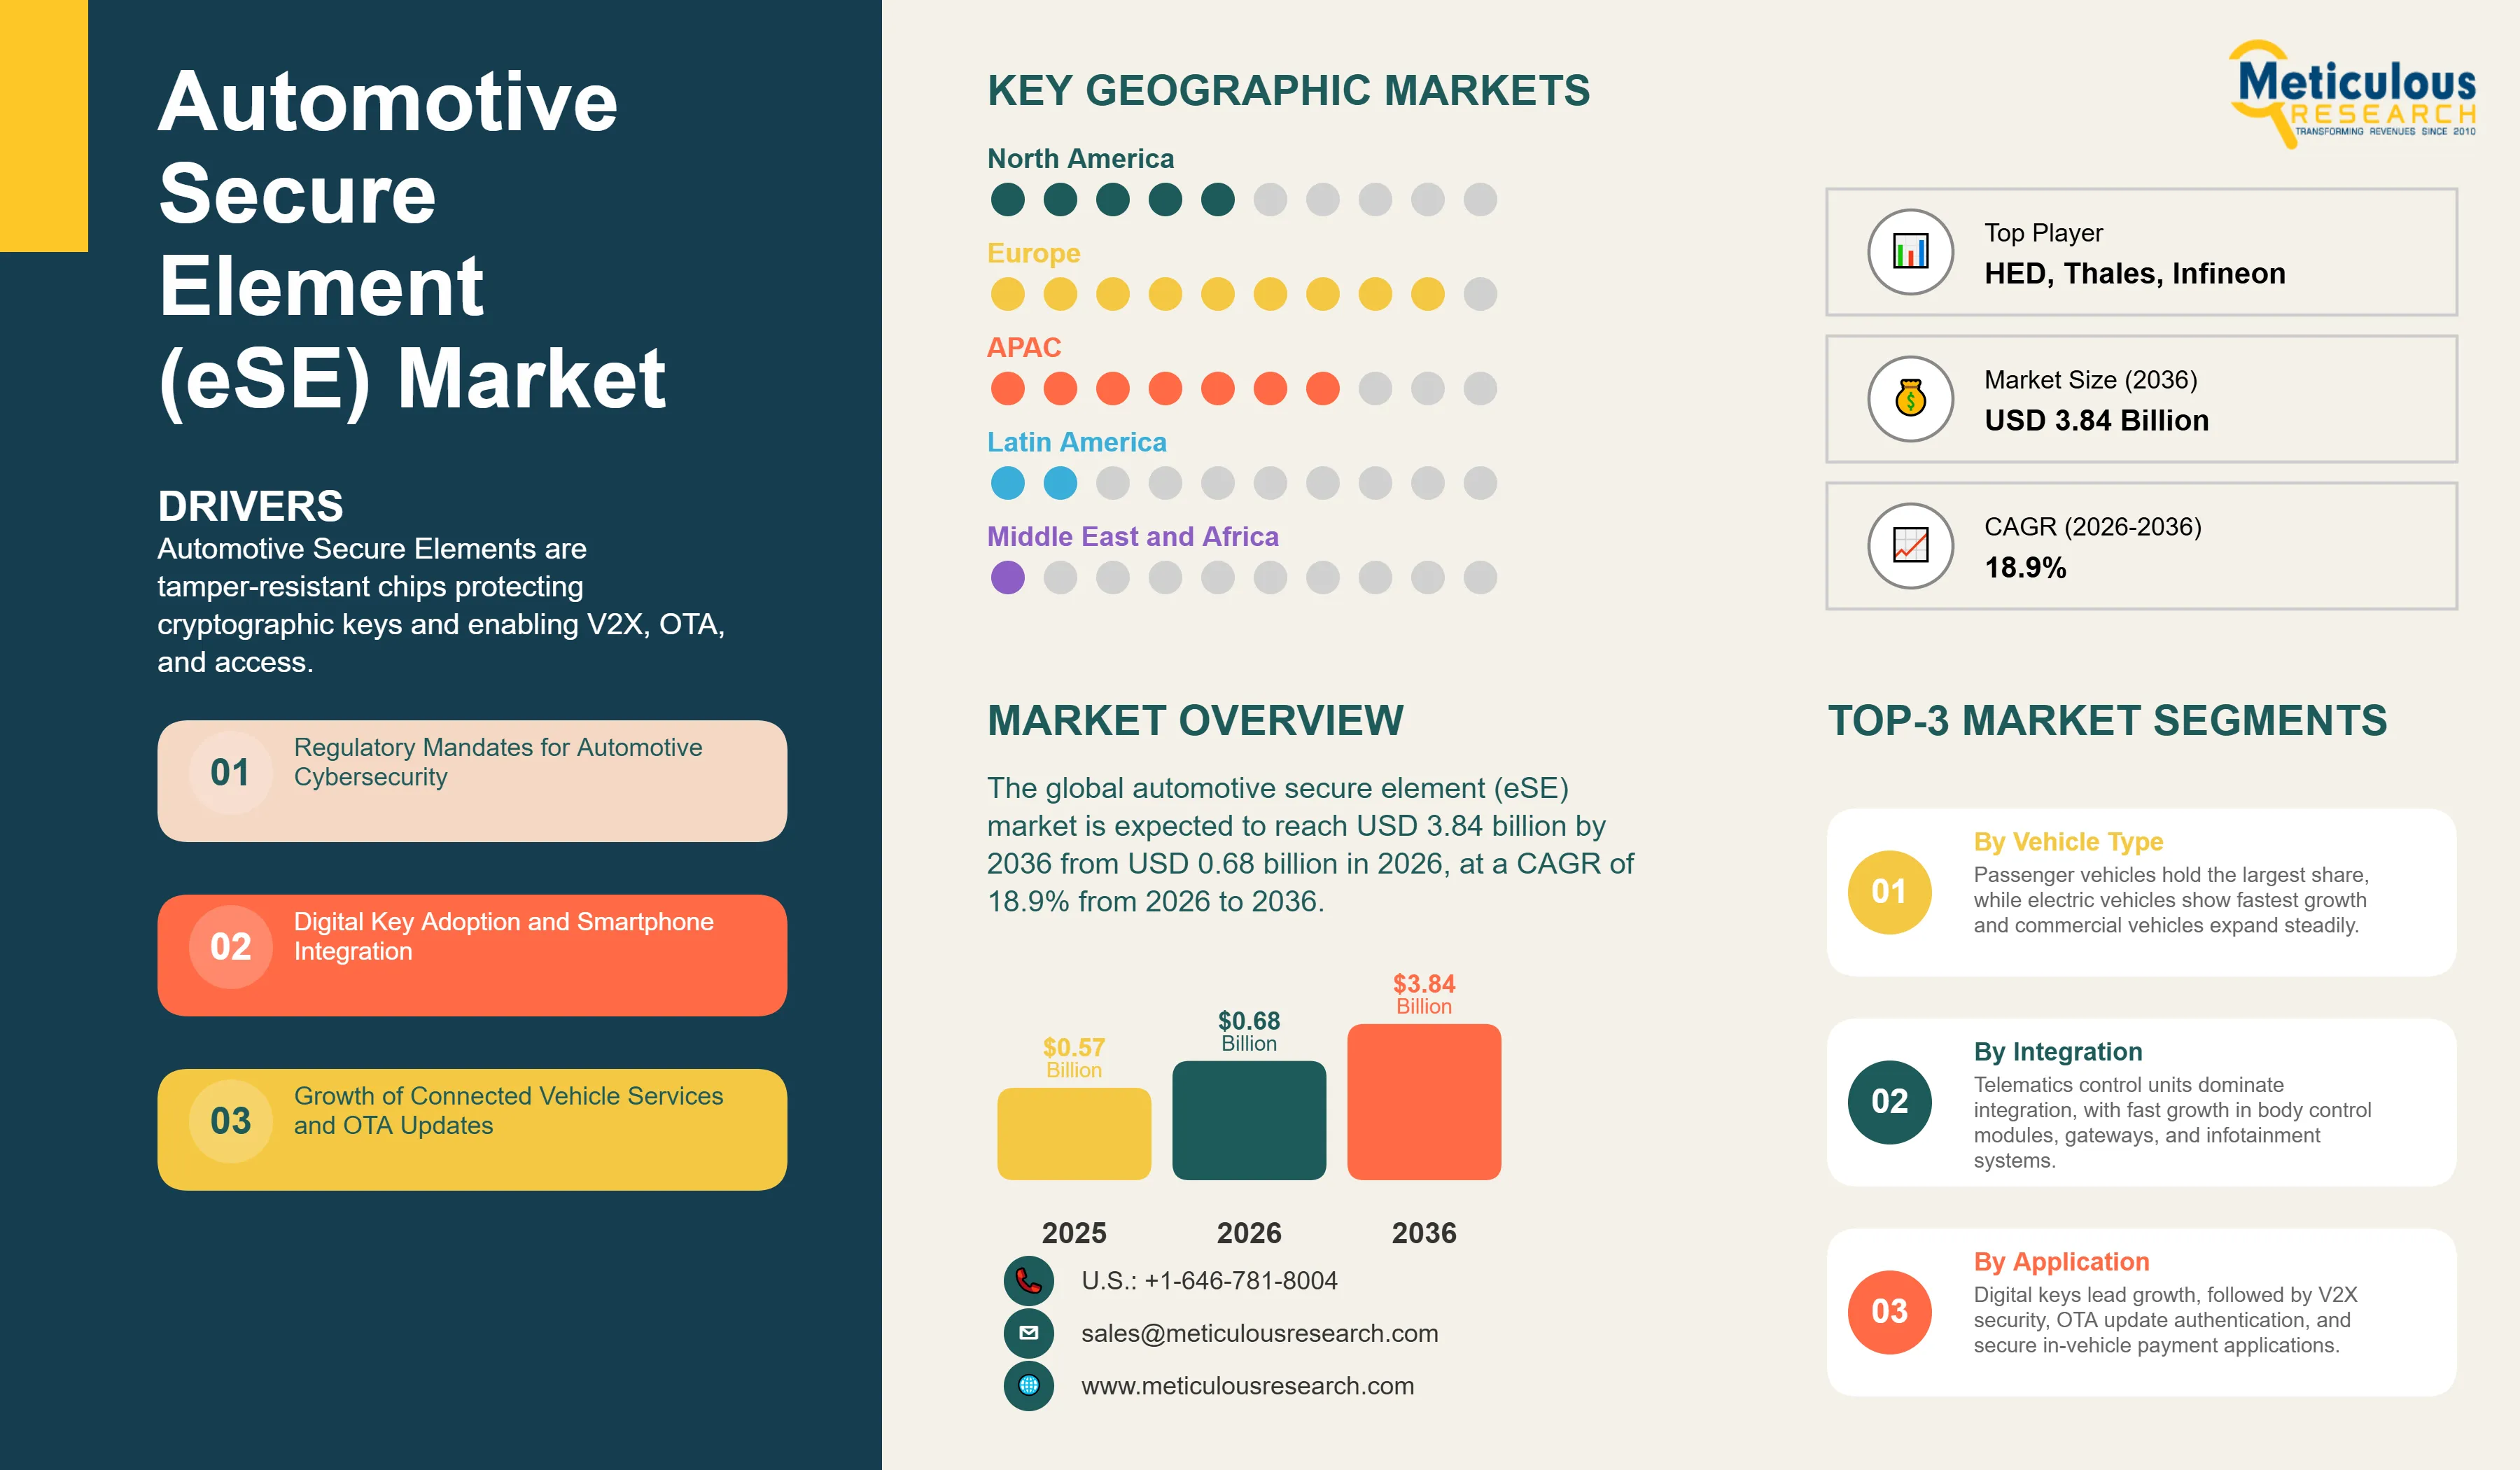
The global automotive secure element (eSE) market is expected to reach USD 3.84 billion by 2036 from USD 0.68 billion in 2026, at a CAGR of 18.9% from 2026 to 2036.
- Published
- Jan 2026
- Pages
- 269
- Format
- PDF + Excel
- Report ID
- MRAUTO - 1041669
- Base year
- 2025
- 2026 · ESTIMATED
- $680.0M
- 2036
- $3.84B
- CAGR 2026–2036
- 18.9%
2025 baseline · 2026–2036 forecast at 18.9% CAGR · hover a bar for the value
Key highlights
In 2026, Europe accounts for the largest share of the global automotive secure element market, driven by stringent automotive cybersecurity regulations including UN R155/R156, strong presence of premium automotive manufacturers implementing digital key and connected services, and advanced development of secure V2X communication infrastructure.
Asia-Pacific is projected to register the highest CAGR during the forecast period, fueled by rapidly growing connected vehicle adoption, massive automotive production volumes in China and India, increasing smartphone-based digital key deployments, expanding electric vehicle segment requiring secure charging authentication, and rising cybersecurity awareness.
Based on eSE architecture, the embedded secure element (eSE) segment holds the largest share of the market in 2026, driven by its superior integration advantages, lower system cost compared to discrete solutions, and growing automotive OEM preference for integrated security in telematics control units and connectivity modules.
Based on security certification, the Common Criteria EAL5+ segment dominates the market in 2026, owing to its recognized international acceptance, comprehensive security evaluation requirements, and automotive industry preference for certified security solutions meeting regulatory cybersecurity standards.
Based on application, the digital key segment is expected to witness the highest growth during the forecast period, driven by consumer demand for smartphone-based vehicle access, automotive OEM differentiation strategies, and Apple CarKey and Google Digital Car Key ecosystem expansion.
Based on integration, the telematics control unit (TCU) integration segment accounts for the largest share of the market in 2026, fueled by TCU's role as the primary connectivity gateway requiring comprehensive security for cellular communication, cloud connectivity, and over-the-air updates.
The V2X communication segment is expected to grow at a significant CAGR during the forecast period, driven by regulatory mandates for cooperative intelligent transport systems in Europe and China, and security requirements for authenticated vehicle-to-vehicle and vehicle-to-infrastructure messaging.
The U.S. automotive secure element market is projected to grow at a CAGR of around 17% during the forecast period 2026 to 2036, driven by increasing cybersecurity regulations, growing digital key adoption, and expansion of connected vehicle services requiring secure authentication.
China is expected to lead the Asia-Pacific automotive secure element market, driven by massive automotive production, government cybersecurity requirements for connected and intelligent vehicles, rapid digital payment integration in vehicles, and extensive V2X infrastructure deployment.
In 2026, Germany is projected to account for the largest share of the European automotive secure element market, driven by its premium automotive segment leadership, early adoption of digital key technology by manufacturers like BMW and Mercedes-Benz, and pioneering C-V2X communication deployment.
Report summary
| Particulars | Details |
|---|---|
| Market Size Value in 2026 | USD 0.68 Billion |
| Revenue Forecast in 2036 | USD 3.84 Billion |
| Growth Rate | CAGR of 18.9% from 2026 to 2036 |
| Format | PDF, Excel & Cloud Portal · 269 pages |
| Base Year for Estimation | 2025 |
| Historical Data | 2021–2025 |
| Forecast Period | 2026–2036 |
| Quantitative Units | Revenue in USD Billion and CAGR from 2026 to 2036 |
| Report Coverage | Revenue forecast, company ranking, competitive landscape, growth factors, and trends |
| Segments Covered | eSE Architecture, Security Certification, Application, Integration, Vehicle Type, Region |
| Regional Scope | North America, Europe, Asia-Pacific, Latin America, Middle East & Africa |
| Countries Covered | U.S., Canada, Germany, U.K., France, Italy, Spain, Netherlands, China, Japan, South Korea, India, Taiwan, Brazil, Mexico, Saudi Arabia, UAE, South Africa |
| Key Companies Profiled | NXP Semiconductors N.V., Infineon Technologies AG, STMicroelectronics N.V., Samsung Semiconductor, Giesecke+Devrient Mobile Security GmbH, Thales Group, IDEMIA Group, Inside Secure (Verimatrix), Microchip Technology Inc., Renesas Electronics Corporation, KONA I Co. Ltd., Nationz Technologies Inc., CEC Huada Electronic Design Co. Ltd., Watchdata Technologies Ltd., Eastcompeace Technology Co. Ltd., HED (Hangzhou) Co. Ltd., Fingerprint Cards AB, Qualcomm Technologies Inc., Texas Instruments Incorporated, Nordic Semiconductor ASA |
Report overview
Segments covered: ese architecture, security certification, application, integration, vehicle type.
Automotive Secure Elements (eSE) are tamper-resistant integrated circuits that provide hardware-based security for storing and processing sensitive cryptographic keys, credentials, and important data in connected vehicles. These specialized security chips include cryptographic accelerators, secure key storage that resists physical attacks, and isolated environments for sensitive operations. They also have measures against physical and logical attacks, such as side-channel analysis, fault injection, and reverse engineering. By using robust security designs certified to international standards like Common Criteria EAL5+ and higher, automotive secure elements support vital vehicle security functions. These include digital key authentication for keyless entry and ignition, secure vehicle-to-everything (V2X) communication with message signing and verification, authentication for over-the-air (OTA) software updates, in-vehicle payment processing for tolls and commerce, and protection of intellectual property and sensitive vehicle data from theft and manipulation.
Automotive Secure Elements represent a critical foundation for connected vehicle security, addressing the fundamental challenge of protecting cryptographic keys and sensitive security operations in increasingly connected, software-defined vehicles vulnerable to cyber attacks. These specialized hardware security modules serve as trust anchors for vehicle security architectures, providing isolated, tamper-resistant environments for storing root cryptographic keys, performing security-critical operations including digital signature generation and verification, authenticating software updates and downloaded code, and protecting against sophisticated attacks that target software-based security implementations. By leveraging dedicated hardware security features including true random number generators, cryptographic accelerators, secure key storage with physical unclonable functions (PUFs), and comprehensive attack countermeasures, automotive secure elements provide security assurances that cannot be achieved through software-alone approaches.
Several transformative trends are reshaping the automotive secure element market, including the rapid proliferation of connected vehicle services requiring secure authentication and data protection, the advancement of digital key technologies enabling smartphone-based vehicle access replacing traditional key fobs, the deployment of vehicle-to-everything (V2X) communication requiring message authentication to prevent spoofing and malicious messages, regulatory mandates for automotive cybersecurity driving systematic security implementation, and the expansion of in-vehicle payment applications for parking, tolling, charging, and commerce requiring payment-grade security. The convergence of connectivity expansion, cybersecurity threat sophistication, regulatory pressure, and consumer demand for seamless digital experiences has elevated automotive secure elements from optional security enhancements to essential components of modern vehicle electronic architectures.
Report infographic
Market dynamics
9 factors across 3 forcesRegulatory Mandates for Automotive Cybersecurity
Regulatory requirements for automotive cybersecurity represent the primary catalyst driving secure element adoption across global automotive markets. The United Nations Economic Commission for Europe (UNECE) regulations UN R155 (cybersecurity) and UN R156 (software updates) came into force in July 2024, requiring all new vehicle types sold in Europe, Japan, South Korea, and other adopting countries to implement comprehensive cybersecurity management systems and demonstrate cybersecurity protections throughout vehicle lifecycles. UN R155 specifically requires vehicle manufacturers to protect vehicles against cyber attacks targeting vehicle functions, protect backend servers and update systems, and implement security by design processes. These regulations create mandatory requirements for strong cryptography, secure key management, authenticated software updates, and other security functions that necessitate hardware security modules like secure elements. The European Union's proposed Cyber Resilience Act extends cybersecurity requirements to automotive components and systems, further driving secure element adoption. China has implemented parallel cybersecurity regulations for intelligent and connected vehicles through standards including GB/T and mandatory guidelines requiring security measures protecting vehicle data, communications, and software. The United States, while not yet mandating comprehensive automotive cybersecurity through federal regulation, has seen increasing focus from the National Highway Traffic Safety Administration (NHTSA) and proposed legislation that will likely result in regulatory requirements. These converging global regulations create unavoidable requirements for automotive secure elements as foundational security components.
Digital Key Adoption and Smartphone Integration
The rapid adoption of digital key technologies enabling smartphone-based vehicle access represents a major growth driver for automotive secure elements. Digital key implementations allow vehicle owners to use smartphones, smartwatches, or other personal devices instead of traditional key fobs for vehicle locking, unlocking, starting, and increasingly for feature authorization and vehicle sharing. Major automotive OEMs including BMW, Mercedes-Benz, Audi, Genesis, Hyundai, and others have deployed digital key capabilities, with mainstream adoption expanding rapidly. Industry standardization through the Car Connectivity Consortium (CCC) Digital Key specification, combined with Apple CarKey and Google Digital Car Key integration in iOS and Android operating systems, is accelerating ecosystem development and consumer adoption. According to industry analysts, digital key penetration is expected to reach over 50% of new vehicles by 2030, up from approximately 15% in 2025. Each digital key implementation requires secure elements in both the vehicle and the user's mobile device to store authentication credentials, perform cryptographic operations for mutual authentication, and enable secure credential sharing. Vehicle-side secure elements must support multiple wireless interfaces including NFC for passive entry, UWB for precise positioning enabling approach detection and ranging, and Bluetooth Low Energy for remote functions. The technology enables new business models including car sharing services, rental fleet applications, and temporary access for delivery services, all requiring secure credential management that secure elements provide.
Table of contents
15 chapters · 219 sections · 269 pages · click to expandGeographic analysis
Europe
Largest shareGermany dominates the regional market through its automotive industry leadership and premium segment focus on advanced connectivity and security features. European automotive OEMs have been early adopters of digital key technologies, with BMW, Mercedes-Benz, and others deploying smartphone-based access starting in 2020-2021. The region's focus on vehicle-to-everything communication, driven by European Commission cooperative intelligent transport systems initiatives, creates additional secure element demand for V2X message signing and certificate management.
Asia-Pacific
Fastest growthThe Asia-Pacific region is expected to grow at the highest CAGR during the forecast period due to rapidly expanding connected vehicle adoption with China leading global deployments of intelligent connected vehicles, massive automotive production volumes with China, Japan, and South Korea representing over 50% of global manufacturing, China's stringent cybersecurity regulations for connected and intelligent vehicles requiring security implementations, extensive V2X infrastructure deployment in China with government-backed C-V2X rollout, growing digital payment integration in vehicles leveraging Asia's advanced mobile payment ecosystems, and expanding electric vehicle production requiring secure charging authentication. China will drive substantial regional growth through government mandates for intelligent connected vehicle security, massive market scale with over 25 million annual vehicle production, domestic automotive semiconductor industry development including secure element capabilities, and extensive smart city and V2X infrastructure investments. Japan contributes through its automotive manufacturers (Toyota, Honda, Nissan) adopting connected services and digital key, and semiconductor industry presence including secure element suppliers. South Korea participates through automotive industry (Hyundai, Kia) technology leadership in connectivity and EVs, and semiconductor industry strength.
North America
North America represents a significant market driven by high connected vehicle penetration particularly for telematics and emergency calling, growing digital key adoption by domestic and international OEMs, increasing cybersecurity focus from NHTSA and proposed federal legislation, strong automotive technology innovation ecosystem in Silicon Valley and Detroit, and large high-value vehicle market with strong premium and luxury segment. The United States market is characterized by high consumer demand for connectivity and smartphone integration features, voluntary security adoption by leading OEMs ahead of regulatory requirements, extensive automotive cybersecurity research and development, and growing EV adoption particularly in California and other progressive markets creating demand for secure charging solutions.
Competitive landscape
- NXP Semiconductors N.V. · Netherlands
- Infineon Technologies AG · Germany
- STMicroelectronics N.V. · Switzerland
- Samsung Semiconductor · South Korea
- Giesecke+Devrient Mobile Security GmbH · Germany
- Thales Group · France
- IDEMIA Group · France
- Inside Secure (now part of Verimatrix) (France/U.S.)
- Microchip Technology Inc. (U.S.)
- Renesas Electronics Corporation · Japan
- KONA I Co. Ltd. · South Korea
- Nationz Technologies Inc. · China
- CEC Huada Electronic Design Co. Ltd. · China
- Watchdata Technologies Ltd. · China
- Eastcompeace Technology Co. Ltd. · China
- HED (Hangzhou) Co. Ltd. · China
- Fingerprint Cards AB · Sweden
- Qualcomm Technologies Inc. (U.S.)
- Texas Instruments Incorporated (U.S.)
- Nordic Semiconductor ASA · Norway
Frequently asked questions
The automotive secure element market is expected to grow from USD 0.68 billion in 2026 to USD 3.84 billion by 2036.
Cite this report
Meticulous Research. (2026). Automotive Secure Element (eSE) Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MRAUTO - 1041669). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/automotive-secure-element-market-6352