Frozen Food Market (2024-2031)
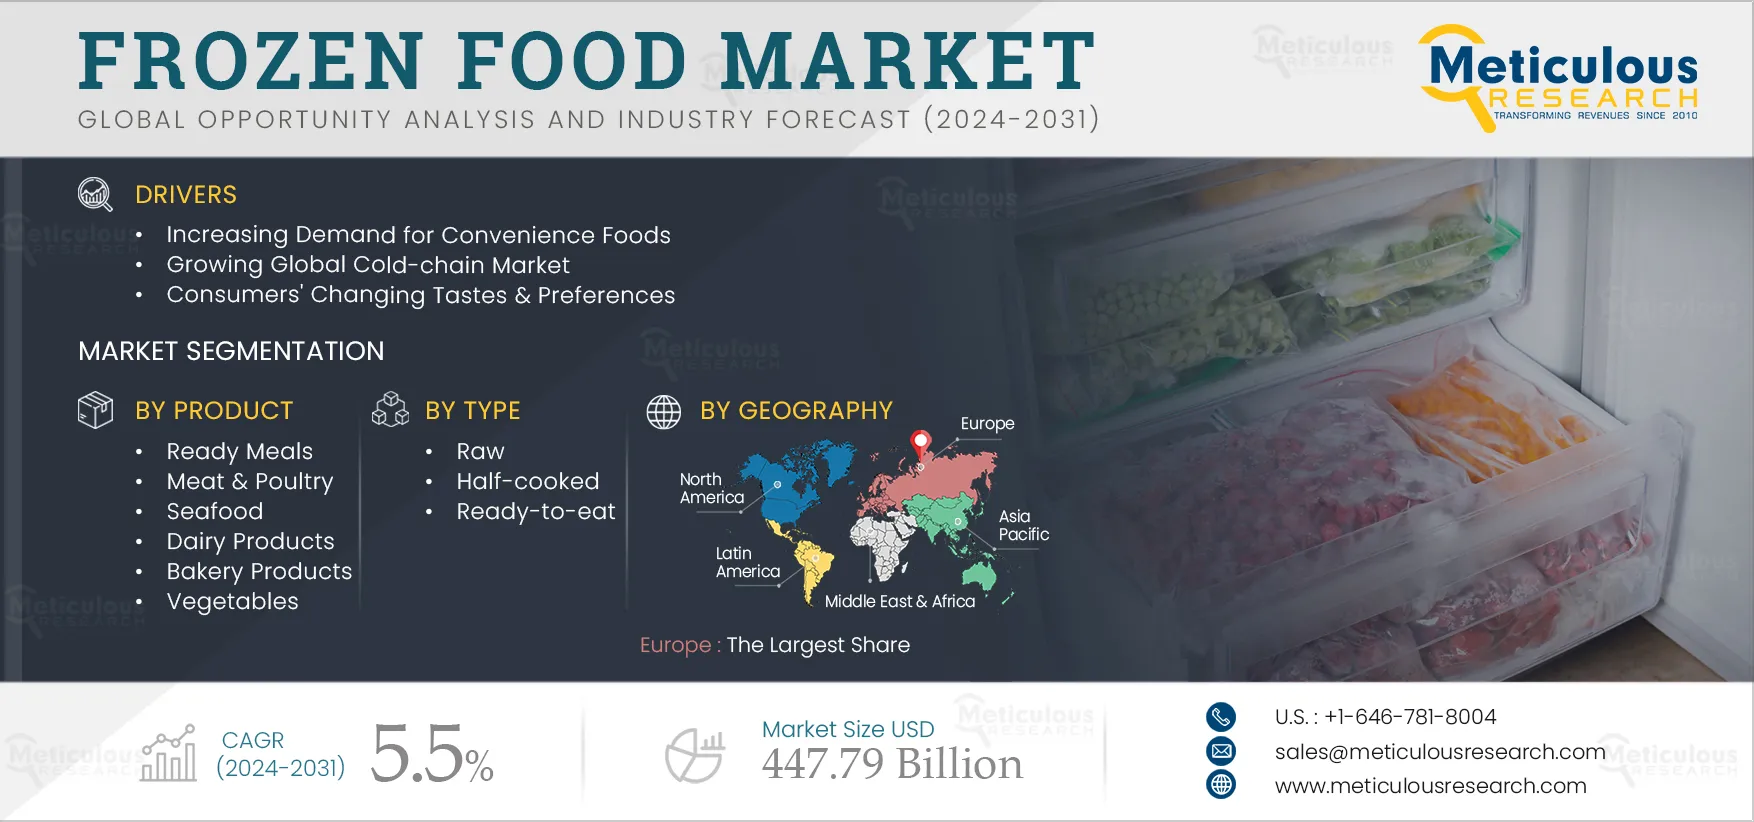
The Frozen Food Market is expected to reach $447.79 billion by 2031, at a CAGR of 5.5% during the forecast period of 2024–2031. Frozen Food Market Size & Forecast The frozen food market presents significant growth opportunities driven by factors such as the increasing demand for convenience foods,
- Published
- Dec 2022
- Pages
- 350
- Format
- PDF + Excel
- Report ID
- MRFB - 104627
- Base year
- 2023
- 2031 · FORECAST
- $447.8B
- 2031
- $447.8B
- CAGR 2024–2031
- 5.5%
2023 baseline · 2024–2031 forecast at 5.5% CAGR · hover a bar for the value
Key highlights
By Product: In 2024, the Ready Meals Segment to Dominate the Frozen Food Market
By Type: In 2024, the Raw Segment to Dominate the Frozen Food Market
By Distribution Channel: The Business-to-consumer Segment to Witness Highest Demand During the Forecast Period
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | ~350 |
| Format | |
| Forecast Period | 2024–2031 |
| Base Year | 2023 |
| CAGR (Value) | 5.5% |
| Market Size (Value) | USD 447.79 Billion |
| Segments Covered | By Product · Ready Meals · Meat & Poultry · Seafood · Dairy Products · Bakery Products · Breads · Pizza Crusts · Cakes & Pastries · Cookies & Biscuits · Doughnuts · Waffles · Other Frozen Bakery Products · Vegetables · Fruits · Other Frozen Food Products · By Type · Raw · Half-cooked · Ready-to-eat · By Distribution Channel · Business-to-business (B2B) · Food Services · Food Manufacturers · Quick Service Restaurants (QSR’s) · Business-to-consumer (B2C) · Offline · Supermarkets & Hypermarkets · Convenience Stores · Other Offline Stores · Online |
| Countries Covered | North America (U.S., Canada), Europe (Germany, U.K., France, Italy, Spain, Poland, Netherlands, Switzerland, Belgium, Sweden, and Rest of Europe), Asia-Pacific (China, Japan, Australia, South Korea, India, Indonesia, Thailand, Malaysia, and Rest of Asia-Pacific), Latin America (Brazil, Mexico, Argentina, and Rest of Latin America), and the Middle East & Africa (UAE, Saudi Arabia, South Africa, and Rest of Middle East & Africa) |
| Key Companies | General Mills, Inc. (U.S.), Conagra Brands, Inc. (U.S.), Nestlé S.A. (Switzerland), Unilever PLC (U.K.), McCain Foods Limited (Canada), The Kraft Heinz Company (U.S.), Tyson Foods, Inc. (U.S.), Associated British Foods plc (U.K.), Ajinomoto Co., Inc. (Japan), Vandemoortele NV (Belgium), Lantmännen Unibake International (A Part of Lantmännen Group) (Denmark), Cargill, Incorporated (U.S.), Europastry, S.A. (Spain), JBS S.A. (Brazil), ARYZTA AG (Switzerland), and Nomad Foods Limited (U.K.) |
Report overview
Segments covered: product, type. Regions: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa.
The frozen food market presents significant growth opportunities driven by factors such as the increasing demand for convenience foods, the expansion of the global cold-chain industry, and evolving customer preferences. The market's growth is, however, restrained by the rising preference for natural and fresh foods and the need for constant temperature monitoring of frozen food. The increasing penetration of E-commerce and the emergence of economies in Asia-Pacific, Latin America, and the Middle East & Africa are expected to create significant growth opportunities. Conversely, the lack of cold-chain infrastructure in developing countries is a major challenge. Noteworthy trends in the global frozen food market include the rise of plant-based and gluten-free frozen food products.
Report infographic
Market dynamics
5 factors across 3 forcesIncreasing Demand for Convenience Foods Driving Market Growth
Consumer demand for convenience foods has increased substantially during the previous decade. Consumers are increasingly turning to convenience food products such as baked goods, confectioneries, beverages, and ready meals as they are quick and easy to prepare. The need for dinner-time solutions among modern customers is fast expanding as a result of severe changes in meal consumption behavior. Many people are willing to spend money on ready-to-eat foods, given that they lack the time and ability required to prepare their food at home. It's important to note that the convenience trend is not a fad but a long-term phenomenon. Increased urbanization is expected to help the convenience movement gain traction, providing stability in the market.
Furthermore, as urbanization accelerates, so does the need for convenience food products, owing mostly to changing lifestyles, an increase in the number of nuclear families, an increasing proportion of workers, and a lack of time for food preparation. These elements make a compelling case for the accelerated growth of the frozen food products market, as frozen food products are widely available and have extended shelf life. As a result, the growing demand for convenience foods drives the frozen food business.
Growing Global Cold-chain Market to Boost Market Growth
Cold-chain operations involve logistics planning and maintaining the temperatures at which perishable food products are stored through refrigeration or thermal packing. This increases product shelf life and helps maintain product quality for longer. Freezing preserves the physical and biochemical properties of fresh agricultural meat, poultry, and seafood products. The cold-chain market is driven by favorable government initiatives, technological advancements in refrigerated storage, and the increasing number of middle-income consumers in developing countries.
In addition, the implementation of advanced technologies in cold chains has facilitated modern warehouse management using modern heavy-duty refrigeration systems that help maintain proper temperatures during the transportation & storage of food. The adoption of innovative IoT-based automated software for cold-chain management provides live data to operators, allowing for unmatched visibility into every process and transaction within cold-chain logistics. Operators can connect to intermodal shipping containers, cargo, vessels, and trailers with enterprise IT systems via sensors, GPS, mobile networks, and cloud-based platforms. Thus, all these factors are expected to boost the global cold-chain market, in turn driving the demand for frozen food in the coming years.
Table of contents
11 chapters · 143 sections · 350 pages · click to expandSegmental analysis
| Segment | Largest share (2024) | Fastest growth (2024–2031) |
|---|---|---|
| By Product | Ready Meals | Seafood |
| By Type | Raw | Ready-to-eat |
| By Distribution Channel | — | Business-to-consumer |
By Product
- The Ready Meals Segment to Dominate the Frozen Food Market
- The ready meals segment is expected to account for the largest share of 32.1% of the frozen food market.
- This segment's substantial market share is attributed to changes in consumer habits as a result of the fast-paced work environment, notably among the working-class population, as well as a growing preference for ready-frozen meals for convenience.
- Furthermore, the growing popularity of ready meals among the younger age and teen population, as well as the widespread availability of frozen food in convenience stores and supermarkets, contribute to this segment's substantial market share.
- However, the seafood segment is estimated to register the highest CAGR during the forecast period.
- The high protein content of fish, rising worldwide aquaculture production, and the expansion of supermarkets and hypermarkets are the main drivers of this growth.
- The market for frozen seafood is expected to grow due to the increasing demand for frozen seafood as a thickening agent, as well as the increasing use of quick-freezing technologies.
By Type
- The Raw Segment to Dominate the Frozen Food Market
- The raw segment is expected to account for the largest share of 46.3% of the frozen food market.
- This segment’s large market share is attributed to the rising consumer awareness about the nutritional properties of raw frozen food, the growing adoption of frozen technologies in the fresh fruits and vegetables sector, and the increasing number of raw frozen food product launches.
- However, the ready-to-eat segment is projected to record the highest CAGR during the forecast period.
- This segment's rapid growth is mainly driven by rapid urbanization and increasing disposable income, changing lifestyles and busy schedules of working individuals, growing demand for convenient and healthy food, and continuous innovation and new product developments.
By Distribution Channel
- The Business-to-consumer Segment to Witness Highest Demand During the Forecast Period
- The business-to-business segment is expected to account for the larger share of 52.7% of the frozen food market.
- The growing number of quick service restaurants (QSRs), the expanding B2B frozen food trading, and the increasing demand from hotels, restaurants, food chains, cafes, and the food service industry are all responsible for this segment's significant market share.
- However, the business-to-consumer segment is estimated to register the highest CAGR during the forecast period.
- This growth is being driven by rising urban population density, an increasing trend of online shopping, an increasing number of supermarkets and hypermarkets, the growing popularity of the franchising concept, and a growing preference for personalization, consumer convenience, and greater product selection.
Geographic analysis
Europe
Largest shareIn 2024, Europe is expected to account for the largest share of 36.9% of the frozen food market, followed by North America, Asia-Pacific, Latin America, and the Middle East & Africa. Europe’s significant market share can be attributed to several key factors, including the rising preference for ready-to-eat food, favorable regulations, a well-established cold chain in the region, innovative practices by key players in the industry, technological innovation in the frozen food sector, busier lifestyles of consumers, introduction of various healthy and diet-related frozen meals, and the growing import of frozen food.
Asia-Pacific
Fastest growthHowever, Asia-Pacific is anticipated to register the highest CAGR during the forecast period. Consumer lifestyle changes, rising disposable income, an increase in foreign direct investment (FDI) in the retail sector, expanding cold-chain facilities, and rising demand for processed food products in emerging markets such as India, Indonesia, and Thailand all contribute to the growth of this regional market. Furthermore, increased demand for dairy products such as yogurt and sour milk is propelling the frozen food market in the region.
Competitive landscape
- July 2023
Conagra Brands introduced over fifty new items in its snack, supermarket, and frozen businesses. Conagra offers a broad range of flavors and price points for all of its brands and entrees in its frozen portfolio.
- September 2022
McCain Foods acquired Scelta Products (Netherlands) to expand its presence in the global prepared appetizers sector and meet customer and consumer demand.
- June 2022
General Mills acquired TNT Crust (U.S.), a company that produces high-quality frozen pizza crusts for regional and national pizza franchises, food service distributors, and retail stores. As part of the transaction, General Mills bought two manufacturing plants in Green Bay, Wisconsin, and one in St. Charles, Missouri.
- June 2022
Conagra Brands opened a state-of-the-art vegetable processing plant in Waseca, Minnesota. The new 245,000-square-foot plant prepares fresh veggies for Conagra's frozen meals division and the Birds Eye brand. It was designed from the ground up with an emphasis on maximizing automation to increase efficiency and improve food safety throughout.
- General Mills, Inc. (U.S.)
- Conagra Brands, Inc. (U.S.)
- Nestlé S.A. · Switzerland
- Unilever PLC (U.K.)
- McCain Foods Limited · Canada
- Kraft Heinz Company (U.S.)
- Tyson Foods, Inc. (U.S.)
- Associated British Foods plc (U.K.)
- Ajinomoto Co., Inc. · Japan
- Vandemoortele NV · Belgium
- Cargill, Incorporated (U.S.)
- Europastry, S.A. · Spain
- JBS S.A. · Brazil
- ARYZTA AG · Switzerland
- Nomad Foods Limited (U.K.)
Frequently asked questions
The Frozen Food Market refers to the sector involved in the production and distribution of food items that are preserved through freezing. This includes products like ready meals, vegetables, seafood, and meats, catering to consumer preferences for convenience and longer shelf life.
Cite this report
Meticulous Research. (2022). Frozen Food Market - Global Opportunity Analysis and Industry Forecast (2024-2031) (Report No. MRFB - 104627). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/frozen-food-market-5313