Frozen Dough Market (2025-2032)
The Frozen Dough Market was valued at $22.9 billion in 2024. This market is expected to reach $37.8 billion by 2032 from an estimated $24.2 billion in 2025, at a CAGR of 6.6% during the forecast period from 2025 to 2032. Frozen Dough Market Size & Forecast This market's growth can be attributed to
- Published
- Jan 2025
- Pages
- 200
- Format
- PDF + Excel
- Report ID
- MRFB - 1041315
- Base year
- 2024
- 2024 · BASELINE
- $22.90B
- 2032
- $37.80B
- CAGR 2025–2032
- 6.6%
2024 baseline · 2025–2032 forecast at 6.6% CAGR · hover a bar for the value
Key highlights
The Frozen Dough Market was valued at $22.9 billion in 2024.
This market is expected to reach $37.8 billion by 2032 from an estimated $24.2 billion in 2025, at a CAGR of 6.6% during the forecast period from 2025 to 2032.
The Bread Segment to Dominate the Frozen Dough Market in 2025
The Business-to-Business (B2B) Segment Dominate the Frozen Dough Market in 2025
In 2025, Europe is expected to account for the largest share of 40.1% of the frozen dough market, followed by North America, Asia-Pacific, Latin America, and the Middle East & Africa.
However, Asia-Pacific is poised to register the highest CAGR of 8.5% during the forecast period. Consumer lifestyle changes, rising disposable income, an increase in foreign direct investment (FDI) in the retail sector, expanding cold-chain facilities, and rising demand for processed food products in emerging markets such as India, Indonesia, and Thailand all contribute to the growth of this regional market.
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | ~200 |
| Format | |
| Forecast Period | 2025–2032 |
| Base Year | 2024 |
| CAGR (Value) | 6.6% |
| Market Size (Value) | USD 37.8 Billion |
| Segments Covered | By Product · Bread · Pizza Crusts · Rolls & Pastries · Cookies & Biscuits · Bagels · Other Products · By Distribution Channel · Business-to-business (B2B) · Food Services · Food Manufacturers · Quick Service Restaurants (QSR’s) · Business-to-consumer (B2C) · Offline · Supermarkets & Hypermarkets · Convenience Stores · Other Offline Stores · Online |
| Countries Covered | North America (U.S., Canada), Europe (Germany, U.K., France, Italy, Spain, Poland, Netherlands, Belgium, and Rest of Europe), Asia-Pacific (China, Japan, Australia, South Korea, India, Indonesia, Thailand, Malaysia, Singapore, and Rest of Asia-Pacific), Latin America (Brazil, Mexico, Argentina, and Rest of Latin America), and the Middle East & Africa |
| Key Companies | General Mills, Inc. (U.S.), ARYZTA AG (Switzerland), Nestlé S.A. (Switzerland), Ajinomoto Co., Inc. (Japan), Campbell Soup Company (U.S.), Bridgford Foods Corporation (U.S.), Europastry, S.A. (Spain), Dawn Food Products, Inc. (U.S.), CSM Ingredients S.A.R.L. (Luxembourg), Guttenplan’s (U.S.), Lantmännen Unibake International (A Part of Lantmännen Group) (Denmark), and Okanagan Frozen Dough (Canada) |
Report overview
Segments covered: product, distribution channel. Regions: North America, Europe, Asia-Pacific, Latin America.
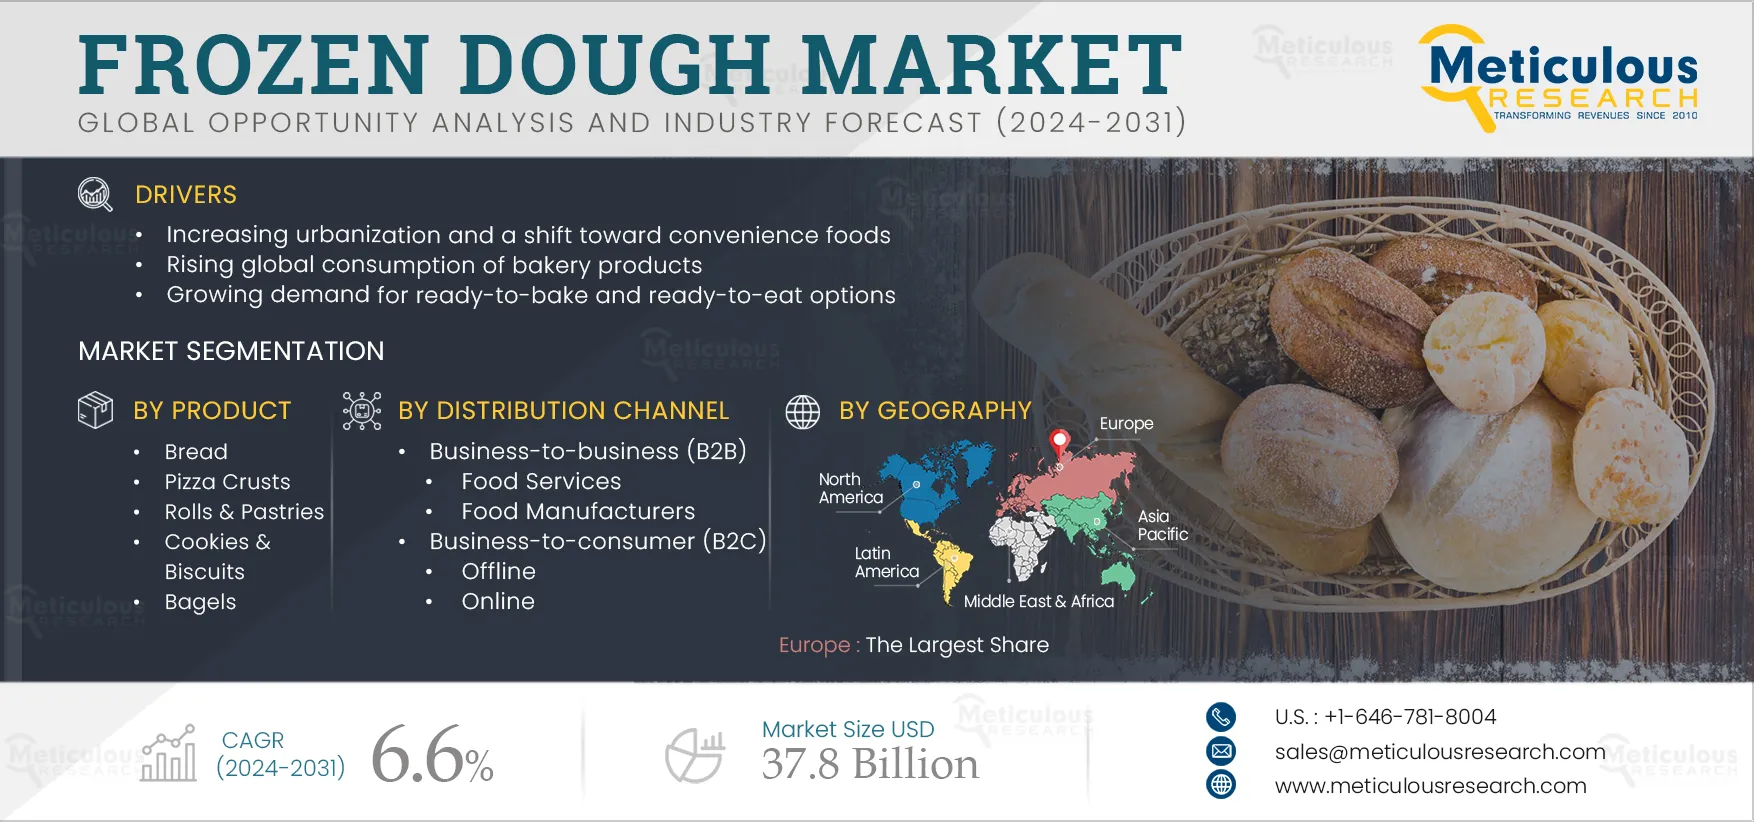
This market's growth can be attributed to multiple factors, such as increasing urbanization and a shift toward convenience foods, the rising global consumption of bakery products, and the growing demand for ready-to-bake and ready-to-eat options. However, challenges such as inadequate storage systems and perceptions of lower quality compared to freshly baked goods are hindering market growth.
Furthermore, the increasing demand for gluten-free and allergen-free options, coupled with the growth of emerging economies in Asia-Pacific, Latin America, and the Middle East & Africa, is anticipated to create substantial growth opportunities for stakeholders in the frozen dough market. On the other hand, the absence of robust cold-chain infrastructure in developing countries presents a significant challenge to market expansion. Prominent trends in the global frozen dough market include the rising popularity of clean-labeled products and a growing demand for frozen vegan dough options.
Report infographic
Market dynamics
5 factors across 3 forcesIncreasing Urbanization and Inclination Toward Convenience Foods
Over half of the global population now resides in urban areas, with nearly every country experiencing increased urbanization. The United Nations World Urbanization Report highlights that the urban population surged from 439,498,772 in 2015 to 471,031,528 in 2019, representing approximately 55% of the world's population—a figure projected to rise to 68% by 2050. This urban growth provides city dwellers with a broader range of food options and improved availability compared to those in rural areas. Additionally, urbanization drives enhanced living standards and higher incomes, which significantly impacts the affordability and accessibility of frozen dough products.
Additionally, with rising urbanization, there is a rapid increase in demand for convenience food products. This surge is driven by shifting lifestyles, a growing number of nuclear families, a higher proportion of working population, and reduced time for food preparation. Over the past few decades, consumer demand for convenience foods has expanded significantly, with many individuals showing a preference for products like baked goods that offer ease and efficiency.
Frozen dough products, such as pizza dough, bread dough, and pastry dough, provide a convenient solution for home baking and cooking. They save time and effort for consumers who wish to enjoy freshly baked goods without the hassle of preparing dough from scratch. The ease of simply thawing and baking aligns with the growing demand for time-saving food solutions, making these products increasingly popular among busy individuals and families. Additionally, the versatility and variety of frozen dough contribute to its rising demand. It enables the preparation of a wide range of baked goods, catering to diverse consumer preferences and dietary needs. This adaptability makes frozen dough an appealing option for both home cooks and food service providers seeking to broaden their menu offerings.
Moreover, advancements in freezing technology have enhanced the quality and shelf life of frozen dough products, ensuring they maintain their freshness and taste. Consequently, rising urbanization and a growing preference for convenience foods are accelerating the adoption of frozen dough, thereby driving market growth.
Rising Consumption of Bakery Products Worldwide
Bakery items such as bread, pastries, and pizzas have become staples in diets globally, and there is a growing demand for high-quality and convenient baking solutions. Consumers are increasingly looking for baked goods that can be prepared quickly at home, and frozen dough provides an ideal solution to meet this need.
Furthermore, the global appeal of diverse and artisanal bakery products is driving increased demand for frozen dough. As consumers develop a taste for specialty breads, gourmet pastries, and authentic pizzas, there is a growing need for versatile dough products that can accommodate these varied preferences. Frozen dough offers the flexibility to create a broad range of bakery items, catering to both traditional and innovative culinary trends. Additionally, there is a rising preference for free-from-food products, particularly gluten-free options, among individuals with celiac disease and the health-conscious population. The demand for gluten-free and sugar-free products is driven by the belief that they can help address issues related to bloating, indigestion, obesity, diabetes, and other health concerns. Consequently, bakery products that are marketed as fat, sugar, and gluten-free are gaining traction among health-conscious consumers. These factors are expected to significantly boost the demand for frozen dough in the coming years.
Table of contents
10 chapters · 120 sections · 200 pages · click to expandSegmental analysis
| Segment | Largest share (2025) | Fastest growth (2025–2032) |
|---|---|---|
| By Product | Bread | Cookies & biscuits |
| By Distribution Channel | Business-to-Business (B2B) | B2C |
By Product
- The Bread Segment to Dominate the Frozen Dough Market in 2025
- The bread segment is expected to account for the largest share of 30.7% of the frozen dough market.
- This segment’s large market share is driven by the rising global consumption of bread dough, which is favored for its convenience, versatility, and affordability.
- Frozen bread doughs offer quick preparation and adaptability to various customer needs.
- However, the cookies & biscuits segment is projected to record the highest CAGR during the forecast period.
- The rapid growth of this segment is primarily driven by the increasing demand for cookies & biscuits from all age groups, growing demand for convenient and ready-to-make products, and surge in demand for healthier baked goods.
- This includes cookies and biscuit dough products made with organic ingredients, whole grains, and reduced sugar.
- Moreover, innovations and new product launches are contributing to this growth.
By Distribution Channel
- The Business-to-Business (B2B) Segment Dominate the Frozen Dough Market in 2025
- The B2B segment is expected to account for a larger share of the frozen dough market.
- This segment's large market share is due to the growing B2B frozen food trading, the growing number of quick service restaurants (QSRs), and rising demand from hotels, restaurants, food chains, cafes, and the food service sector.
- However, the B2C segment is expected to register the highest CAGR during the forecast period.
- This segment's fast growth is mainly due to the rising population density in urban areas, the increasing trend of online shopping, and the growing number of supermarkets and hypermarkets.
Geographic analysis
Europe
Largest shareIn 2025, Europe is expected to account for the largest share of 40.1% of the frozen dough market, followed by North America, Asia-Pacific, Latin America, and the Middle East & Africa. The European frozen dough market is estimated to be worth USD 9,684.9 million in 2025. Europe’s significant market share can be attributed to several key factors, including the increasing preference for ready-to-eat food, favorable regulations, a well-established cold chain, innovative practices by leading industry players, advancements in frozen food technology, busier consumer lifestyles, and the rising import of frozen foods. Europe to Dominate the Global Frozen Dough Market in 2025
Asia-Pacific
Fastest growthHowever, Asia-Pacific is poised to register the highest CAGR of 8.5% during the forecast period. Consumer lifestyle changes, rising disposable income, an increase in foreign direct investment (FDI) in the retail sector, expanding cold-chain facilities, and rising demand for processed food products in emerging markets such as India, Indonesia, and Thailand all contribute to the growth of this regional market.
Competitive landscape
- November 2024
Okanagan Frozen Dough opened a new manufacturing facility in Calgary, Canada. The new facility is set to become an SQF-certified facility, which will aid the company’s stringent food safety program. It will feature spirals, a blast freezer, a mixer, and other equipment for quick-freezing products.
- August 2024
General Mills expanded its frozen dough plant in Joplin, Missouri, U.S., to boost manufacturing and packaging capacity. The expansion is projected to enable the plant to produce over 1 billion pounds of frozen dough products annually.
- General Mills, Inc. (U.S.)
- ARYZTA AG · Switzerland
- Nestlé S.A. · Switzerland
- Ajinomoto Co., Inc. · Japan
- Campbell Soup Company (U.S.)
- Bridgford Foods Corporation (U.S.)
- Europastry, S.A. · Spain
- Dawn Food Products, Inc. (U.S.)
- CSM Ingredients S.A.R.L · Luxembourg
- Guttenplan’s (U.S.)
- Okanagan Frozen Dough · Canada
Frequently asked questions
This report covers the frozen dough market sizes and forecasts based on product, distribution channel, and geography. It also provides the value analysis of various segments of the frozen dough market at the regional and country levels.
Cite this report
Meticulous Research. (2025). Frozen Dough Market - Global Opportunity Analysis and Industry Forecast (2025-2032) (Report No. MRFB - 1041315). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/frozen-dough-market-5998