Fill-finish Manufacturing Market (2025-2032)
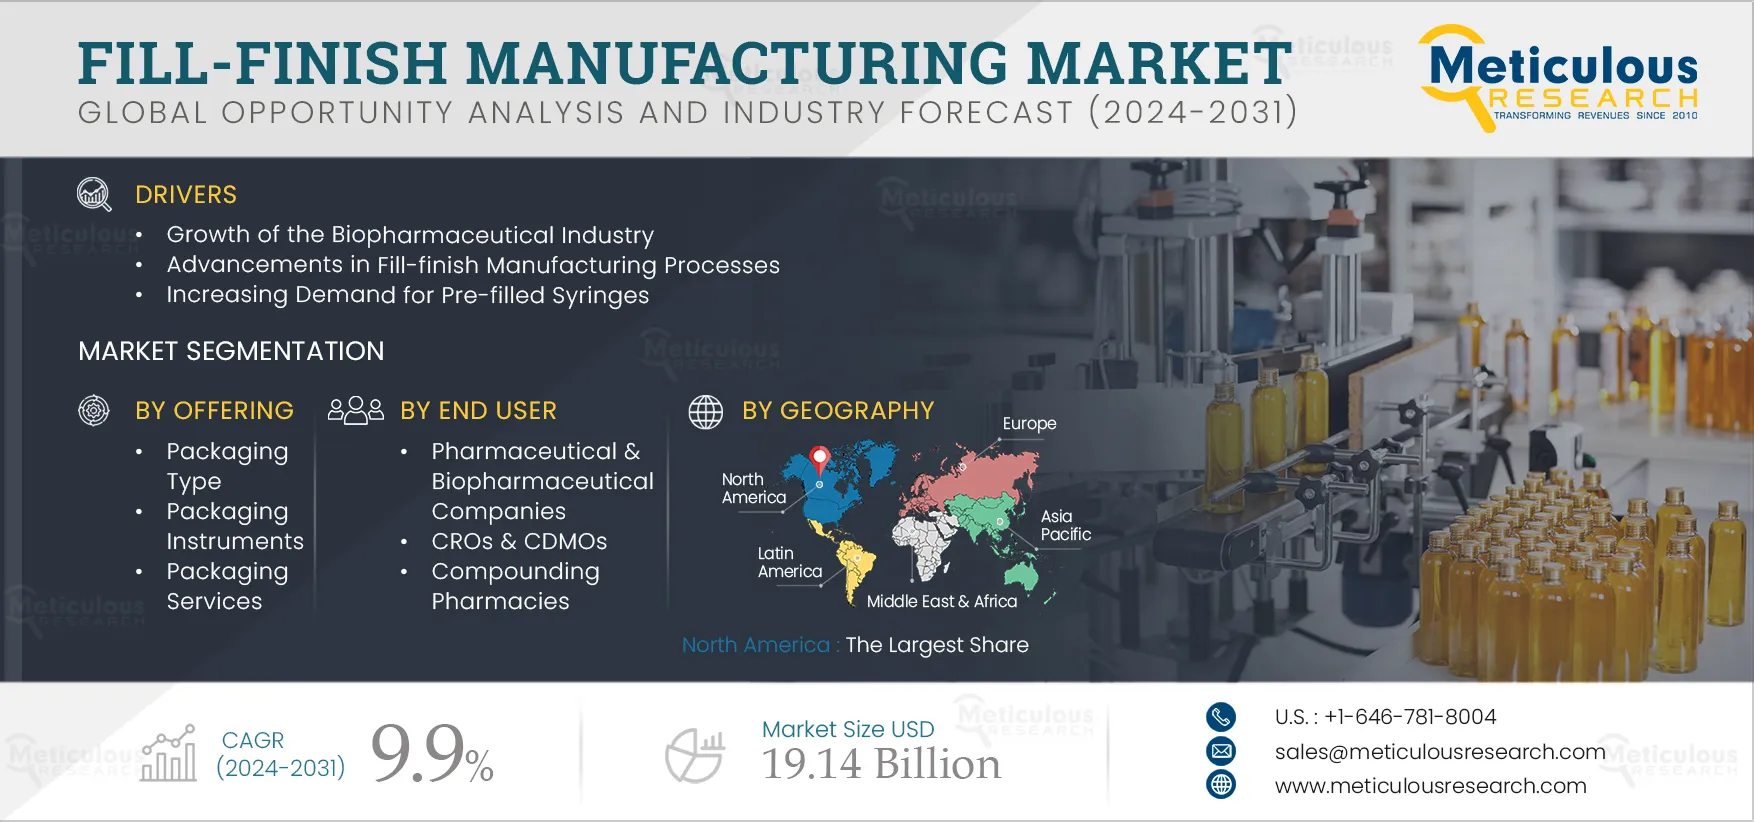
The Fill-finish Manufacturing Market is projected to reach $19.14 billion by 2032, at a CAGR of 9.9% from 2025 to 2032.
- Published
- Jun 2024
- Pages
- 550
- Format
- PDF + Excel
- Report ID
- MRHC - 1041247
- Base year
- 2024
- 2032 · FORECAST
- $19.14B
- 2032
- $19.14B
- CAGR 2025–2032
- 9.9%
2024 baseline · 2025–2032 forecast at 9.9% CAGR · hover a bar for the value
Key highlights
By Offering: In 2025, the Packaging Type Segment to Dominate the Fill-finish Manufacturing Market
By Formulation: In 2025, the Parenteral Segment to Dominate the Fill-finish Manufacturing Market
By Sterilization Process: In 2025, the Aseptic Processing Segment to Dominate the Fill-finish Manufacturing Market
By Application: In 2025, the Small Molecules Segment to Dominate the Fill-finish Manufacturing Market
By End User: In 2025, the CROs & CDMOs Segment to Dominate the Fill-finish Manufacturing Market
North America to Dominate the Market in 2025
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 550 |
| Format | |
| Forecast Period | 2025-2032 |
| Base Year | 2024 |
| CAGR | 9.9% |
| Estimated Market Size (Value) | $19.14 billion by 2032 |
| Segments Covered | By Offering · Packaging Type · Packaging Type, by Product · Vials · Liquid Vials · Lyophilized Vials · Powder Filled Vials · Syringes · Cartridges · Ampoules · Accessories · Packaging Type, by Material · Polymer · Glass · Other Materials · Packaging Instruments · Packaging Instrument, by System Type · Integrated Systems · Standalone Systems · Packaging Instrument, by Machine Type · Automated Machines · Semi-automated Machines · Packaging Instrument, by Type · Processing Instruments · Packaging Instruments · Bottle Filling & Capping Equipment · Blow-Fill-Seal (BFS) Equipment · Aseptic Filling Equipment · Pharmaceutical Spray Filling Equipment · Other Packaging Instruments · Packaging Services · Vials & Ampoules Filling · Injection Filling · Cartridge Filling · Other Packaging Services · (Note1: Other materials include rubber, metal, and paper) · (Note2: Other packaging instruments include powder sachet filling & packaging equipment, nested filling systems, tube filling equipment, and cream filling equipment.) · (Note3: Other packaging services include capsule filling, tube filling, sachet filling, and powder filling.) · By Formulation · Oral · Parenteral · Topical · Other Formulations · (Note: Other formulations include nasal, ocular, intradermal, and transcutaneous (TC) formulations.) · By Sterilization Process · Aseptic Processing · Terminal Sterilization · By Application · Biologics · Biologics, by Type · Monoclonal Antibodies · Recombinant Hormones/Proteins · Vaccines · Cellular Based Biologics · Gene-Based Biologics · Biologics, by Development Phase · Clinical/preclinical · Commercial · Small Molecules · Clinical/preclinical · Commercial · By End User · Pharmaceutical & Biopharmaceutical Companies · CROs & CDMOs · Compounding Pharmacies |
| Countries Covered | North America (U.S. and Canada), Europe (Germany, France, U.K., Italy, Spain, Switzerland, Ireland, Belgium, Denmark, and Rest of Europe), Asia-Pacific (China, Japan, India, South Korea, Australia, and Rest of Asia-Pacific), Latin America (Brazil, Mexico, and Rest of Latin America), and the Middle East & Africa. |
| Key Companies | The key players operating in the Fill-finish manufacturing market are Syntegon Technology GmbH (Germany), Becton, Dickinson and Company (U.S.), Industria Macchine Automatiche S.p.A. (Italy), West Pharmaceutical Services, Inc. (U.S.), Catalent, Inc. (U.S.), AbbVie Inc. (U.S.), Gerresheimer AG (Germany), AptarGroup, Inc. (U.S.), OPTIMA packaging group GmbH (Germany), Baxter International Inc. (U.S.), C.H. Boehringer Sohn AG & Co. KG (Germany), Schott Pharma AG & Co. KGaA (Germany), SGD Pharma (France), and Stevanato Group (Italy). |
Report overview
Segments covered: offering, packaging type, product, vial, liquid vial, lyophilized vial, powder filled vial, syringe, cartridge, ampoule, accessory, material, polymer, glass, other material, packaging instrument, system type, integrated system, standalone system, machine type, automated machine, semi-automated machine, type, processing instrument, bottle filling & capping equipment, aseptic filling equipment, pharmaceutical spray filling equipment, other packaging instrument, packaging service, vials & ampoules filling, injection filling, cartridge filling, other packaging service, formulation, oral, parenteral, topical, other formulation, sterilization process, aseptic processing, terminal sterilization, application, biologic, monoclonal antibody, recombinant hormones/protein, vaccine, cellular based biologic, gene-based biologic, development phase, clinical/preclinical, commercial, small molecule, end user, pharmaceutical & biopharmaceutical company, cros & cdmo, compounding pharmacy. Regions: North America, Europe, Asia-Pacific, Latin America.
The growth of this market is driven by the growth of the biopharmaceutical industry, initiatives by pharmaceutical & biopharmaceutical companies to expand their production capacities, advancements in fill-finish manufacturing processes, and the increasing demand for pre-filled syringes.
Moreover, initiatives aimed at increasing vaccination rates, increasing focus on biosimilar development, and rising investments in the development of new biologics are expected to create market growth opportunities.
Report infographic
Market dynamics
5 factors across 3 forcesGrowth of the Biopharmaceutical Industry
The global biopharmaceutical market is witnessing significant growth, driven by the increase in biologics approvals, rising investments by vendors in expanding biomanufacturing capacities, and government initiatives aimed at boosting bioproduction. In 2021, the number of new planned clinical trials reached 5,500, an increase of 14% and 19% from 2020 and 2019, respectively. This increase in clinical trials and R&D activities is driving the growth of the fill-finish manufacturing market.
Governments worldwide are launching initiatives to support the biopharmaceutical market's growth. For instance, the government of China has implemented various measures to promote the development and commercialization of biosimilars. Similarly, countries such as Malaysia, Indonesia, Thailand, and Taiwan have established regulatory pathways for biosimilars, thereby enhancing access to biosimilar technologies. The production of biosimilars is expected to drive the demand for fill-finish manufacturing, thereby driving market growth.
Advancements in Fill-finish Manufacturing Processes
There is an increased demand for fill-finish manufacturing services in the pharmaceutical industry, driven by increased drug approvals and growth in the biopharmaceutical sector. Recent advancements in fill-finish technology have improved bioprocessing capabilities, enhancing product quality & efficiency and reducing contamination risks. Key advancements include the adoption of single-use systems, advanced barrier technologies, and robotics, among others.
A significant innovation in aseptic fill-finish technologies involves the integration of data analytics and sensor technology for real-time process control and monitoring. Continuous monitoring of critical parameters such as airflow, temperature, and pressure enables swift detection of process deviations, thereby minimizing contamination risks and optimizing process efficiency.
Table of contents
13 chapters · 147 sections · 550 pages · click to expandSegmental analysis
| Segment | Largest share (2025) | Fastest growth (2025–2032) |
|---|---|---|
| By Offering | Packaging Type | — |
| By Formulation | Parenteral | — |
| By Sterilization Process | Aseptic Processing | — |
| By Application | Small Molecules | — |
| By End User | CROs & CDMOs | — |
By Offering
- The Packaging Type Segment to Dominate the Fill-finish Manufacturing Market
- The packaging type segment is expected to account for the largest share of the fill-finish manufacturing market.
- This segment encompasses consumables like vials, pre-filled syringes, ampoules, and other containers used for drug filling.
- This segment's large market share can be attributed to the increasing utilization of vials and ampoules in vaccine packaging, the growing adoption of pre-fillable syringes and ampoules for single-dose packaging, and advancements in fill-finish technology.
- Technological advancements, such as the integration of automation & robotics in filling instruments, are crucial in reducing drug wastage, optimizing production speed, and minimizing human interventions, thereby lowering the risk of contamination.
- The integration of these technologies in fill-finish packaging solutions is anticipated to drive the growth of this segment during the forecast period.
By Formulation
- The Parenteral Segment to Dominate the Fill-finish Manufacturing Market
- The parenteral segment is expected to account for the largest share of the fill-finish manufacturing market.
- Parenteral administration is the second most prevalent drug delivery method after oral solids and liquids.
- In recent years, parenteral drugs have constituted approximately 40% of new molecular entities approved annually by the U.S. Food and Drug Administration.
- The rising development of parenteral drugs is driving the demand for advanced drug delivery devices such as pre-filled syringes, thereby boosting the adoption of fill-finish manufacturing services.
By Sterilization Process
- The aseptic processing segment is expected to account for the larger share of 60.8% of the fill-finish manufacturing market.
- Aseptic processing ensures the sterility of pharmaceutical products.
- This method employs techniques such as dry heat, fumigation, gamma radiation, and others without subjecting the materials to high temperatures.
- The increasing demand for aseptic processing is driven by the need to sterilize heat-sensitive drugs such as biologics, vaccines, and other parenteral medications.
- Additionally, the rising approvals and growing demand for vaccines and biologics are contributing to the increased demand for aseptic processing.
- According to data from the World Health Organization (WHO), global vaccine doses supplied increased from approximately 5.8 billion in 2019 to 16 billion in 2021.
By Application
- The Small Molecules Segment to Dominate the Fill-finish Manufacturing Market
- The small molecules segment is expected to account for the larger share of 55.3% of the fill-finish manufacturing market.
- This segment’s large market share can be attributed to factors such as the cost-effectiveness of small molecules and their increasing efficacy in treating various diseases, the rising prevalence of conditions like cancer & diabetes, and the increasing number of small molecules in clinical development.
- According to Lonza Group (Switzerland), small molecules account for 52% of all molecules in clinical development.
- Furthermore, the increasing complexities associated with manufacturing small molecules have increased the reliance on fill-finish manufacturing services, thereby contributing to the segment's large market share.
- However, the biologics segment is projected to register a higher CAGR of 11.1% during the forecast period.
- This growth is driven by increased funding for biologics development, rising approvals of biologic products, and investments by market players in expanding production capacities for biologics.
- Over the past five years, biologics manufacturing has grown significantly, with further growth anticipated with the advent of technologies like Bioprocessing 4.0.
- This approach harnesses the Internet of Things (IoT) for enhanced process control & efficiency.
By End User
- The CROs & CDMOs Segment to Dominate the Fill-finish Manufacturing Market
- The CROs & CDMOs segment is expected to account for the largest share of the fill-finish manufacturing market.
- This segment’s large market share can be attributed to the increasing outsourcing of drug fill-finish operations to contract companies, driven by rising product development costs and limited in-house R&D infrastructure, particularly among small and medium-sized enterprises.
- The surge in clinical trials and rapid growth in the healthcare and life sciences sectors are accelerating the outsourcing trend to ensure efficient and cost-effective drug filling.
- According to a report published by the Association for Packaging and Processing Technologies (U.S.) in 2022, 60% of pharmaceutical manufacturers currently outsource at least a portion of their operations to third-party contractors.
Geographic analysis
North America
Largest shareIn 2025, North America is expected to account for the largest share of 35.1% of the fill-finish manufacturing market. North America’s significant market share can be attributed to the presence of leading fill-finish manufacturers and major biopharmaceutical companies, substantial R&D investments, government & regulatory support promoting biopharmaceutical usage, and expansions of manufacturing capacities by pharmaceutical companies. For instance, in 2022, the U.S. accounted for approximately 45% of the global pharmaceutical market and 22% of global production. According to the International Trade Administration (ITA), the U.S. holds the largest share of the biopharmaceutical market globally, comprising about one-third of the market, and leads in biopharmaceutical manufacturing and R&D activities. The large biopharmaceutical market in North America is driving the demand for fill-finish manufacturing services, particularly for aseptic drug filling. North America to Dominate the Market in 2025
Asia-Pacific
Fastest growthHowever, the market in Asia-Pacific is projected to register the highest growth rate of 11.3% during the forecast period. Countries such as China, India, and South Korea are expected to present significant growth opportunities for vendors in the fill-finish manufacturing market. The market growth in Asia-Pacific can be attributed to several factors, including the proliferation of pharmaceutical and biopharmaceutical companies, expanding patient populations, rising disposable incomes, and growing foreign direct investments (FDIs) in the pharmaceutical and biopharmaceutical sectors. In 2015, the Government of China launched the Made in China (MIC) 2025 plan to strengthen domestic manufacturing capabilities, resulting in a significant increase in the emergence of new Chinese biopharmaceutical firms. Additionally, China has become an attractive destination for international pharmaceutical companies seeking to streamline product timelines and minimize production costs. These factors are driving the demand for fill-finish manufacturing across Asia-Pacific, thereby fueling the market’s growth.
Competitive landscape
- February 2025
Catalent, Inc. (U.S.) upgraded its capsule filling facility for Dry Powders for Inhalation and capsule blistering suites in Massachusetts, U.S., to accommodate potent drugs.
- November 2024
Gerresheimer AG (Germany) expanded its manufacturing plant for ready-to-fill (RTF) syringes in Querétaro, Mexico, with an investment of approximately USD 108 million (EUR 100 million). This expansion aims to increase the manufacturing capacity by several hundred million RTF syringes annually.
- June 2024
Corning, Inc. (U.S.) collaborated with SGD Pharma (U.S.) to establish a new glass tubing facility in Vemula, India. This collaboration enables SGD Pharma to adopt Corning's velocity vials technology, enhancing vial quality, filling-line productivity, and global delivery of injectable treatments. Manufacturing operations are expected to commence in 2025.
- May 2024
Schott Pharma (Germany) launched prefillable syringes (PFS) designed for deep-cold drugs, capable of storage and transport on dry ice at temperatures down to -100°C. These syringes are made from pharmaceutical-grade polymer.
- September 2022
Becton, Dickinson and Company (U.S.) launched the next-generation BD Effivax Glass Prefillable Syringe, setting new standards in performance for vaccine PFS. These syringes are developed in collaboration with leading pharmaceutical firms to meet the complex and evolving requirements of vaccine manufacturing.
- Syntegon Technology GmbH · Germany
- Becton
- Dickinson and Company (U.S.)
- Industria Macchine Automatiche S.p.A · Italy
- West Pharmaceutical Services, Inc. (U.S.)
- Catalent, Inc. (U.S.)
- AbbVie Inc. (U.S.)
- Gerresheimer AG · Germany
- AptarGroup, Inc. (U.S.)
- OPTIMA packaging group GmbH · Germany
- Baxter International Inc. (U.S.)
- C.H. Boehringer Sohn AG & Co. KG · Germany
- Schott Pharma AG & Co. KGaA · Germany
- SGD Pharma · France
- Stevanato Group · Italy
Frequently asked questions
The Fill-finish manufacturing market report covers the qualitative and quantitative analysis of the fill-finish manufacturing market. This report analyzes various segments of the fill-finish manufacturing market, such as offering, formulation, sterilization process, application, and end user at the regional and country levels. The report also provides insights on factors impacting market growth, regulatory analysis, pricing analysis, and Porter’s five forces analysis.
Cite this report
Meticulous Research. (2024). Fill-finish Manufacturing Market - Global Opportunity Analysis and Industry Forecast (2025-2032) (Report No. MRHC - 1041247). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/fill-finish-manufacturing-market-5930