Pharmaceutical Contract Development and Manufacturing Market (2024-2031)
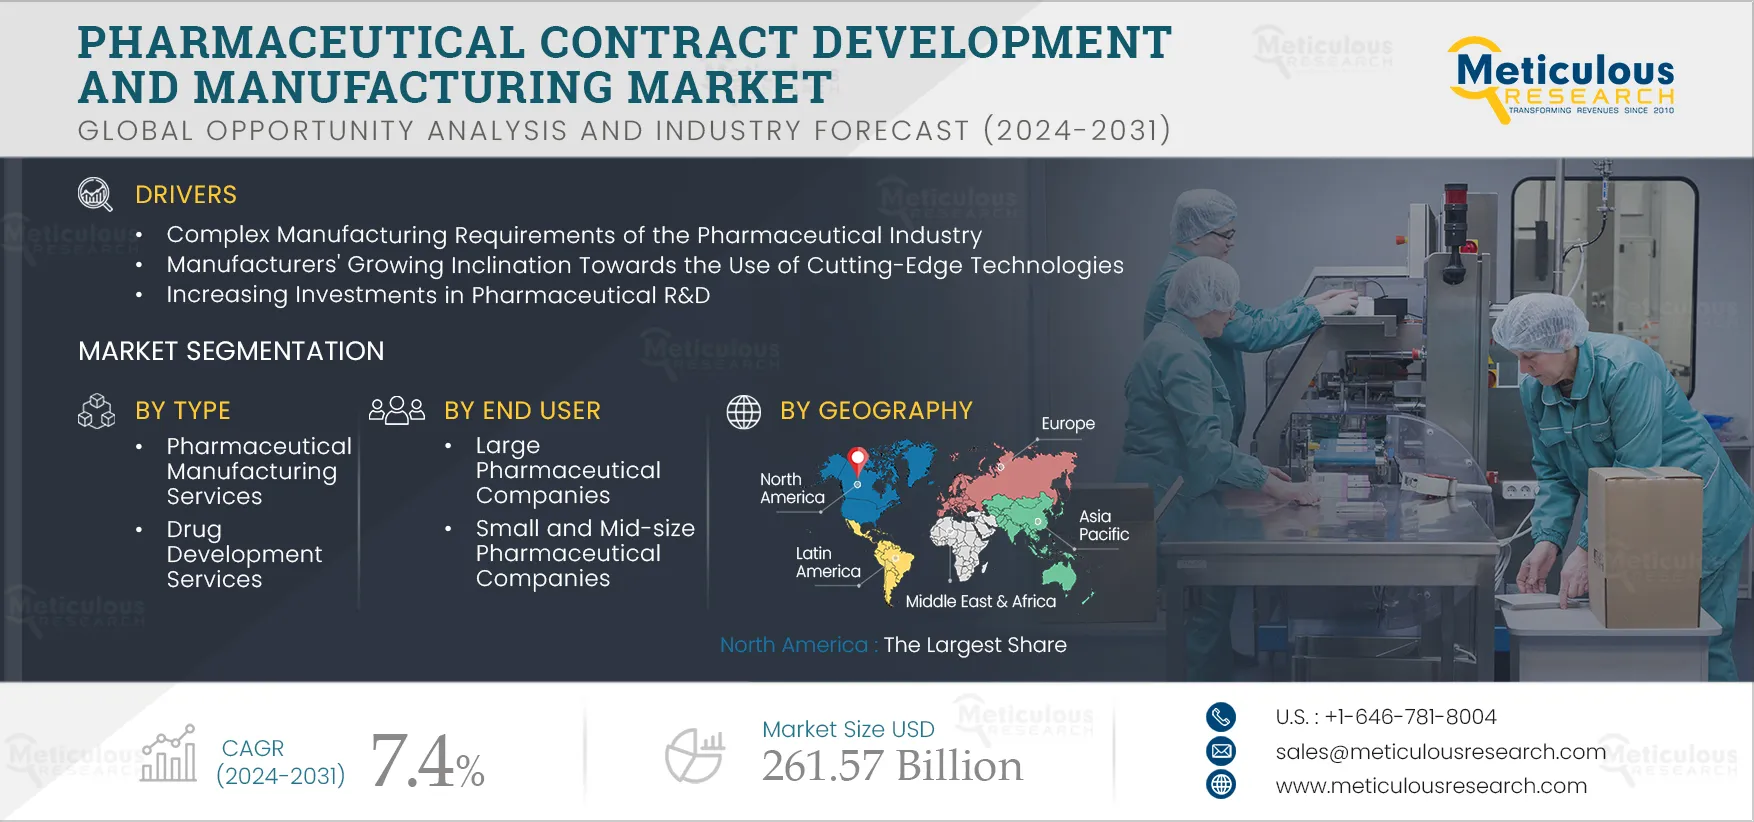
The Pharmaceutical Contract Development and Manufacturing Market was valued at $146.14 billion in 2023. This market is expected to reach $261.57 billion by 2031 from an estimated $158.27 billion in 2024, at a CAGR of 7.4% during the forecast period of 2024-2031. Pharmaceutical Contract Development and
- Published
- Aug 2024
- Pages
- 250
- Format
- PDF + Excel
- Report ID
- MRHC - 104477
- Base year
- 2023
- 2023 · BASELINE
- $146.1B
- 2031
- $261.6B
- CAGR 2024–2031
- 7.4%
2023 baseline · 2024–2031 forecast at 7.4% CAGR · hover a bar for the value
Key highlights
The Pharmaceutical Contract Development and Manufacturing Market was valued at $146.14 billion in 2023.
This market is expected to reach $261.57 billion by 2031 from an estimated $158.27 billion in 2024, at a CAGR of 7.4% during the forecast period of 2024-2031.
The pharmaceutical manufacturing services segment is expected to account for the largest share of 75.6% of the pharmaceutical contract development and manufacturing market.
The large pharmaceutical companies segment is expected to account for the largest share of 42.3% of the pharmaceutical contract development and manufacturing market.
In 2024, North America is expected to account for the largest share of 44.3% of the pharmaceutical contract development and manufacturing market.
Moreover, Asia-Pacific is poised to register the highest CAGR of 8.8% during the forecast period. The region's rapid growth can be attributed to increased awareness of overall health and treatment availability, improved healthcare infrastructure, a growing geriatric population, low-cost manufacturing advantages, rising pharmaceutical R&D expenditure, increased government funding for drug development and research, and rising healthcare spending in the region.
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | ~250 |
| Format | |
| Forecast Period | 2024-2031 |
| Base Year | 2023 |
| CAGR | 7.4% |
| Estimated Market Size (Value) | $261.57 billion by 2031 |
| Segments Covered | By Type · Pharmaceutical Manufacturing Services · Active Pharmaceutical Ingredient (API) Manufacturing Services · Finished Dosage Forms (FDF) Manufacturing Services · Parenteral/Injectable Manufacturing Services · Tablet Manufacturing Services · Capsule Manufacturing Services · Oral Liquid Manufacturing Services · Other Formulations · Drug Development Services · Biologics Manufacturing Services · Active Pharmaceutical Manufacturing Services (API) Manufacturing Services · Finished Dosage Form Manufacturing (FDF) Services · (Note: Other formulations include topical formulations, powder formulations, and modified-release dosage forms.) · By End User · Large Pharmaceutical Companies · Small & Mid-size Pharmaceutical Companies · Generic Pharmaceutical Companies |
| Countries Covered | North America (U.S. and Canada), Europe (Germany, France, U.K., Italy, Spain, Switzerland, Netherlands, Denmark, and Rest of Europe), Asia-Pacific (China, Japan, India, South Korea, Australia, Singapore, and Rest of Asia-Pacific), Latin America (Brazil, Mexico, Rest of Latin America), and Middle East & Africa. |
| Key Companies | are Lonza Group Ltd. (Switzerland), Catalent Inc. (U.S.), Patheon (Subsidiary of Thermo Fisher Scientific Inc. (U.S.), Recipharm AB (Sweden), C.H. Boehringer Sohn AG & CO. KG. (Germany), Aurobindo Pharma ltd (India), Jubilant Pharmova Limited (India), Fareva SA (Luxembourg), Vetter Pharma International GmbH (Germany), Aenova Group (Germany), WuXi Biologics Inc. (China), Piramal Enterprises Limited (India), Almac Group (U.K.), Fabbrica Italiana Sintetici S.p.A. (F.I.S.) (Italy), Samsung Biologics Co., Ltd (South Korea), Cambrex Corporation (U.S.), Siegfried Holdings AG (Switzerland), FULJIFILM Diosynth Biotechnologies (Japan), and Curia Global, Inc. (U.S.), WuXi Biologics Inc. (China), Piramal Enterprises Limited (India), Almac Group (U.K.), Fabbrica Italiana Sintetici S.p.A. (F.I.S.) (Italy), Samsung Biologics Co., Ltd (South Korea), Cambrex Corporation (U.S.), Siegfried Holdings AG (Switzerland), FULJIFILM Diosynth Biotechnologies (Japan), and Curia Global, Inc. (U.S.). |
Report overview
Segments covered: type, pharmaceutical manufacturing service, parenteral/injectable manufacturing service, tablet manufacturing service, capsule manufacturing service, oral liquid manufacturing service, other formulation, drug development service, biologics manufacturing service, end user, large pharmaceutical company, small & mid-size pharmaceutical company, generic pharmaceutical company. Regions: North America, Europe, Asia-Pacific, Latin America.
The growth of this market can be attributed to various factors, such as complex manufacturing requirements of the pharmaceutical industry, manufacturers growing inclination towards the use of cutting-edge technologies, increasing investments in pharmaceutical R&D, patent expiration, and rising demand for generic medicines and biologics. Furthermore, growing demand for cell therapies, gene therapies, and personalized medicines and growth in high potency active pharmaceutical ingredients (HPAPI) and antibody-drug conjugates (ADC) markets are expected to offer growth opportunities.
Report infographic
Market dynamics
5 factors across 3 forcesIncreasing Investments in Pharmaceutical R&D
Pharmaceutical companies are allocating significant resources for R&D purposes. This funding is mainly driven by the rising prevalence of chronic diseases due to the growing geriatric population, complexities in clinical trials, and higher failure of drugs in early-phase studies. The increasing funding for R&D purposes is leading to accelerated drug discovery and manufacturing, thereby driving the need for contract manufacturing and development organizations. According to the International Federation of Pharmaceutical Manufacturers and Associations (IFPMA), pharmaceutical R&D expenditure is expected to reach USD 213 billion by 2026 from USD 189 billion in 2022. Additionally, governments around the world are ramping up their investments in pharmaceutical and biopharmaceutical research. Various national governments have also launched initiatives to enhance pharmaceutical R&D.
For instance, in March 2023, the Canadian government allocated USD 59 million to the Canadian Critical Drug Initiative to advance drug research and commercialization. Such initiatives are anticipated to drive higher demand for pharmaceutical CDMOs to support efficient manufacturing processes.
Complex Manufacturing Requirements of the Pharmaceutical Industry
The pharmaceutical industry is driven mainly by scientific advancements and discoveries in conjunction with clinical and toxicological expertise. In addition to the complex nature of the pharmaceutical manufacturing process, multiple countries offer distinct legal safeguards for exclusive medications and production techniques, commonly referred to as intellectual property rights. Extensive government rules are in place in many countries that impact the development and approval of medications intended for commercial sale. To protect the integrity of drug manufacturing processes and the efficacy, safety, and quality of pharmaceutical goods, these countries have stringent regulations for good manufacturing practices. Due to these difficulties, pharmaceutical companies are now developing and producing medicines and biologics in collaboration with contract manufacturing and development firms.
Table of contents
10 chapters · 112 sections · 250 pages · click to expandSegmental analysis
| Segment | Largest share (2024) | Fastest growth (2024–2031) |
|---|---|---|
| By Type | Pharmaceutical Manufacturing Services | Biologics manufacturing services |
| By End User | Large Pharmaceutical Companies | — |
By Type
- The pharmaceutical manufacturing services segment is expected to account for the largest share of 75.6% of the pharmaceutical contract development and manufacturing market.
- The complex requirements of the manufacturing process, in addition to the high cost associated with drug manufacturing, are increasing the outsourcing of manufacturing services.
- Small and medium-sized pharmaceutical companies need more manufacturing infrastructure and require technical expertise.
- Small and medium-sized pharmaceutical companies can lower production costs and uphold medical quality standards by outsourcing to CDMOs.
- Pharmaceutical firms can focus on their core capabilities by using CDMOs to streamline their manufacturing process, from manufacture to secondary packaging.
- However, the biologics manufacturing services segment is estimated to register the highest CAGR of 11.1% during the forecast period.
- Biologics are becoming progressively more in demand due to their advantages, which include high activity and specificity, few side effects, and the capacity to target particular molecules.
- The need for manufacturing biologics is growing as these are used in treating infectious, autoimmune, and cardiovascular diseases, and different types of cancers.
- The U.S. Food and Drug Administration (FDA) reports that over the last five years, the approval of biologics has increased and now makes up over 25% of all drug approvals; in 2022, 15 biologics were approved out of a total of medicines, up from 13 in 2020.
- Moreover, the intricacy involved in producing biologics is leading to a rise in outsourcing to CDMOs.
- CDMO successfully handles issues including scaling up, potential for contamination, and stringent analytical testing.
- Therefore, it is anticipated that the growth of biologics manufacturing services will be aided by an increase in the percentage of approved biologics, an increase in the complexity of production, and government funding in biologics R&D.
By End User
- The large pharmaceutical companies segment is expected to account for the largest share of 42.3% of the pharmaceutical contract development and manufacturing market.
- The primary drivers accounting for the largest market share of this segment are the increasing demand for modern technology and the emphasis on expanding worldwide in business.
- Since CDMOs have facilities spread across multiple regions, they are a major source of manufacturing support for large pharmaceutical businesses looking to expand geographically.
- Due to the increasing complexity of drug research and the rising expenses of building and maintaining those facilities, large biotech and pharmaceutical companies are finding it increasingly necessary to rely on outside contract manufacturers for help running their intricate operations.
Geographic analysis
North America
Largest shareIn 2024, North America is expected to account for the largest share of 44.3% of the pharmaceutical contract development and manufacturing market. This region’s large market share is attributed to factors such as the presence of large pharmaceutical and biotechnology manufacturers, biopharmaceutical R&D funding, and rising demand for cell and gene therapies. The region's biopharmaceutical production facilities have grown as a result of the growing demand for biopharmaceuticals and supportive activities for their adoption. Drug shortages are an important concern for consumers in the United States. Drug shortages can be caused by a variety of factors, including delays, discontinuations, and issues with manufacturing and quality. The U.S. FDA reports that in 2023 there were 98 medicine shortages as opposed to 79 in 2021. Many pharmaceutical companies in the United States are depending on CDMOs to prevent medicine shortages. In 2024, North America to Dominate the Market
Asia-Pacific
Fastest growthMoreover, Asia-Pacific is poised to register the highest CAGR of 8.8% during the forecast period. The region's rapid growth can be attributed to increased awareness of overall health and treatment availability, improved healthcare infrastructure, a growing geriatric population, low-cost manufacturing advantages, rising pharmaceutical R&D expenditure, increased government funding for drug development and research, and rising healthcare spending in the region. The governments of this region are focusing on improving healthcare infrastructure in order to improve patient safety. In 2022–2023, the Government of India approved 13 foreign direct investment (FDI) proposals, which led to USD 281,400 in foreign investment in the pharmaceutical sector for brownfield projects. These government initiatives and other factors are expected to drive growth in pharmaceutical CDMOs in the Asia-Pacific region.
Competitive landscape
- July 2024
Siegfried Holdings AG Holding (Switzerland) acquired Curia Global Inc.'s CDMO location in Wisconsin (U.S.) to enhance drug substance capabilities.
- June 2024
Vetter Pharma (Germany) expanded manufacturing sites in the US and Germany. These facilities are expected to be completely operational in 2030. The development is expected to boost the company's footprint in the US market.
- March 2024
Lonza Group (Switzerland) agreed to pay USD 1.2 billion to Genentech, Inc. (US), a subsidiary of F. Hoffmann-La Roche AG, for the biologics production plant in California. The acquisition is planned to boost the company's large-scale biologics manufacturing capabilities for mammalian medicines and broaden its regional presence in the U.S.
- September 2023
Samsung Biologics (South Korea) signed an agreement with Bristol Myers Squibb (U.S.) for commercial production of antibody cancer drug substances.
- Catalent Inc.
- Thermo Fisher Scientific Inc.
- Recipharm AB
- H. Boehringer Sohn AG
- Jubilant Pharmova Limited
- Vetter Pharma International GmbH
- WuXi Biologics Inc.
- Piramal Enterprises Limited
- Samsung Biologics Co., Ltd
- Cambrex Corporation
- Curia Global, Inc.
Frequently asked questions
The pharmaceutical contract development and manufacturing market report covers the qualitative and quantitative analysis of the market. This report involves analyzing various segments of pharmaceutical contract development and manufacturing, such as type, end user, and regional and country-level studies. The report also provides insights on factors impacting market growth, regulatory analysis, factor analysis, and Porter’s five forces analysis.
Cite this report
Meticulous Research. (2024). Pharmaceutical Contract Development and Manufacturing Market - Global Opportunity Analysis And Industry Forecast (2024-2031) (Report No. MRHC - 104477). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/pharmaceutical-contract-development-and-manufacturing-market-5171