Direct-to-Device (D2D) Market (2026-2036)
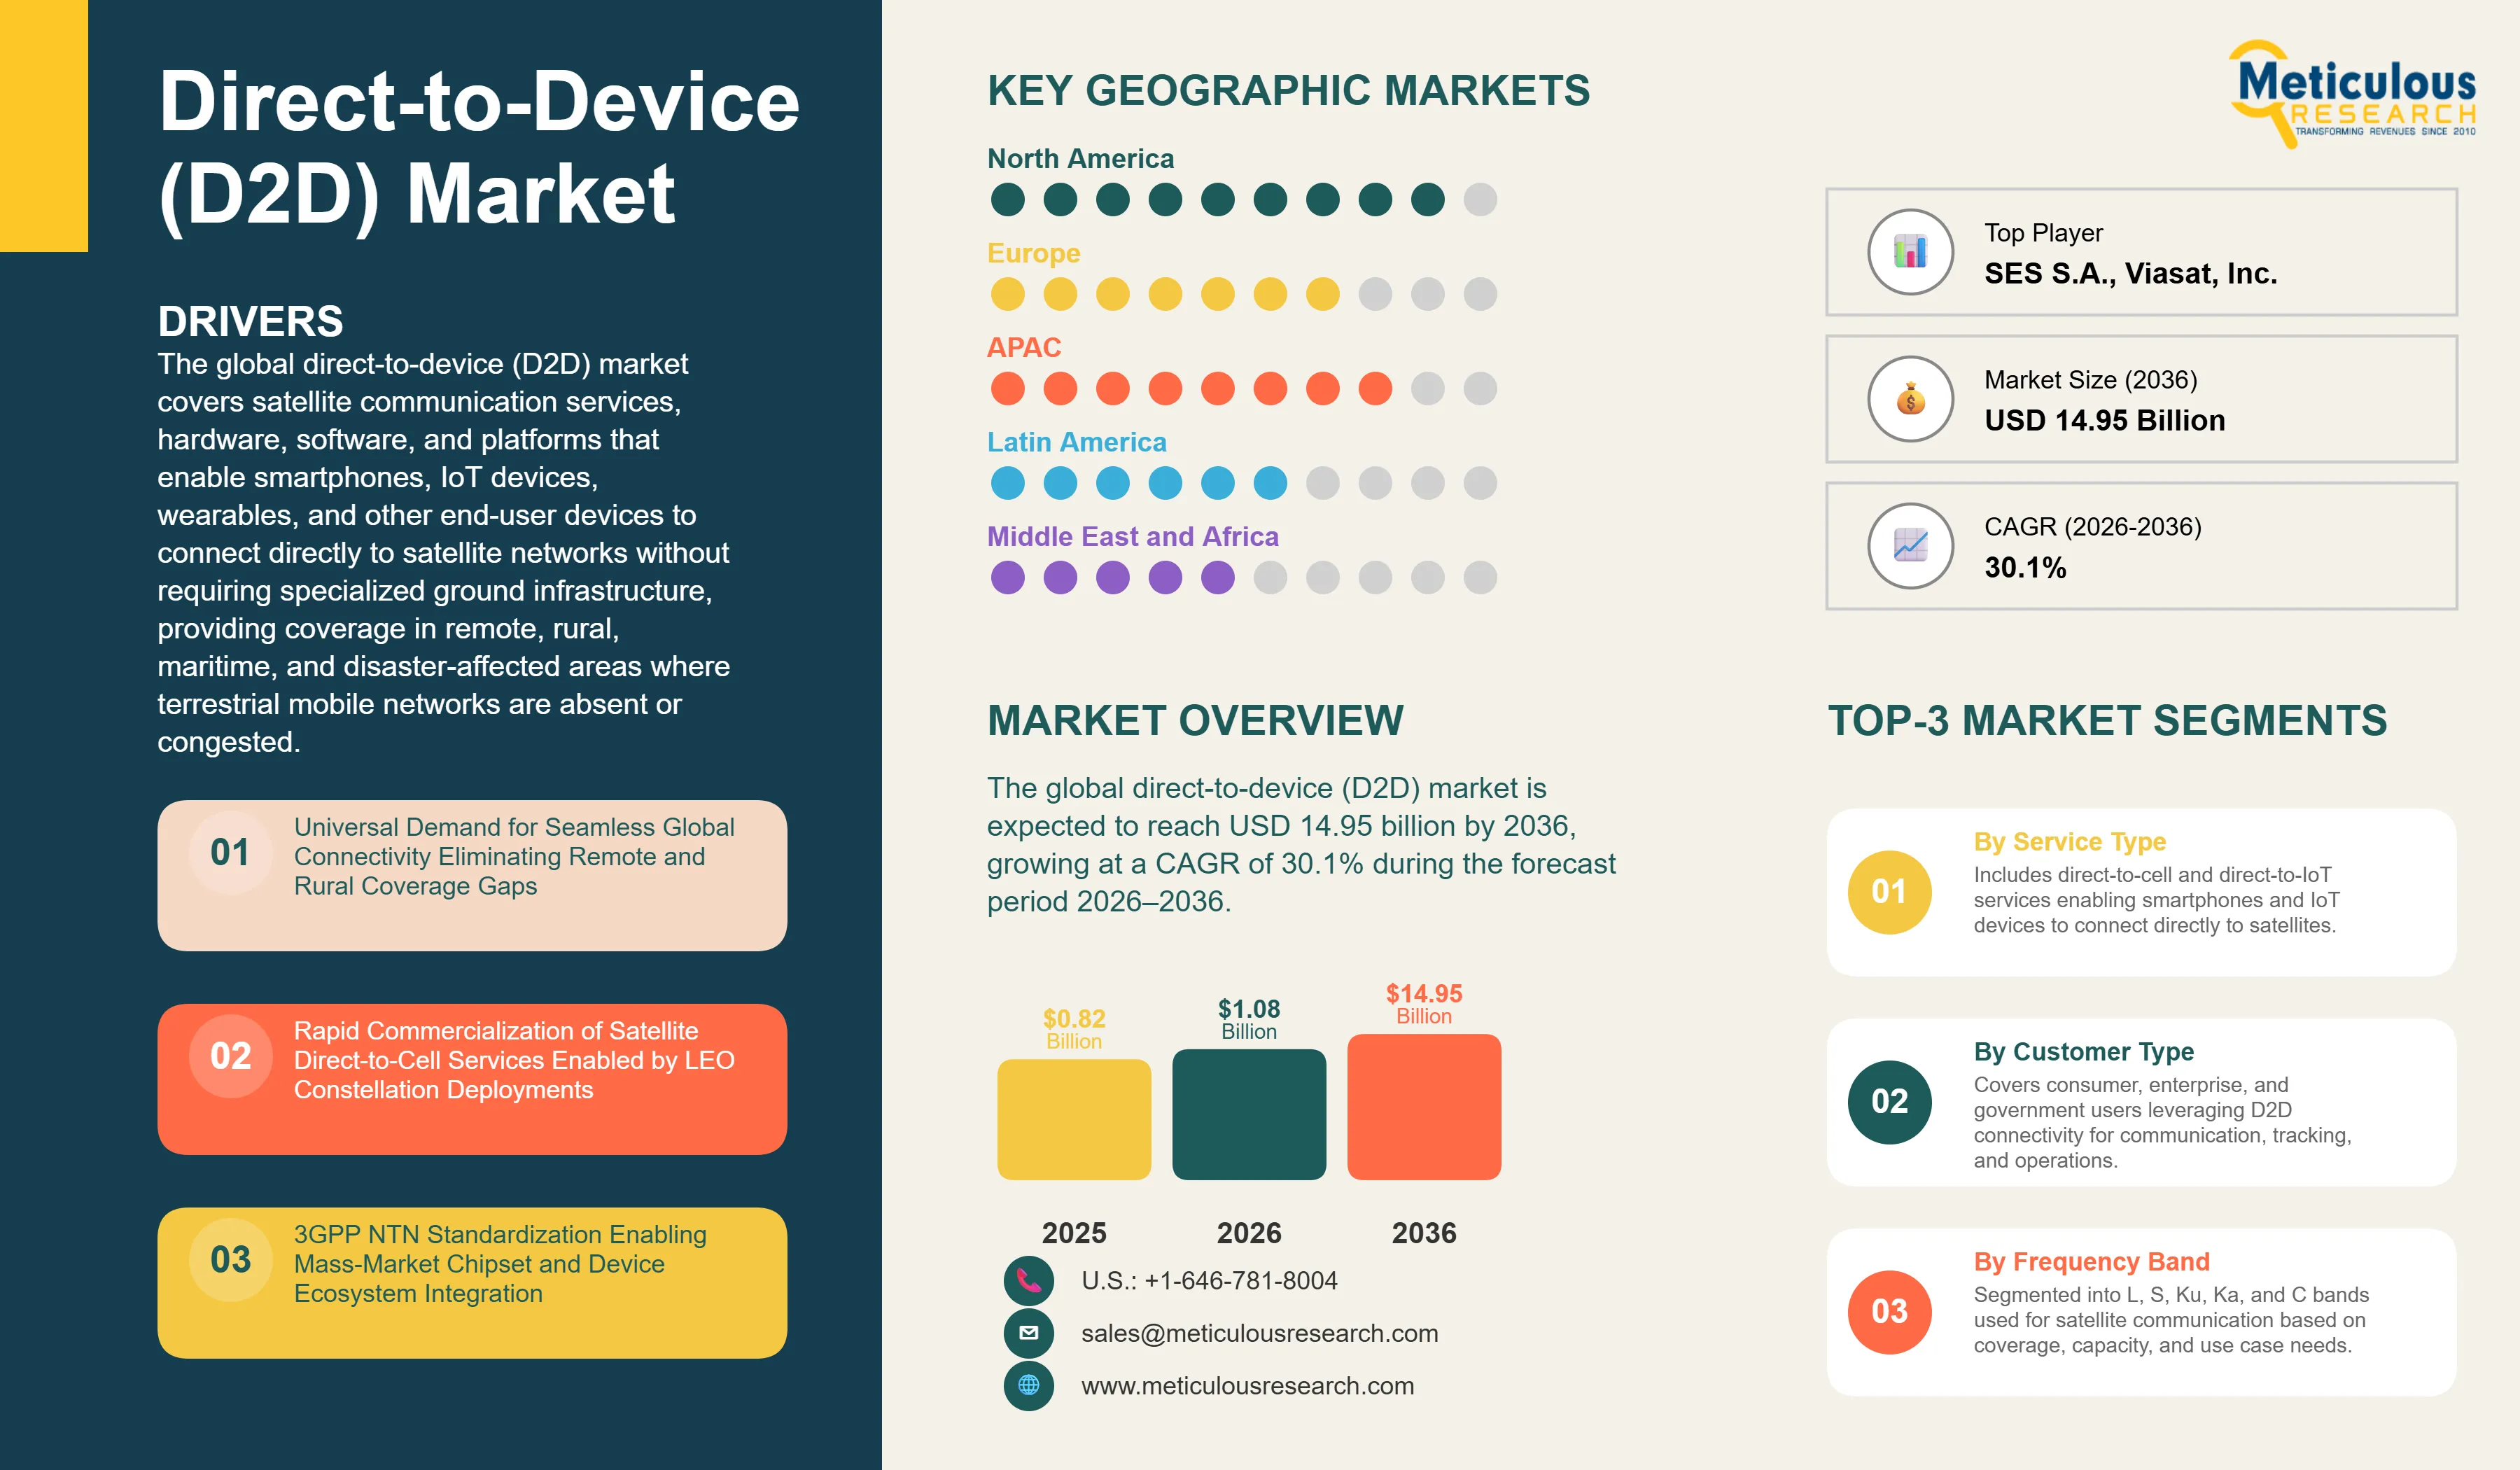
The global direct-to-device (D2D) market was valued at USD 0.82 billion in 2025. This market is expected to reach USD 14.95 billion by 2036 from an estimated USD 1.08 billion in 2026, growing at a CAGR of 30.1% during the forecast period 2026–2036.
- Published
- Apr 2026
- Pages
- 291
- Format
- PDF + Excel
- Report ID
- MR-1864
- Base year
- 2025
- 2025 · BASELINE
- $820.0M
- 2036
- $14.95B
- CAGR 2026–2036
- 30.1%
2025 baseline · 2026–2036 forecast at 30.1% CAGR · hover a bar for the value
Key highlights
The global direct-to-device (D2D) market is projected to reach USD 14.95 billion by 2036.
The market is expected to grow at a CAGR of 30.1% during the forecast period 2026–2036.
The global D2D market was valued at USD 0.82 billion in 2025 and is estimated to reach USD 1.08 billion in 2026.
North America is expected to dominate the global D2D market in 2026, driven by active commercial deployments through T-Mobile/Starlink T-Satellite, Apple/Globalstar Emergency SOS, and AST SpaceMobile/AT&T-Verizon initial broadband service in 2026.
Asia Pacific is projected to witness the fastest growth during the forecast period, driven by the world's largest mobile subscriber base exceeding 3.5 billion, the highest proportion of populations in remote and rural areas lacking terrestrial coverage, and growing digital inclusion mandates across India, Southeast Asia, and the Pacific Islands.
By service type, the direct-to-cell (D2C) segment is expected to hold the largest market share in 2026, driven by active consumer smartphone satellite connectivity deployments from SpaceX, AST SpaceMobile, and Globalstar.
By service type, the direct-to-IoT (D2IoT) segment is projected to register the highest CAGR during the forecast period, driven by massive industrial IoT connectivity demand in logistics, agriculture, maritime, and energy sectors requiring global asset tracking coverage.
By customer type, the consumer segment is expected to hold the largest market share in 2026, while the enterprise network segment is projected to register the highest CAGR during the forecast period.
By frequency band, L-band and S-band (MSS spectrum) are expected to hold the largest market share in 2026, while Ku-band and Ka-band are projected to register the highest CAGR.
By orbit, LEO is expected to account for the largest share and maintain the fastest growth through the forecast period, driven by its superior link budget for 4G-equivalent smartphone service quality.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 14.95 Billion |
| Market Size in 2026 | USD 1.08 Billion |
| Market Size in 2025 | USD 0.82 Billion |
| Revenue Growth Rate (2026–2036) | CAGR of 30.1% |
| Format | PDF, Excel & Cloud Portal · 291 pages |
| Dominating Service Type | Direct-to-Cell (D2C) |
| Fastest Growing Service Type | Direct-to-IoT (D2IoT) |
| Dominating Customer Type | Consumer |
| Fastest Growing Customer Type | Enterprise Network |
| Dominating Frequency Band | L-Band / S-Band (MSS) |
| Fastest Growing Frequency Band | Ku-Band / Ka-Band |
| Dominating Orbit | Low Earth Orbit (LEO) |
| Dominating Application | Emergency SOS & Safety Messaging |
| Fastest Growing Application | Broadband Data & Voice |
| Dominating Geography | North America |
| Fastest Growing Geography | Asia Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
Report overview
Segments covered: service type, customer type, frequency band, orbit, network architecture, end-use vertical.
The global direct-to-device (D2D) market covers satellite communication services, hardware, software, and platforms that enable smartphones, IoT devices, wearables, and other end-user devices to connect directly to satellite networks without requiring specialized ground infrastructure, providing coverage in remote, rural, maritime, and disaster-affected areas where terrestrial mobile networks are absent or congested. The D2D market is segmented into two primary service types: Direct-to-Cell (D2C), which connects smartphones and consumer handsets directly to satellite networks for emergency messaging, SMS, voice, and data services; and Direct-to-IoT (D2IoT), which connects industrial and consumer IoT sensors, trackers, and modules to satellite networks for narrowband data transmission, asset tracking, environmental monitoring, and machine-to-machine communication.
The growth of the direct-to-device (D2D) market is primarily driven by the increasing demand for ubiquitous connectivity across remote, rural, and maritime regions where terrestrial network deployment remains economically unviable. The commercialization of satellite direct-to-cell services, enabled by low Earth orbit (LEO) constellations from SpaceX (Starlink), AST SpaceMobile, Inc., and Lynk Global, Inc., is a key growth driver, allowing standard 4G and 5G smartphones to connect directly to satellites without requiring hardware modifications.
In parallel, the standardization of 3GPP Release 17 Non-Terrestrial Network (NTN) protocols is enabling interoperability between satellite and terrestrial networks, driving large-scale integration by mobile network operators and device chipset manufacturers.
However, the market faces several constraints, including complexities in spectrum allocation and regulatory approvals across jurisdictions, as well as technical limitations associated with satellite link budgets, which restrict D2D services to supplemental connectivity for high-bandwidth applications.
Additionally, the significant capital investment required to deploy and maintain LEO constellations capable of delivering continuous global coverage remains a key barrier to widespread adoption.
On the opportunity front, the increasing availability of NTN-compatible chipsets from Qualcomm Incorporated, MediaTek Inc., and Sony Group Corporation (Altair) is accelerating ecosystem readiness. Furthermore, growing adoption of D2D connectivity for enterprise IoT applications, including asset tracking across agriculture, logistics, maritime, and energy sectors, is creating high-value revenue streams. The ongoing evolution of 6G standards, with native integration of non-terrestrial capabilities, is expected to further expand the addressable market.
A key market trend is the transition from messaging-centric services to higher-bandwidth D2D capabilities, with early-stage broadband support expected to emerge toward the latter part of the decade, marking a critical inflection point in market development.
Report infographic
Market dynamics
3 factors across 1 force3GPP NTN Standards Enabling Mass-Market Device Ecosystem Integration
The standardization of Non-Terrestrial Network (NTN) protocols within the 3GPP framework is a foundational enabler for the large-scale adoption of direct-to-device (D2D) connectivity. Introduced in Release 17 and further enhanced in Release 18, with improvements in mobility management, handover efficiency, and higher-bandwidth 5G New Radio (NR) support, NTN is aligning satellite communication with existing terrestrial 4G and 5G standards.
This alignment enables seamless integration of NTN capabilities into mainstream semiconductor platforms, allowing device manufacturers to incorporate satellite connectivity into smartphones and IoT modules with limited incremental cost. As a result, D2D functionality is expected to be embedded across a broad installed base of consumer and industrial devices through standard technology upgrade cycles.
Leading semiconductor companies such as Qualcomm Incorporated, MediaTek Inc., and Sony Group Corporation (Altair) are already commercializing NTN-compatible chipsets and modules, enabling both consumer devices and industrial IoT hardware to support satellite connectivity without requiring dedicated satellite radio hardware.
Looking ahead, the evolution toward 6G, expected to see initial standardization toward the end of the decade, is anticipated to incorporate NTN capabilities at a native architectural level, driving long-term growth prospects for the D2D market through the 2030s.
MNO-Satellite Partnership Model Emerging as the Dominant Commercial Deployment Architecture
The mobile network operator–satellite operator (MNO–satellite) partnership model is emerging as the dominant commercial framework for direct-to-device (D2D) service monetization. Under this model, satellite operators provide wholesale connectivity capacity, which mobile network operators (MNOs) integrate into consumer and enterprise service plans as a premium, coverage-extension feature.
This approach leverages the MNO’s established billing relationships, subscriber base, regulatory approvals, and device distribution channels, while enabling satellite operators to monetize constellation capacity through scalable wholesale agreements. Key industry developments, including initiatives by T-Mobile US, Inc. (T-Satellite with Starlink), AT&T Inc. (D2D collaboration with AST SpaceMobile), Vodafone Group Plc (SatCo joint venture with AST SpaceMobile), and Rogers Communications Inc. (Starlink-based D2D services), highlight the growing adoption of this partnership-led model.
Within this framework, D2D connectivity is increasingly positioned as a value-added service, offered as an add-on to existing mobile plans to ensure connectivity beyond terrestrial coverage. This positioning aligns with existing MNO pricing strategies and enables large-scale commercialization through established carrier distribution channels.
Enterprise IoT Emerging as the High-ARPU Growth Engine Beyond Consumer Connectivity
While consumer emergency messaging is the initial and most visible use case for direct-to-device (D2D) connectivity, enterprise IoT applications are emerging as a key driver of long-term market growth, driven by higher average revenue per user (ARPU) and more stable demand dynamics.
Industrial sectors such as maritime (vessel tracking, crew communication, cargo monitoring), logistics and transportation (fleet and asset tracking), agriculture (precision farming, livestock monitoring, irrigation systems), energy and utilities (pipeline monitoring, remote asset management), and mining (equipment telemetry and worker safety) operate in environments where terrestrial connectivity is limited or unavailable. In these settings, the economic value of reliable connectivity is significantly higher than in consumer use cases.
Enterprise IoT deployments typically generate recurring subscription revenues ranging from low single-digit to low double-digit USD per device per month, exceeding typical consumer D2D pricing levels. In addition, long-term enterprise contracts provide predictable and high-value revenue streams, supporting the strategic importance of this segment within the overall D2D market.
Table of contents
14 chapters · 133 sections · 291 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Service Type | Direct-to-Cell | D2IoT |
| By Customer Type | Consumer | Enterprise network |
By Service Type
- The Direct-to-Cell Segment to Dominate the Global D2D Market
- The D2C segment is expected to account for the largest share of the market, driven by higher per-subscriber revenue from smartphone-based connectivity services and strong commercial momentum from mobile network operator deployments.
- Early implementations, such as satellite-enabled emergency messaging and expanding messaging/data capabilities, have demonstrated growing consumer and enterprise adoption of D2C services as a coverage-extension solution.
- The segment is further supported by ongoing service evolution toward voice, video, and limited broadband capabilities, which is expected to expand the addressable use cases and revenue potential.
- Industry estimates indicate a rapid increase in satellite-enabled smartphone users over the next decade, driven by increasing integration of NTN capabilities into mainstream devices.
- However, the D2IoT segment is projected to register the highest CAGR during the forecast period.
- This growth is driven by growing demand for reliable connectivity across industrial sectors such as logistics, agriculture, maritime, energy, and mining, where terrestrial coverage remains limited.
- Increasing availability of NTN-compatible IoT modules, offered by providers such as Skylo Technologies, Inc., Omnispace, LLC, and Iridium Communications Inc., is enabling satellite connectivity with minimal hardware modification.
By Customer Type
- The Consumer Segment to Hold the Largest Share
- The consumer segment is expected to account for the largest share of the market, driven by the scale of smartphone deployments and the widespread rollout of carrier-bundled D2D services by operators such as T-Mobile US, Inc., AT&T Inc., Verizon Communications Inc., Rogers Communications Inc., and Vodafone Group Plc.
- Consumer D2D services are increasingly positioned as a value-added coverage extension feature, enabling connectivity in areas without terrestrial network availability.
- This positioning supports large-scale adoption through existing mobile service plans and distribution channels, with growing integration of satellite connectivity into mainstream smartphone devices.
- However, the enterprise network segment is projected to register the highest CAGR during the forecast period.
- This growth is driven by higher average revenue per user (ARPU) associated with enterprise applications, where reliable connectivity in remote and mission-critical environments commands premium pricing.
- Increasing adoption of D2D solutions to support business continuity and operational efficiency across sectors such as logistics, energy, maritime, and agriculture is further accelerating segment growth.
Geographic analysis
North America
Largest shareIn 2026, North America is expected to account for the largest share of the market. This dominance is driven by the presence of leading D2D ecosystem players, including SpaceX (in partnership with T-Mobile US, Inc.), AST SpaceMobile, Inc. (with AT&T Inc. and Verizon Communications Inc.), and Globalstar, Inc. (supporting Apple Inc.). The region also benefits from a large and technologically advanced smartphone base, supportive regulatory frameworks for satellite spectrum authorization, and strong enterprise IoT adoption across sectors such as agriculture, energy, logistics, and maritime.
Asia-Pacific
Fastest growthHowever, the Asia Pacific direct-to-device (D2D) market is poised to register the highest CAGR during the forecast period. This growth is driven by the large mobile subscriber base, extensive rural and underserved populations, and increasing policy focus on digital inclusion in the region. Countries such as India are expected to play a significant role, driven by large rural connectivity demand, expanding satellite capabilities, and evolving NTN regulatory frameworks. In addition, commercial initiatives, such as collaborations involving KDDI Corporation, Rakuten Group, Inc., and Optus, are further strengthening the regional D2D ecosystem.
Competitive landscape
- SpaceX (Starlink) (U.S.)
- AST SpaceMobile, Inc. (U.S.)
- Globalstar, Inc. (U.S.)
- Iridium Communications Inc. (U.S.)
- Lynk Global, Inc. (U.S.)
- Omnispace, LLC (U.S.)
- Skylo Technologies, Inc. (U.S.)
- SES S.A. · Luxembourg
- Viasat, Inc. (U.S.)
- Qualcomm Incorporated (U.S.)
- Apple Inc. (U.S.)
- MediaTek Inc. · Taiwan
- Ericsson AB · Sweden
- Vodafone Group Plc (U.K.)
- EchoStar Corporation (U.S.)
- Space42 (UAE)
Frequently asked questions
The global D2D market is expected to reach USD 14.95 billion by 2036 from an estimated USD 1.08 billion in 2026, at a CAGR of 30.1% during the forecast period 2026–2036.
Cite this report
Meticulous Research. (2026). Direct-to-Device (D2D) Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MR-1864). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/direct-to-device-market-6547