Airborne Radars Market (2026-2036)
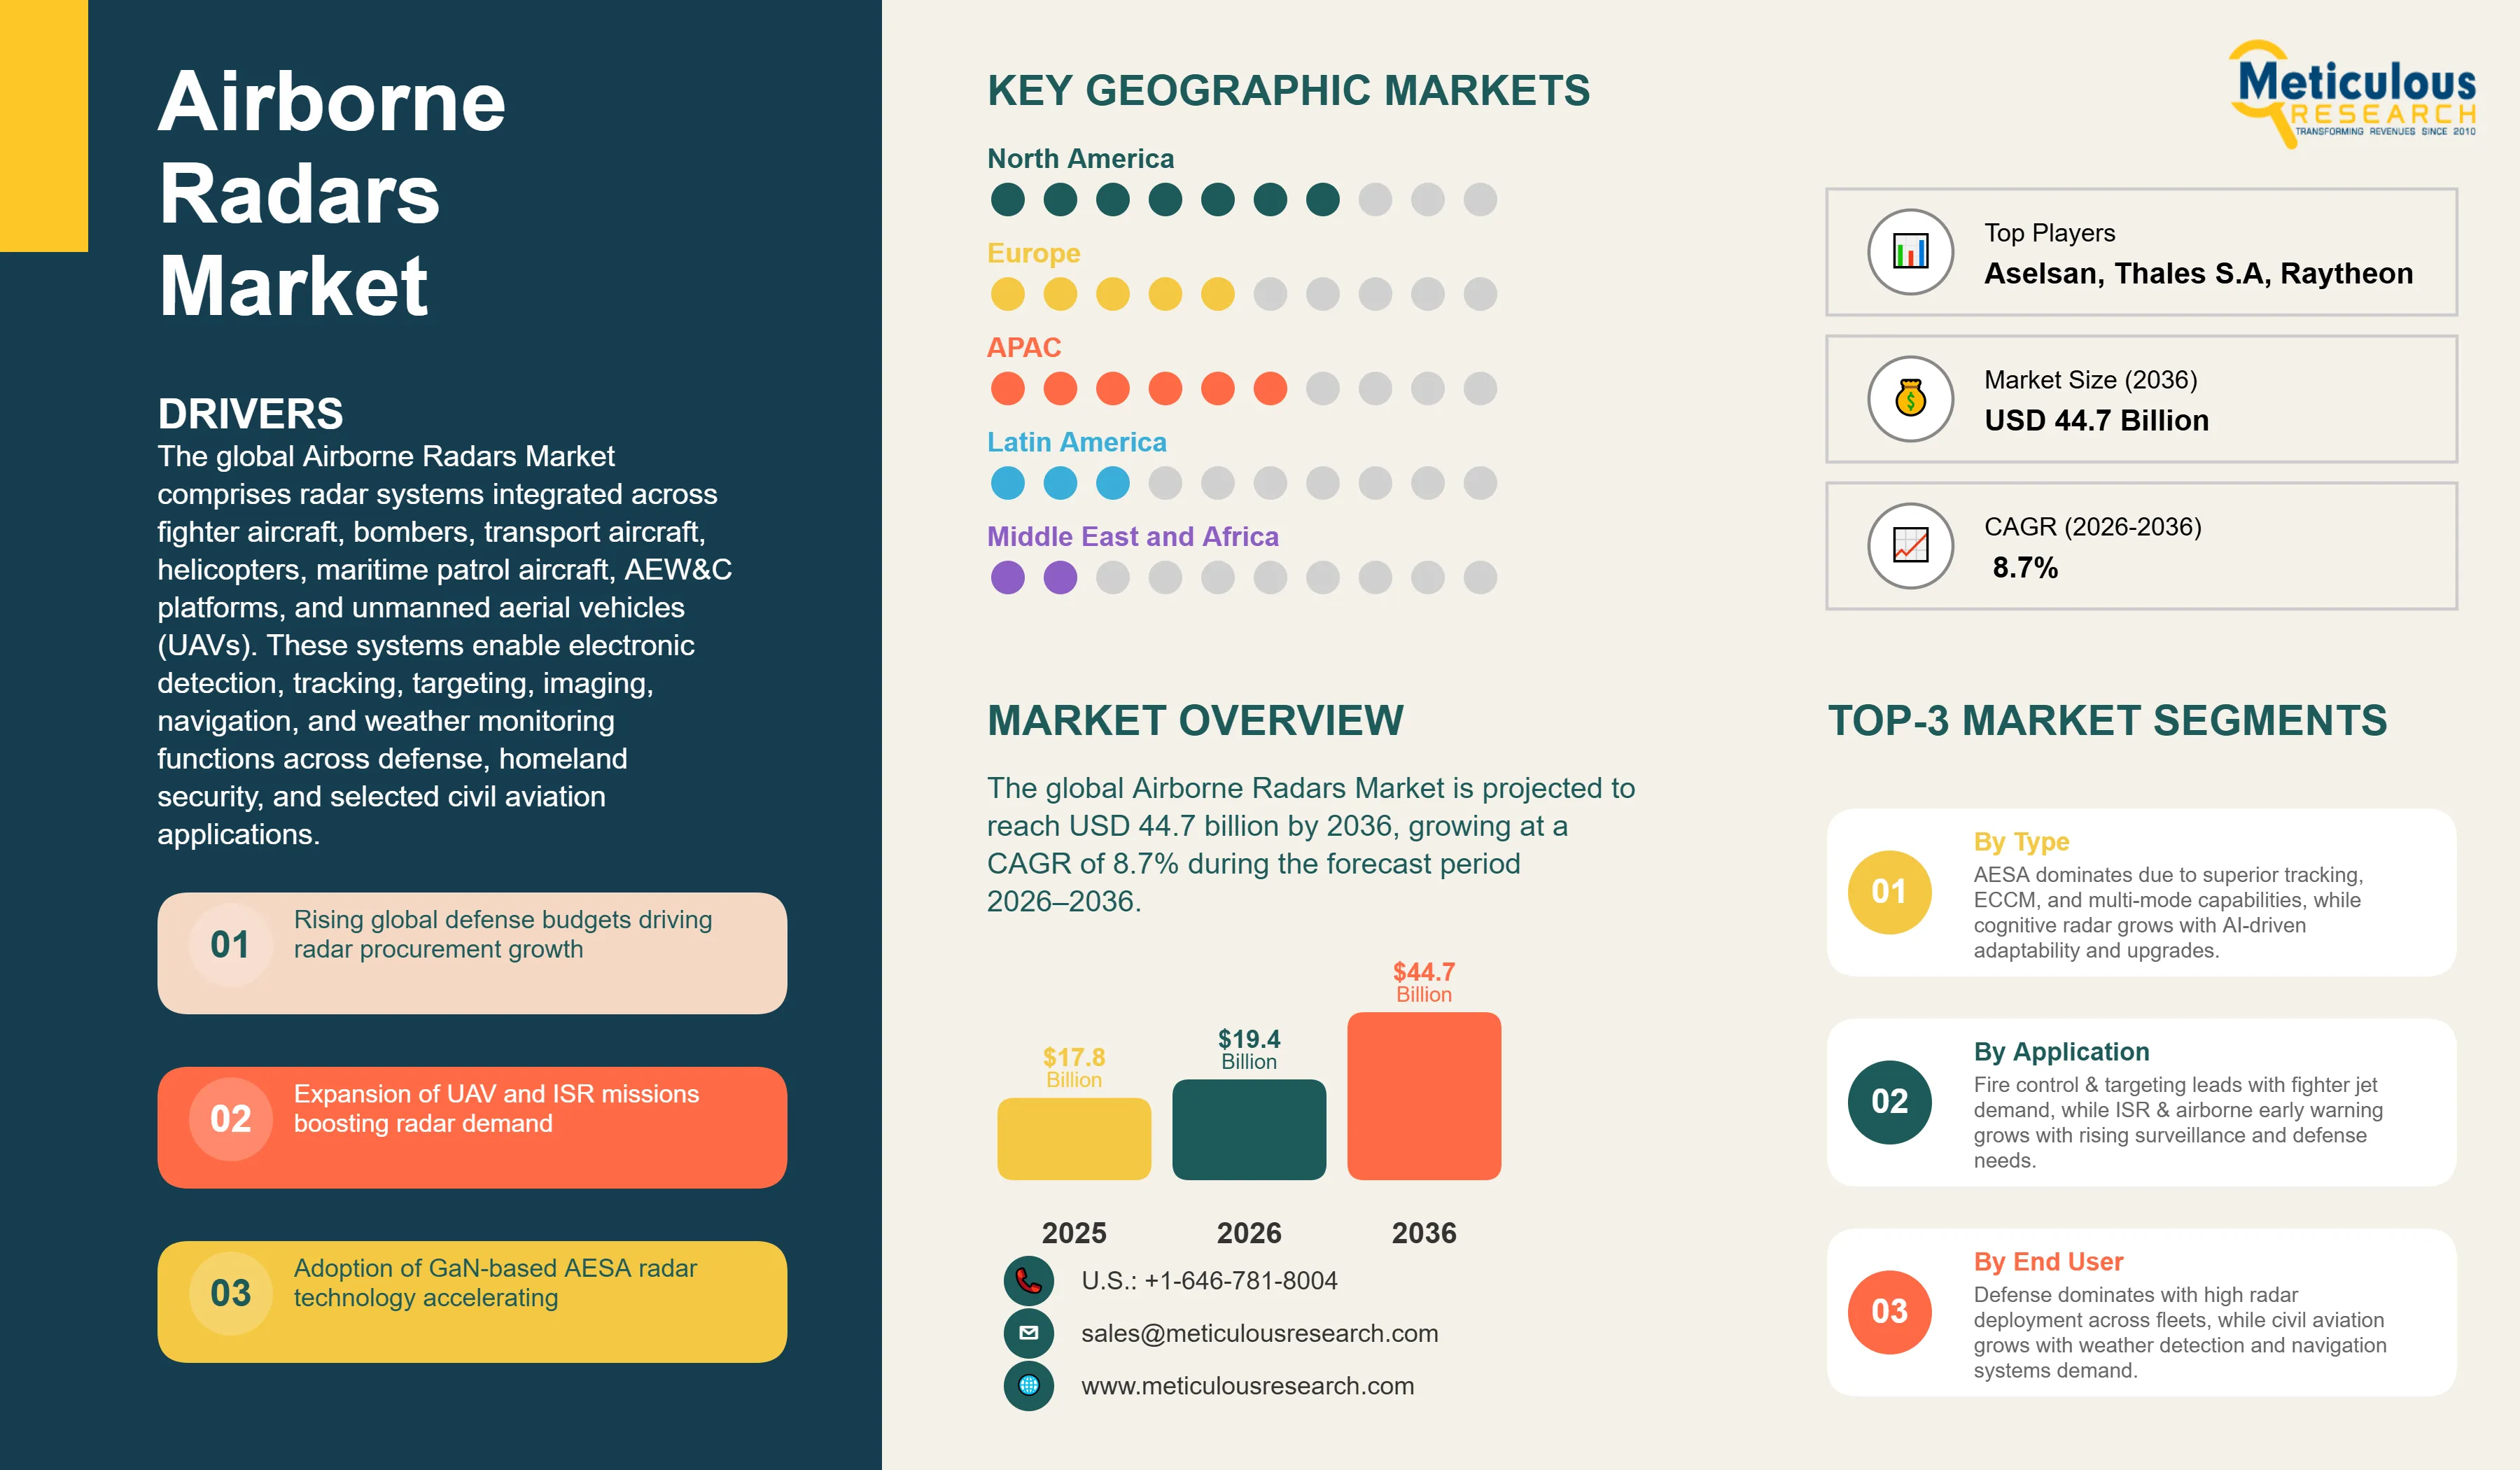
The global Airborne Radars Market was valued at USD 17.8 billion in 2025. The market is projected to reach USD 44.7 billion by 2036 from an estimated USD 19.4 billion in 2026, growing at a CAGR of 8.7% during the forecast period 2026–2036.
- Published
- Apr 2026
- Pages
- 291
- Format
- PDF + Excel
- Report ID
- MR-1920
- Base year
- 2025
- 2025 · BASELINE
- $17.80B
- 2036
- $44.70B
- CAGR 2026–2036
- 8.7%
2025 baseline · 2026–2036 forecast at 8.7% CAGR · hover a bar for the value
Key highlights
The global Airborne Radars Market is projected to reach USD 44.7 billion by 2036.
The market is expected to grow at a CAGR of 8.7% during the forecast period 2026–2036.
The global Airborne Radars Market was valued at USD 17.8 billion in 2025 and is estimated to reach USD 19.4 billion in 2026.
North America is expected to dominate the global Airborne Radars Market in 2026, accounting for around 35% of global revenue. The region continues to benefit from the world’s largest defense budget and sustained investments in combat aircraft modernization, airborne surveillance, and mission systems. Strong procurement pipelines for fighter aircraft, airborne early warning, maritime patrol, and ISR platforms are expected to continue driving demand for airborne radars in the region.
The share of North American region is further strengthened by large-scale radar retrofit programs for legacy fleets. The U.S. Air Force’s F-16 Radar Modernization Program is one of the largest such programs globally. Under Phase 3 alone, the program covers 450 active-duty and Air National Guard aircraft, in addition to the 72 radars already acquired in earlier phases.
North America is also witnessing strong contract-backed demand for AESA radar upgrades. The cumulative value of U.S. Air Force F-16 APG-83 radar contracts has reached around USD 1.6 billion. This reflects robust retrofit demand and long-term fleet sustainment spending.
Asia-Pacific is poised to grow at the fastest CAGR from 2026 to 2036. The growth of the Airborne Radars Market in the Asia Pacific is expected to be driven by increased military modernization across China, South Korea, Japan, India, and Australia. Rising regional security concerns and increasing defense allocations are supporting procurement of advanced airborne sensing and surveillance platforms.
South Korea is expected to emerge as a major growth market. The country has commenced production of an indigenous GaN-based AESA radar for the KF-21 Boramae fighter aircraft. This is expected to significantly increase regional deployment of next-generation airborne radar systems.
Japan is also expected to support regional market expansion. Continued investments in airborne early warning systems, maritime surveillance aircraft, and participation in the Global Combat Air Programme (GCAP) are expected to drive the development of next-generation radar sensors and multi-domain airborne surveillance capabilities.
India remains a key growth market within Asia-Pacific. Ongoing fighter fleet modernization, radar upgrades for the Su-30MKI, and indigenous programs such as the Virupaaksha GaN-based AESA radar are expected to drive demand for airborne radars in India.
By technology, AESA is expected to hold the largest share in 2026. This segment continues to benefit from superior multi-target tracking, rapid electronic beam steering, stronger ECCM capability, and low probability of intercept characteristics. AESA systems are now widely deployed across fifth-generation fighters and upgraded legacy aircraft.
Software-defined and cognitive radar architectures market is poised to grow at the fastest CAGR during the forecast period. The growth is being driven by the shift toward open-architecture and software-upgradable mission systems that reduce hardware replacement cycles and improve platform adaptability.
By frequency band, X-Band is expected to hold the largest market share in 2026. The segment benefits from an optimal balance of range, resolution, and compact antenna size, making it highly suitable for fighter aircraft and combat helicopter fire-control radar applications.
Ka/Ku-Band is projected to register the highest CAGR during the forecast period. Increasing deployment in UAV-mounted synthetic aperture radar (SAR), high-resolution imaging, and maritime surveillance missions is expected to drive segment growth.
By platform, fighter aircraft are expected to hold the largest market share in 2026. This is supported by continued procurement of fifth-generation fighters and extensive retrofit programs for fourth-generation fleets.
UAVs and UCAVs market is expected to grow at the fastest CAGR during the forecast period. Rising defense investments in autonomous ISR, counter-drone missions, and collaborative combat aircraft are expected to significantly drive the demand for radar integration.
By application, fire control and targeting is expected to hold the largest market share in 2026. This is mainly attributed to the dominant use of airborne fire-control radars across fighter aircraft and attack helicopters.
ISR and airborne early warning is expected to register the highest CAGR during the forecast period. Growing investments in AEW&C aircraft, maritime patrol platforms, and persistent ISR UAV programs across NATO and Indo-Pacific countries are expected to drive the growth of this market.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 44.7 Billion |
| Market Size in 2026 | USD 19.4 Billion |
| Market Size in 2025 | USD 17.8 Billion |
| Revenue Growth Rate (2026–2036) | CAGR of 8.7% |
| Format | PDF, Excel & Cloud Portal · 291 pages |
| Dominating Technology | Active Electronically Scanned Array (AESA) |
| Fastest Growing Technology | Software-Defined / Cognitive Radar |
| Dominating Frequency Band | X-Band |
| Fastest Growing Frequency Band | Ka/Ku-Band |
| Dominating Platform | Fixed-wing Military Aircraft (Fighter Jets) |
| Fastest Growing Platform | Unmanned Aerial Vehicles (UAVs/UCAVs) |
| Dominating Application | Fire Control & Targeting |
| Fastest Growing Application | ISR & Airborne Early Warning |
| Dominating End User | Defense / Military |
| Fastest Growing End User | Civil Aviation (Weather & Terrain Avoidance) |
| Dominating Geography | North America |
| Fastest Growing Geography | Asia Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
Report overview
Segments covered: technology, frequency band, range, platform, application, end user.
The global Airborne Radars Market comprises radar systems integrated across fighter aircraft, bombers, transport aircraft, helicopters, maritime patrol aircraft, AEW&C platforms, and unmanned aerial vehicles (UAVs). These systems enable electronic detection, tracking, targeting, imaging, navigation, and weather monitoring functions across defense, homeland security, and selected civil aviation applications.
The market continues to benefit from rising geopolitical tensions and accelerated military modernization programs worldwide. The ongoing Russia–Ukraine conflict, elevated Indo-Pacific security risks, and persistent instability across parts of the Middle East have led to sustained increases in defense spending and procurement activity. NATO’s long-standing defense spending benchmark of at least 2% of GDP has further supported investments in airborne surveillance and combat aviation upgrades.
A major demand driver remains the F-35 Lightning II program, which continues to represent the world’s largest single airborne radar production ecosystem. The aircraft is equipped with Northrop Grumman’s AN/APG-81 AESA radar, while the next-generation AN/APG-85 radar is scheduled for Lot 17 aircraft and beyond, entering production from 2025 onward. This transition is expected to create significant upgrade-driven revenue opportunities across advanced fire-control radar systems.
North America continues to benefit from large-scale retrofit demand. A key example is the U.S. Air Force F-16 radar modernization program, which includes deployment of the AN/APG-83 SABR AESA radar across hundreds of aircraft. The cumulative contract value for this program has reached approximately USD 1.6 billion, underscoring strong long-term demand for legacy fleet upgrades.
One of the most important technology transitions in the market is the shift from gallium arsenide (GaAs) to gallium nitride (GaN)-based transmit/receive modules. GaN technology enables higher power density, improved thermal performance, longer detection range, and stronger resistance to electronic countermeasures, while also supporting smaller and lighter radar apertures. This is increasingly important for UAVs, light combat aircraft, and collaborative combat aircraft platforms.
A notable example is Raytheon’s PhantomStrike GaN-based AESA radar, designed as a lightweight, air-cooled radar for UAVs and light combat aircraft. Poland’s selection of this radar for its 36 FA-50PL aircraft further validates the growing commercial potential of compact GaN-based airborne radar systems.
Despite strong growth prospects, the market faces some restraints. High development and procurement costs continue to limit adoption among smaller defense forces and cost-sensitive emerging markets. Advanced AESA radars involve significant capital expenditure not only at procurement but also across integration, maintenance, and lifecycle support.
Supply chain risks also remain an important challenge. Export controls on gallium and limited GaN foundry capacity continue to create lead-time uncertainty and component cost pressure for radar OEMs and defense integrators. In addition, cybersecurity risks are emerging as a critical challenge as airborne radars become increasingly integrated with network-centric warfare and digital battlespace management systems.
Report infographic
Market dynamics
2 factors across 1 forceGaN-Based AESA Technology Reaching Tipping-Point Adoption Across Fighter and UAV Platforms
One of the key trends in the global Airborne Radars Market is the rapid adoption of gallium nitride (GaN)-based AESA radar technology across new and upgrade programs. This transition shows a clear shift from legacy gallium arsenide (GaAs)-based systems toward higher-performance semiconductor architectures. The scale of deployment across multiple countries indicates that GaN is approaching a technology inflection point in airborne radar systems.
GaN offers measurable performance advantages over GaAs. It enables significantly higher power density and improved thermal efficiency, allowing radars to operate at higher output power with reduced cooling requirements. These advantages translate into longer detection ranges, stronger electronic counter-countermeasure (ECCM) performance, and improved reliability, while also enabling smaller and lighter radar apertures suitable for UAV and light combat platforms.
In the U.S., Raytheon completed the first flight test of its PhantomStrike GaN-based AESA radar on May 6, 2025. The radar is designed as a compact, air-cooled system weighing ~68 kg (150 lbs), significantly lighter than traditional fighter-class AESA radars. This positions it for deployment across UAVs, light combat aircraft, and collaborative combat aircraft platforms.
The U.S. Air Force continues to allocate funding toward advanced radar upgrades. The FY2026 budget includes approximately USD 90 million for F-22 Raptor modernization, including radar and sensor enhancements. This reflects continued investment in high-performance airborne sensing capabilities.
At the platform level, the F-35 program remains the largest airborne radar production ecosystem globally. More than 3,000 AN/APG-81 AESA radars are expected across the planned F-35 fleet, with production extending into the 2030s. The transition to the AN/APG-85 radar from Lot 17 (production beginning 2025) represents a major upgrade cycle within this installed base.
North America is also witnessing large-scale retrofit demand. The U.S. Air Force F-16 radar modernization program covers over 600 aircraft, including active-duty and Air National Guard fleets. The program’s cumulative contract value has reached approximately USD 1.6 billion, highlighting the scale of AESA upgrade demand.
Raytheon is further expanding GaN deployment through its PhantomStrike radar. Poland has selected the system for 36 FA-50PL aircraft, marking one of the first operational deployments of a compact GaN AESA radar in light combat aircraft.
Asia-Pacific is emerging as a major growth center for GaN radar adoption. India’s DRDO is advancing the Virupaksha AESA radar for Su-30MKI upgrades, building on indigenous AESA development programs. South Korea’s Hanwha Systems has initiated production of an indigenous AESA radar for the KF-21 Boramae fighter in 2025, marking a key milestone in domestic radar capability development.
At the system level, GaN-based AESA radars are increasingly being designed for multi-role functionality, including fire control, ISR, electronic warfare support, and high-resolution SAR imaging. Their ability to support simultaneous multi-mode operations is becoming critical for next-generation air combat and network-centric warfare environments.
The simultaneous deployment of GaN radar programs across the U.S., Europe, and Asia-Pacific confirms a clear industry-wide transition. GaN is no longer limited to niche or high-end applications. It is rapidly becoming the baseline technology for new airborne AESA radar systems, with implications for both performance benchmarks and lifecycle cost structures over the next decade.
Sixth-Generation Combat Air Programs and UAV Loyal Wingman Driving Long-term Radar System Requirements
The simultaneous development of sixth-generation combat air programs and unmanned collaborative combat aircraft is emerging as a long-term demand driver for next-generation airborne radar systems. These programs are expected to drive radar innovation and procurement cycles well into the 2030s and beyond, supported by multi-decade defense investments and platform development timelines.
Two major multinational sixth-generation programs are currently at the center of this transition. The Global Combat Air Programme (GCAP), led by the UK, Japan, and Italy, and the Future Combat Air System (FCAS), led by France, Germany, and Spain, are both progressing through advanced development phases. Both programs place sensor fusion and advanced radar systems at the core of their operational architecture.
GCAP formally established its joint government–industry structure in 2025, with BAE Systems, Leonardo, and Japan Aircraft Industrial Enhancement Co. (JAIEC) forming a joint venture with equal 33.3% ownership stakes. The program aims to deliver a sixth-generation combat aircraft by 2035, supported by a fully integrated system-of-systems architecture including unmanned platforms.
The program is expected to involve over USD 40 billion in cumulative development spending through 2035, with total lifecycle investments likely exceeding USD 60 billion as partner nations scale production and system integration. This level of investment indicates the critical role of radar systems in enabling sensor fusion, distributed sensing, and multi-domain combat operations.
Japan’s participation is strategically aligned with regional security dynamics, mainly in response to evolving threats in the Indo-Pacific. The program includes co-development of next-generation radar sensors, reinforcing the importance of radar as a core mission system within sixth-generation platforms.
The Future Combat Air System (FCAS) program similarly emphasizes distributed sensing and network-centric warfare. Airbus-led Remote Carrier unmanned systems are designed to operate alongside manned fighter aircraft, requiring compact, high-performance radar systems capable of operating within constrained size, weight, and power (SWaP) environments.
In parallel, the U.S. is advancing its Collaborative Combat Aircraft (CCA) program, which is expected to procure more than 1,000 autonomous aircraft over time to operate alongside platforms such as the F-35 and Next Generation Air Dominance (NGAD) fighter. These systems will rely heavily on onboard and networked sensors, including lightweight AESA radar systems, for autonomous mission execution.
This shift is creating a new product segment within the Airborne Radars Market. There is growing demand for compact, cost-optimized GaN-based AESA radars designed specifically for UAVs and loyal wingman platforms. These radars must meet strict SWaP constraints while still delivering multi-mode functionality, including target detection, tracking, SAR imaging, and electronic warfare support. Raytheon’s PhantomStrike radar is a key example of this emerging category. The system weighs approximately 68 kg (150 lbs) and is designed as an air-cooled AESA radar, eliminating the need for complex liquid cooling systems. This significantly reduces integration complexity and lifecycle costs, making it suitable for large-scale deployment across collaborative combat aircraft fleets.
The combination of sixth-generation combat air programs and unmanned systems is reshaping radar requirements. Future airborne radar systems will need to support distributed sensing, AI-enabled data processing, multi-platform interoperability, and autonomous decision support. As a result, radar is evolving from a standalone sensor into a core node within a networked combat ecosystem.
This transformation is expected to drive strong demand for advanced airborne radar systems over the next decade, with increasing emphasis on scalability, software-defined architectures, and integration across manned-unmanned teaming environments.
Table of contents
14 chapters · 160 sections · 291 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Technology | AESA | Software-defined and cognitive radar systems |
| By Platform | Fighter Aircraft | UAVs and UCAVs |
| By Application | Fire Control & Targeting | — |
By Technology
- AESA to Dominate the Global Airborne Radars Market
- AESA is expected to account for the largest share of the global Airborne Radars Market.
- The segment is projected to maintain its dominance due to its status as the standard technology for new airborne radar programs, particularly in military aviation.
- AESA radars offer key advantages over MSA and PESA systems.
- These include simultaneous multi-mode operation, electronic beam steering, low probability of intercept (LPI), and high reliability due to distributed T/R modules.
- These capabilities support applications across fire control, ISR, SAR imaging, and electronic warfare.
- At the program level, the F-35 AN/APG-81 radar remains the largest AESA production program, with over 3,000 units expected.
- Retrofit demand is also strong, with the APG-83 SABR deployed across more than 600 U.S. Air Force F-16 aircraft, with cumulative contracts of ~USD 1.6 billion.
- AESA adoption is also expanding across UAVs and next-generation platforms.
- However, software-defined and cognitive radar systems are expected to register the highest CAGR during the forecast period.
- These systems enable software-based upgrades, AI-driven adaptability, and real-time spectrum management, making them critical for future electronic warfare environments.
- Frequency Band Insights
- X-Band to Account for the Largest Share
- X-Band is expected to account for the largest share of the global Airborne Radars Market.
- The segment benefits from an optimal balance of detection range, angular resolution, target discrimination, and compact antenna size, making it the preferred band for fighter aircraft fire-control and multi-role radar systems.
- X-Band radars account for approximately 45–50% share of the overall airborne fire-control radar deployments, reflecting their widespread use across combat aircraft.
- Leading systems such as the AN/APG-81 (F-35), APG-83 SABR (F-16), APG-82(V)1 (F-15E), and PhantomStrike AESA radar all operate in the X-Band frequency range, reinforcing its dominance across both new production and retrofit programs.
- However, Ku/Ka-Band is projected to register the highest CAGR during the forecast period.
- These higher-frequency bands (Ku: ~12–18 GHz; Ka: ~27–40 GHz) enable significantly higher-resolution SAR/ISAR imaging, making them increasingly suitable for UAV-mounted radars, maritime surveillance, and precision terrain mapping.
- The rapid expansion of UAV-based ISR missions is driving demand for compact, high-resolution Ku/Ka-Band radars, mainly in applications where SWaP constraints and imaging accuracy are critical.
By Platform
- Fighter Aircraft to Hold the Largest Share
- Fighter aircraft are expected to account for the largest share of the global Airborne Radars Market.
- This is driven by strong procurement of fifth-generation platforms and large-scale AESA radar upgrades across legacy fleets.
- The F-35 program remains the primary driver, with Lockheed Martin targeting ~156 aircraft annually, with peak deliveries in the range of 175–190 aircraft per year.
- The program includes 17 partner and FMS customer nations, supporting a sustained global radar production pipeline through the 2030s.
- In parallel, a large installed base of fourth-generation fighters, such as F-16, F-15, F/A-18, Eurofighter Typhoon, Dassault Rafale, Saab Gripen, MiG-29, and Su-27 variants, is undergoing AESA radar upgrades, further reinforcing segment dominance.
- However, UAVs and UCAVs are projected to register the highest CAGR from 2026 to 2036.
- The growth of this market is driven by increasing deployment of radar-equipped unmanned systems across ISR, maritime surveillance, counter-drone, and collaborative combat missions.
- Program-level investments highlight this trend.
- The MQ-4C Triton program includes ~USD 376.4 million in FY2026 funding, while the MQ-25 Stingray program is supported by ~USD 305.5 million in FY2026 funding.
- These investments reflect the growing scale of radar-enabled UAV procurement.
- The increasing integration of SAR, maritime surveillance, and targeting radars on MALE and HALE UAV platforms is expected to further drive demand, mainly in applications requiring persistent surveillance and autonomous mission capability.
By Application
- Fire Control & Targeting to Hold the Largest Share
- Fire control & targeting is expected to account for the largest share of the global Airborne Radars Market.
- The large share of this segment is driven by high procurement volumes across global fighter aircraft fleets and the premium value of fire control radar systems.
- The segment benefits from both new production and retrofit demand.
- Ongoing manufacturing of fifth-generation aircraft, mainly the F-35, and large-scale AESA upgrades across fourth-generation fleets continue to drive demand.
- Fire control radars command the highest per-unit pricing in the market due to their complexity, weapon system integration, and stringent qualification requirements.
- For example, a U.S. Air Force contract for 31 APG-83 AESA radars was valued at ~USD 88.24 million, highlighting the strong unit economics of this segment.
- However, the Airborne Radars Market for the ISR and airborne early warning application segment is projected to grow at the fastest CAGR from 2026 to 2036, driven by increasing investments in persistent surveillance, maritime domain awareness, and network-centric battle management systems.
- High-value programs continue to support this segment.
- Platforms such as the Boeing E-7A Wedgetail and Saab GlobalEye are witnessing growing international adoption.
- In addition, modernization initiatives to replace aging AWACS fleets are creating long-term procurement opportunities.
- The expansion of ISR missions is also visible in UAV deployments.
- NATO’s RQ-4D Phoenix deployment in Finland in 2025 highlights the increasing use of radar-equipped HALE UAVs for persistent surveillance across contested regions.
Geographic analysis
North America
Largest shareIn 2026, North America is expected to account for the largest share of the global Airborne Radars Market, at approximately 35% of global revenue. The region’s dominance is driven by the scale and technological sophistication of U.S. defense procurement programs. The U.S. Department of Defense operates the world’s most extensive airborne radar portfolio. Key programs include the F-35 AN/APG-81 production (with over 3,000 units expected) and the transition to the AN/APG-85 from Lot 17 (2025 onward). Retrofit demand is also significant, with the F-16 APG-83 upgrade covering over 600 aircraft, with cumulative contracts of ~USD 1.6 billion. Additional programs include the F-15E/EX APG-82 radar, ongoing F-22 radar upgrades, and the B-21 Raider, which is expected to incorporate advanced AESA radar systems. The U.S. Navy further strengthens regional demand through programs such as the F/A-18E/F APG-79, supported by a ~USD 603 million radar support contract (2025), along with the E-2D Advanced Hawkeye, P-8A Poseidon, and MQ-4C Triton surveillance radar systems. Canada contributes through F-35A procurement and continued modernization of legacy fleets. North America U.S. Mexico
Europe
Europe holds the second-largest share, driven by widespread AESA radar upgrades across NATO air forces. Key programs include the Eurofighter Typhoon Captor-E AESA radar, developed by the Euroradar consortium, the Rafale F4 upgrade with the RBE2-AA AESA radar, and continued Gripen E/F production with advanced AESA radar systems. In addition, the Global Combat Air Programme is driving long-term investment in next-generation radar technologies across the UK and Italy industrial base. U.K. Germany France Italy Sweden Spain Rest of Europe
Asia-Pacific
Fastest growthThe Asia Pacific Airborne Radars Market is poised to grow at the fastest CAGR during the forecast period, driven by large-scale modernization programs across multiple defense markets. South Korea’s KF-21 Boramae program and FA-50 radar upgrades represent parallel indigenous and export-driven AESA deployments. Japan’s FY2025 defense budget of ~JPY 7.95 trillion (USD ~50+ billion), combined with GCAP participation and maritime surveillance investments, further drives the strong demand in the region. India’s Su-30MKI upgrade program, covering ~300 aircraft, alongside Tejas MkI/MkII radar programs, represents one of the largest modernization efforts in the region. China continues to expand indigenous AESA radar deployment across platforms such as J-20, J-16, and J-10C, while Taiwan’s F-16V upgrade program with APG-83 AESA radar reflects continued investment driven by regional security dynamics. Overall, the Asia Pacific Airborne Radars Market is expected to grow at the fastest CAGR through 2036, driven by rising defense budgets, indigenous radar development, and strong fighter and UAV procurement. By Geography (Revenue, USD Billion, 2026–2036) Australia Rest of Asia Pacific
Middle East & Africa
Israel Saudi Arabia UAE Rest of Middle East & Africa
Competitive landscape
- Northrop Grumman Corporation
- RTX Corporation / Raytheon
- Lockheed Martin Corporation
- Leonardo S.p.A
- Thales S.A.
- Saab AB
- BAE Systems plc
- Hensoldt AG
- Israel Aerospace Industries / Elta Systems
- Elbit Systems Ltd.
- L3Harris Technologies, Inc.
- Mitsubishi Electric Corporation
- Hanwha Systems
- Aselsan A.Ş
- Indra Sistemas S.A.
- Toshiba Corporation
- China Electronics Technology Group Corporation
- Aviation Industry Corporation of China
- Defence Research and Development Organisation
Frequently asked questions
The global Airborne Radars Market is expected to reach USD 44.7 billion by 2036 from an estimated USD 19.4 billion in 2026, at a CAGR of 8.7% during the forecast period 2026–2036.
Cite this report
Meticulous Research. (2026). Airborne Radars Market - Global Opportunity Analysis And Industry Forecasts (2026-2036) (Report No. MR-1920). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/airborne-radars-market-6603