LEO Satellite Market (2026-2036)
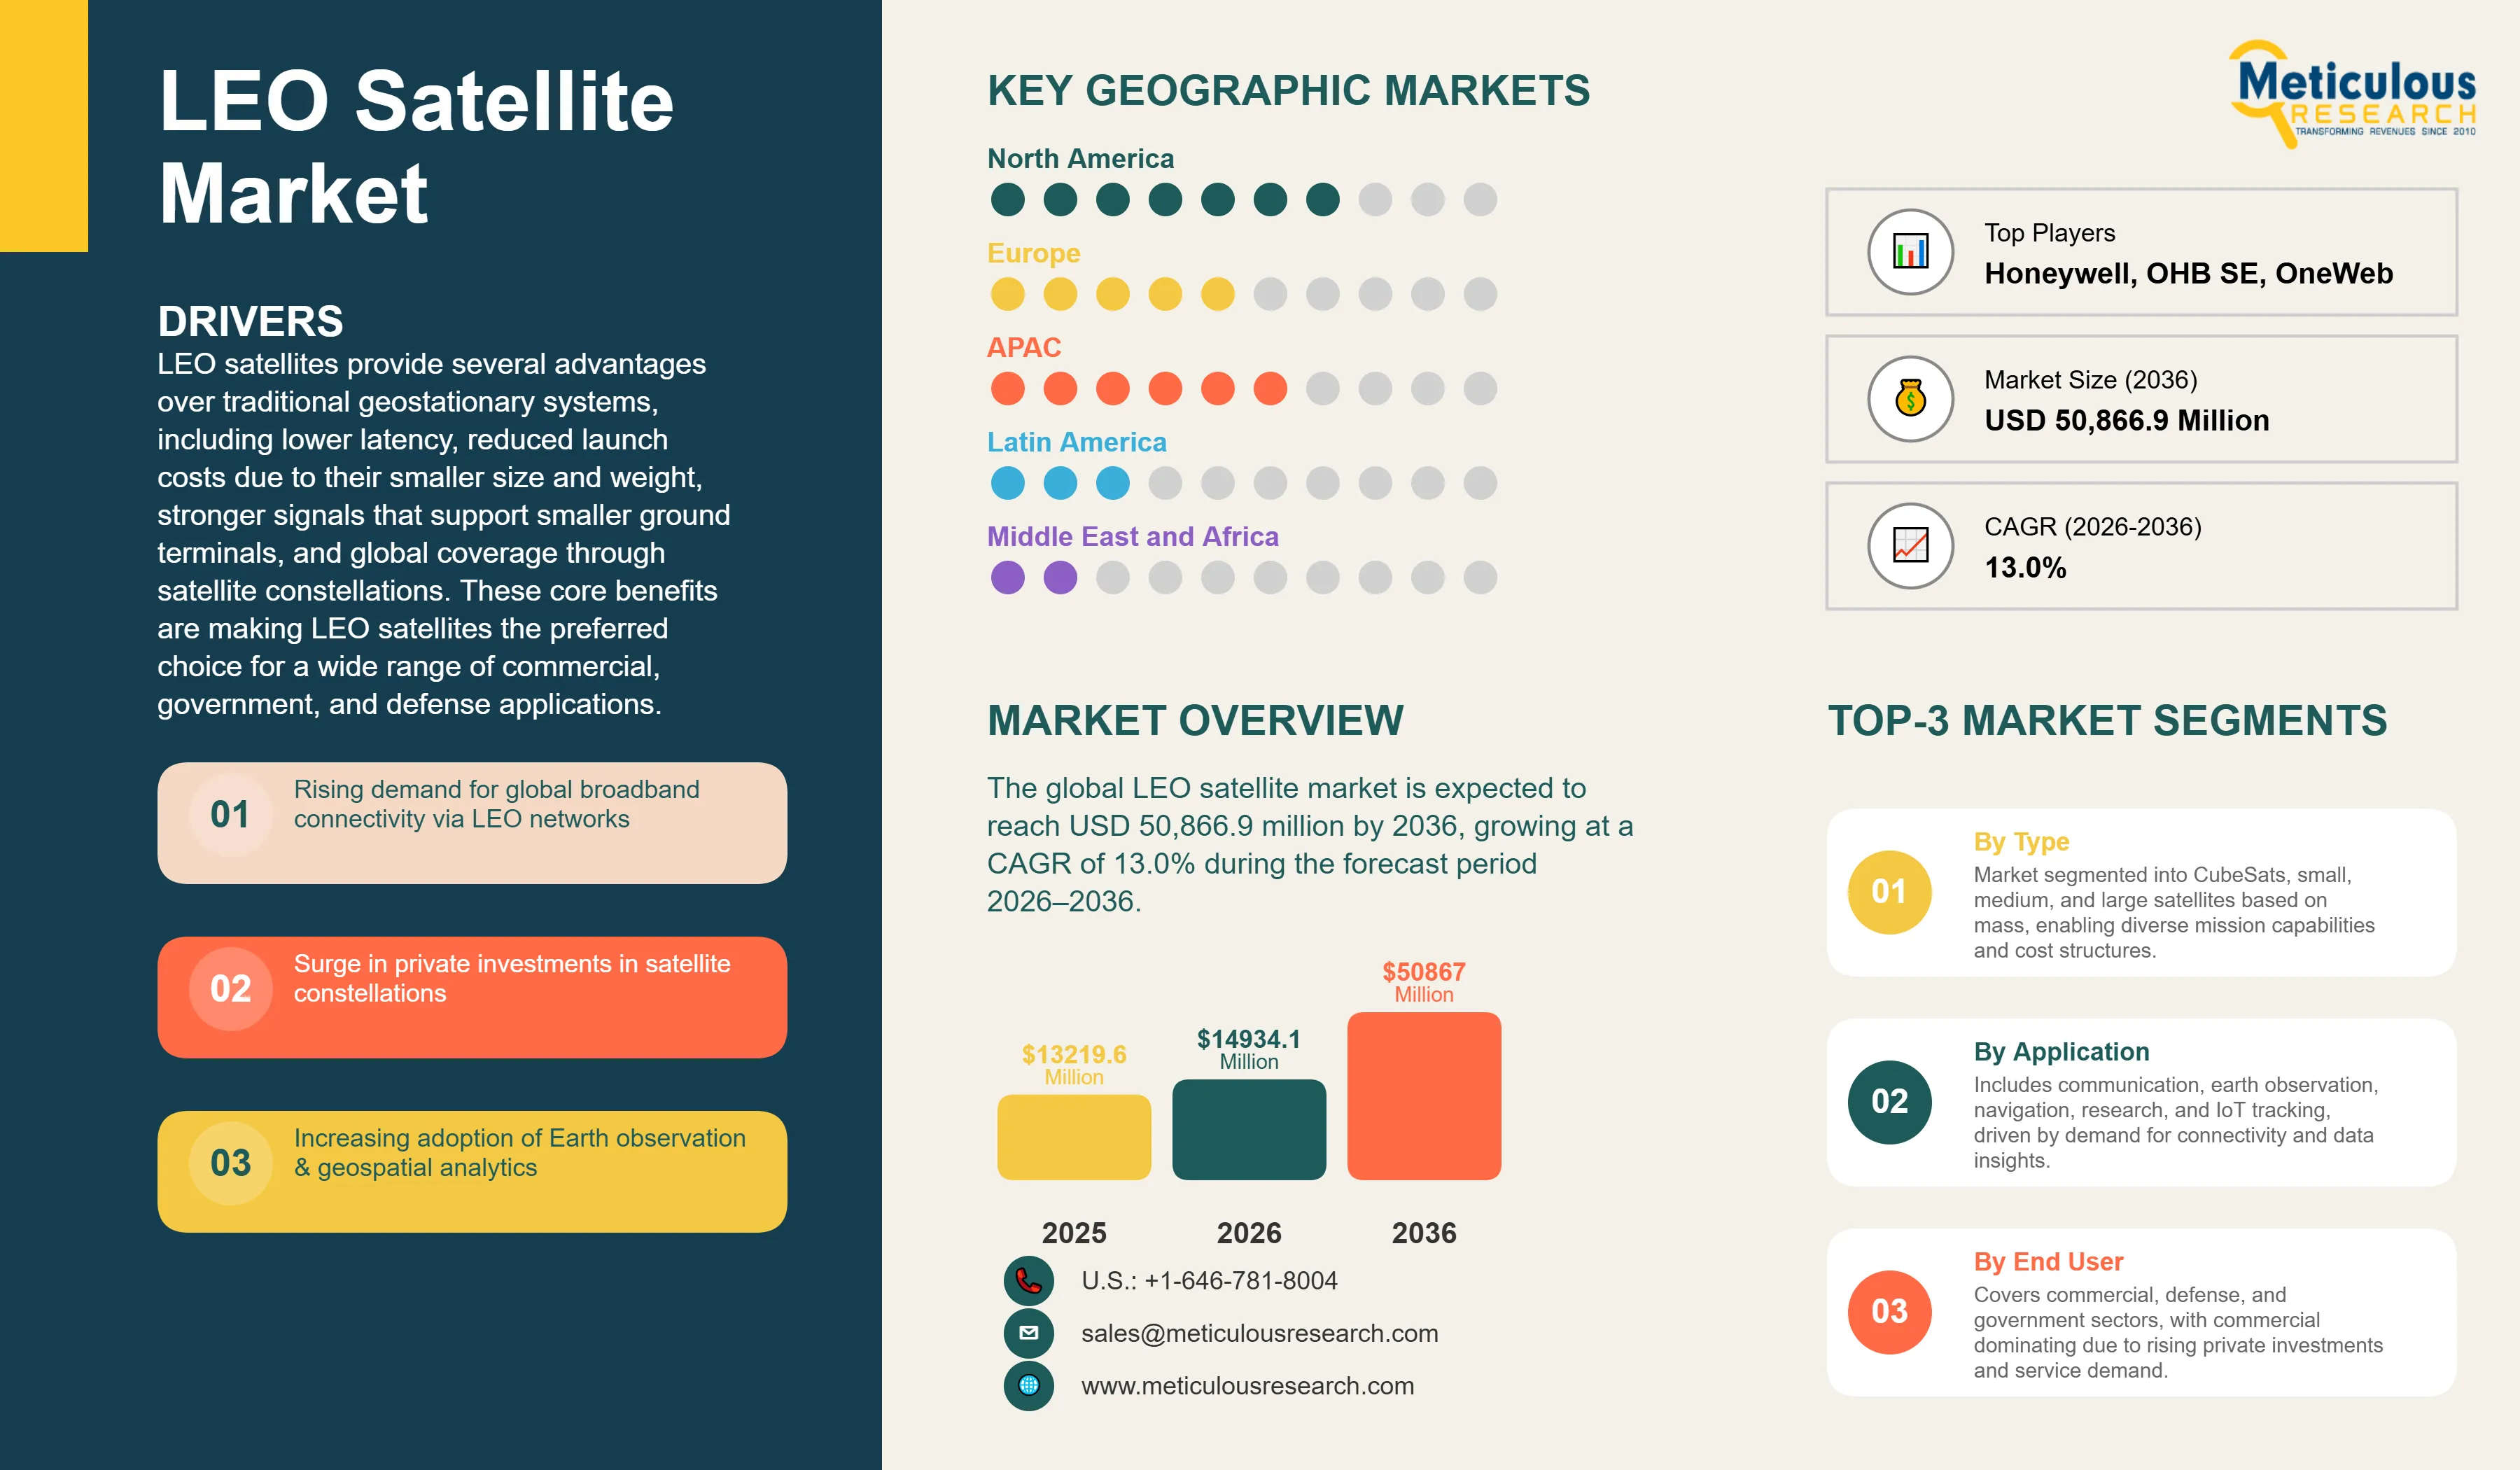
The global LEO satellite market is estimated at USD 14,934.1 million in 2026. This market is expected to reach USD 50,866.9 million by 2036, growing at a CAGR of 13.0% during the forecast period 2026–2036.
- Published
- Apr 2026
- Pages
- 465
- Format
- PDF + Excel
- Report ID
- MR-1788
- Base year
- 2025
- 2026 · ESTIMATED
- $14.93B
- 2036
- $50.87B
- CAGR 2026–2036
- 13.0%
2025 baseline · 2026–2036 forecast at 13.0% CAGR · hover a bar for the value
Key highlights
The global LEO satellite market is projected to reach USD 50, 866.9 million by 2036.
The market is expected to grow at a CAGR of 13.0% during the forecast period 2026–2036.
The global LEO satellite market is estimated at USD 14, 934.1 million in 2026.
North America is expected to lead the global LEO satellite market with the largest share in 2026, driven by the strong presence of leading LEO satellite companies and constellation operators, significant investments in space technologies by both government and private players, and early adoption of advanced satellite communication technologies.
Asia Pacific is projected to witness the fastest growth during the forecast period, driven by increasing investments in space programs by countries such as China, India, and Japan, growing demand for satellite based connectivity in rural and underserved areas, and rapid expansion of commercial space activities supported by government initiatives to strengthen space capabilities.
By satellite mass, the small satellites (10–500 kg) segment is expected to hold the largest share in 2026, driven by the increasing deployment of LEO satellite constellations for broadband connectivity and earth observation applications, along with the optimal balance these satellites offer between payload capacity, cost efficiency, and launch flexibility.
By satellite mass, the CubeSats/nanosatellites (1–10 kg) segment is projected to register the highest growth of 15.2% during the forecast period, driven by rising adoption of low cost satellite solutions for technology demonstration, academic research, and IoT based applications.
By subsystem, the payload segment is expected to account for the largest share of the global LEO satellite market in 2026, attributed to the critical role of payloads in defining satellite functionality across communication, earth observation, and navigation services.
By application, the communication segment is expected to account for the largest share in 2026, driven by increasing demand for global broadband connectivity and high speed internet services.
By application, the tracking and monitoring segment is projected to register the highest growth during the forecast period.
By end user, the commercial segment is expected to dominate the market in 2026, while also registering the fastest growth during the forecast period.
By geography, North America is expected to dominate the market in 2026, while Asia Pacific is expected to witness the fastest growth during the forecast period.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 50,866.9 Million |
| Market Size in 2026 | USD 14,934.1 Million |
| Revenue Growth Rate (2026–2036) | CAGR of 13.0% |
| Format | PDF, Excel & Cloud Portal · 465 pages |
| Dominating Satellite Mass Segment | Small Satellites (10–500 kg) |
| Fastest Growing Satellite Mass Segment | CubeSats/Nanosatellites (1–10 kg) |
| Dominating Subsystem | Payload |
| Dominating Orbit Altitude | Low Earth Orbit (450–1,200 km) |
| Fastest Growing Orbit Altitude | Very Low Earth Orbit (VLEO) (<450 km) |
| Dominating Frequency Band | Ka Band |
| Fastest Growing Frequency Band | Laser/Optical |
| Dominating Application | Communication |
| Fastest Growing Application | Tracking & Monitoring |
| Dominating End User | Commercial |
| Dominating Geography | North America |
| Fastest Growing Geography | Asia Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
Report overview
Segments covered: satellite mass, subsystem, orbit altitude, frequency band, application, end user.
The global LEO satellite market covers spacecraft positioned in orbits ranging from approximately 160 kilometers to 2,000 kilometers above Earth's surface, significantly lower than traditional geostationary satellites that orbit at approximately 35,786 kilometers altitude. LEO satellites serve a broad range of applications including broadband internet connectivity, earth observation and remote sensing, Internet of Things connectivity, navigation and positioning services, weather monitoring, scientific research, and national security purposes.
LEO satellites provide several advantages over traditional geostationary systems, including lower latency, reduced launch costs due to their smaller size and weight, stronger signals that support smaller ground terminals, and global coverage through satellite constellations. These core benefits are making LEO satellites the preferred choice for a wide range of commercial, government, and defense applications.
The growth of the overall LEO satellite market is primarily driven by the rapid commercialization of LEO mega constellation based broadband internet services, which are generating multi billion dollar annual subscription revenues and represent one of the most commercially validated satellite market developments to date. In parallel, the increasing influx of private capital including venture capital, private equity, and strategic corporate investments into commercial LEO satellite programs is supporting constellation deployment, with cumulative investments amounting to tens of billions of dollars. Furthermore, the ongoing transformation in government and defense procurement strategies is rushing the shift toward proliferated LEO architectures, following the demonstrated operational resilience of LEO satellite networks in contested environments.
However, the growth of this market is restrained by the high capital intensity associated with achieving minimum viable satellite constellation thresholds for commercial broadband service delivery, which remains a significant barrier to entry for new operators. Furthermore, increasing spectrum congestion and growing competition for orbital slot allocations among LEO operators are complicating regulatory approvals for new constellation deployments. Evolving competitive pricing dynamics, driven by vertically integrated players with significant cost advantages, are also exerting pricing pressure across the market, making it challenging for independent operators to achieve comparable cost efficiencies without similar scale in manufacturing and launch capabilities.
On the other hand, growing adoption of LEO satellite connectivity across maritime, aviation, and enterprise sectors presents substantial growth opportunities, where low latency and high throughput capabilities offer a clear performance advantage over traditional GEO satellite systems. The emergence of direct to device satellite connectivity is further expanding the market, with the potential to serve billions of users globally. In addition, increasing government procurement of commercial LEO satellite services for applications such as intelligence, weather forecasting, and disaster management is creating stable, long term revenue streams for players operating in this market.
Report infographic
Market dynamics
5 factors across 3 forcesGrowing Demand for Commercial Earth Observation and Geospatial Intelligence Services
The commercial Earth observation (EO) and geospatial intelligence market has emerged as a strong and diversified demand driver for LEO satellite investment. Government defense and intelligence agencies, along with agricultural firms, financial institutions, insurers, energy operators, and environmental organizations, collectively support a multi-billion-dollar annual market, growing at double-digit rates as satellite-derived analytics transition from research tools to operational decision-making inputs. Industry bodies such as the Satellite Industry Association and European Association of Remote Sensing Companies highlight continued expansion in EO data and value-added services driven by both public and commercial demand.
The growth of this market is driven by the convergence of improving data quality and declining costs. Commercial constellations now deliver sub-30 cm optical imagery and sub-meter SAR data, with revisit frequencies ranging from daily to multiple times per day, while increased competition and cloud-based distribution have reduced data pricing. This has expanded accessibility to enterprise users that were previously excluded, positioning EO as a scalable analytics layer across industries.
Table of contents
14 chapters · 253 sections · 465 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Satellite Mass | Small Satellites | CubeSats/nanosatellites (1–10 kg) |
| By Application | Communication | Tracking and monitoring |
| By End User | Commercial | — |
By Satellite Mass
- The Small Satellites Segment to Dominate the Global LEO Satellite Market
- The large share of this segment is mainly attributed to the increasing deployment of LEO satellite constellations for broadband connectivity and earth observation applications, along with the optimal balance these satellites offer between payload capacity, cost efficiency, and launch flexibility.
- The growing preference among commercial operators for scalable and cost effective satellite platforms further supports the dominance of this segment.
- However, the CubeSats/nanosatellites (1–10 kg) segment is projected to register the highest growth rate during the forecast period.
- The fast growth of this segment is driven by the rising adoption of low cost satellite solutions for technology demonstration, academic research, and IoT based applications, coupled with the increasing availability of standardized satellite platforms such as CubeSat form factors.
- The growing number of startups and new space companies focusing on rapid satellite deployment and short mission cycles is significantly accelerating the growth of this segment.
By Application
- The Communication Segment to Hold the Largest Share
- The dominance of this segment is attributed to the increasing demand for global broadband connectivity and high speed internet services, along with the rapid deployment of large scale LEO satellite constellations aimed at bridging the digital divide in underserved and remote regions.
- The growing reliance on satellite based communication for mobility applications — including maritime, aviation, and defense communications — coupled with the rising demand for low latency and high capacity networks, is further driving the dominance of this segment.
- However, the tracking and monitoring segment is projected to register the highest growth during the forecast period.
- The fast growth of this segment is driven by the increasing adoption of satellite enabled IoT solutions for asset tracking, fleet management, and logistics optimization, along with the growing need for real time monitoring across industries such as transportation, agriculture, and environmental management.
By End User
- The Commercial Segment to Account for the Largest Share
- The large share of this segment is attributed to the increasing investments by private companies in deploying large scale LEO satellite constellations for broadband communication and data services, along with the growing demand for satellite based connectivity across industries such as telecommunications, transportation, agriculture, and media.
- The rapid expansion of NewSpace companies and the commercialization of space technologies, coupled with the rising adoption of satellite services for enterprise and consumer applications, is further driving the dominance of this segment.
Geographic analysis
North America
The leading position of North America is driven by the strong presence of leading LEO satellite companies and constellation operators, along with significant investments in space technologies by both government and private players. The early adoption of advanced satellite communication technologies and the presence of a well established space ecosystem, coupled with the increasing deployment of large scale LEO constellations for broadband and defense applications, further strengthens the market leadership in this region.
Asia-Pacific
Fastest growthHowever, the Asia Pacific LEO satellite market is expected to grow at the fastest growth rate during the forecast period. The rapid growth of this region is driven by increasing investments in space programs by countries such as China, India, and Japan, along with the growing demand for satellite based connectivity in rural and underserved areas. The rising number of satellite launches, expanding commercial space activities, and increasing government initiatives to strengthen space capabilities, coupled with the rapid growth of digital infrastructure and IoT adoption, are significantly accelerating the growth of this region.
Competitive landscape
- Lockheed Martin
- Northrop Grumman
- Boeing
- Thales Alenia Space
- Airbus Defence and Space
Frequently asked questions
The global LEO satellite market is expected to reach USD 50,866.9 million by 2036 from an estimated USD 14,934.1 million in 2026, at a CAGR of 13.0% during the forecast period 2026–2036.
Cite this report
Meticulous Research. (2026). LEO Satellite Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MR-1788). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/leo-satellite-market-6471