Digital Health Market (2025-2032)
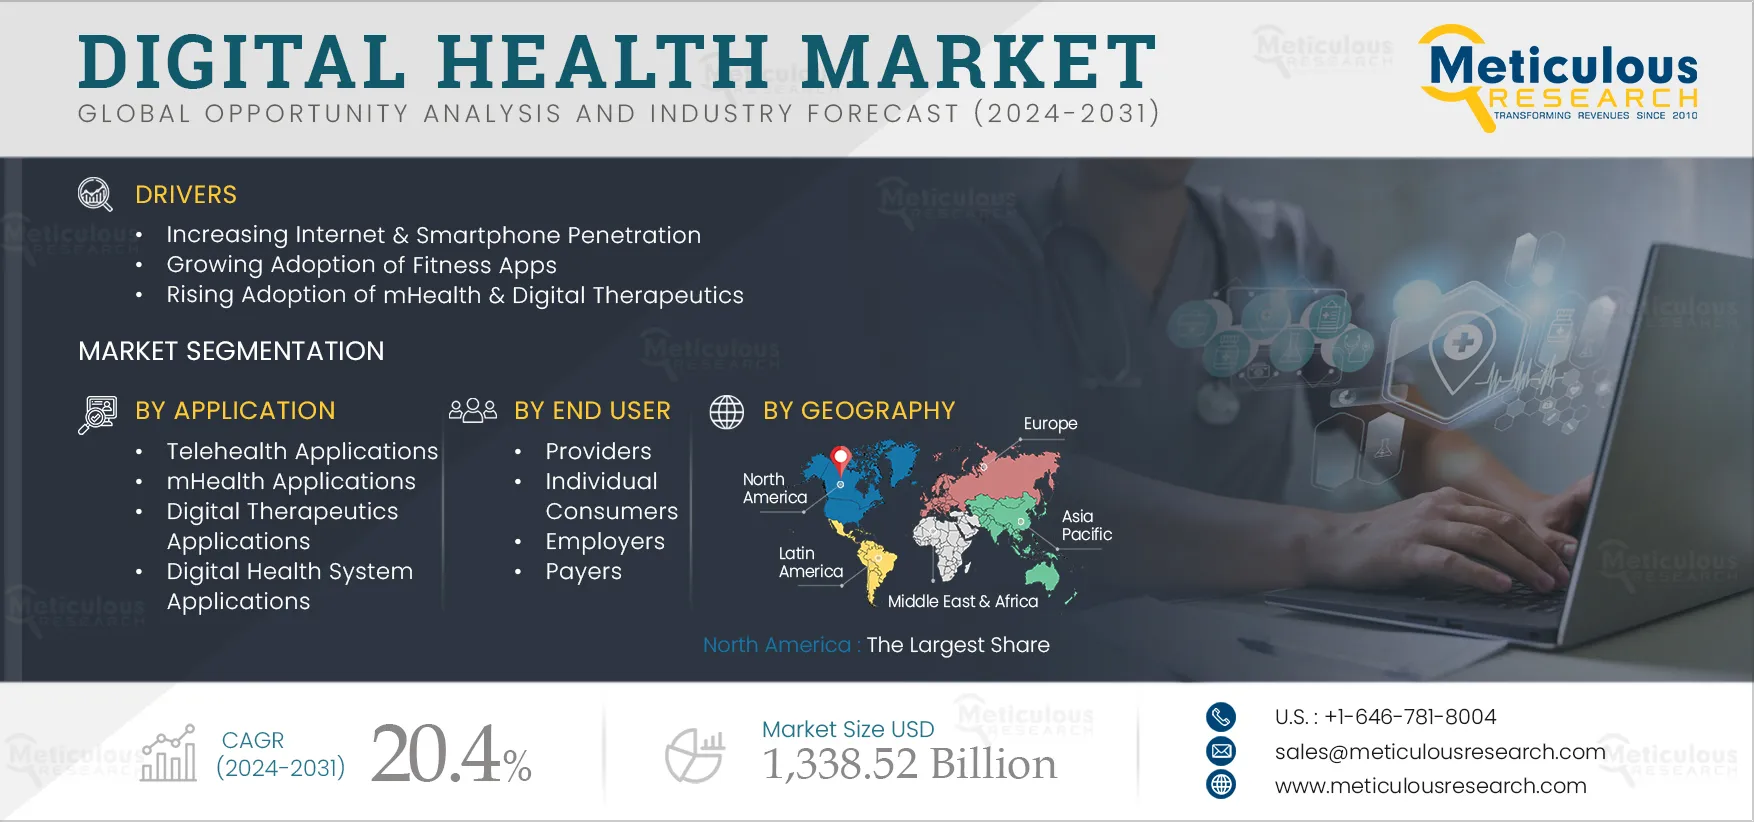
The Digital Health Market was valued at $305.59 billion in 2024. This market is expected to reach $1338.52 billion by 2032, from an estimated $364.96 billion in 2025, at a CAGR of 20.4% during the forecast period 2025-2032. Digital Health Market Size & Forecast The growth of this market is primarily
- Published
- May 2024
- Pages
- 610
- Format
- PDF + Excel
- Report ID
- MRHC - 1041215
- Base year
- 2024
- 2024 · BASELINE
- $305.6B
- 2032
- $1.34T
- CAGR 2025–2032
- 20.4%
2024 baseline · 2025–2032 forecast at 20.4% CAGR · hover a bar for the value
Key highlights
By Component: The Services Segment to Dominate the Digital Health Market in 2025
By Technology: The Telehealth Segment to Dominate the Digital Health Market in 2025
By Application: The Telehealth Applications Segment to Dominate the Digital Health Market in 2025
By End User: The Payers Segment to Dominate the Digital Health Market in 2025
Report summary
| Particulars | Details |
|---|---|
| No. of Pages | 610 |
| Format | |
| Forecast Period | 2025–2032 |
| Base Year | 2024 |
| CAGR | 20.4% |
| Market Size (Value) | $1,338.52 Billion by 2032 |
| Segments Covered | By Component · Hardware · Wearable Devices · Non-wearable Devices · Software · Subscription-based · Licensing-based · Services · Subscription-based · Pay Per Service-based · By Technology · mHealth · mHealth Apps · Disease Management & Treatment Apps · Women's Health Apps · Clinical & Diagnostic Apps · Mental Health Apps · Chronic Disease Management Apps · Medication Management Apps · Sleep Monitoring Apps · Other Disease Management & Treatment Apps · Wellness Apps · Diet & Nutrition Apps · Fitness & Workout Apps · Other mHealth Apps · (Note: Other mHealth apps include insurance & claims processing apps and medical data management apps.) · mHealth Monitoring Devices · Vital Sign Monitoring Devices · Heart Rate Monitors · Activity Monitors · Electrocardiographs · Pulse Oximeters · Spirometers · Blood Pressure Monitors · Blood Glucose Monitors · Sleep Monitoring Devices · Fetal Electrocardiographs & Obstetric Devices · Neuromonitoring Devices · Electroencephalographs · Electromyographs · Other mHealth Monitoring Devices · (Note: Other mHealth monitoring devices include peak flow meters and multiparameter trackers.) · Telehealth · Hardware · Activity Monitoring · Blood Glucose Monitors · Blood Pressure Monitors · Weighing Scales · Pulse Oximeters · Peak Flow Meters · ECG Monitors · Patient Monitors · Other Activity Monitoring Devices · (Note: Other activity monitoring devices include digital thermometers, coagulation monitors, pacemakers, Implantable Cardioverter Defibrillators (ICD), Cardiac Resynchronization Therapy (CRT) devices, and stethoscopes.) · Telemedicine Kiosks · Telemedicine Carts · Remote Medication Management Devices · Software & Services · RPM · Video Consultation · Store & Forward · Digital Therapeutics · Disease Management & Treatment DTx · Disease Prevention DTx · Digital Health Systems · EHR · E-prescribing Systems · Healthcare Analytics · Other Digital Health Systems · (Note: Other digital health systems include health information management systems and Clinical Decision Support Systems (CDSS), among others.) · By Application · Telehealth Applications · Psychiatry · Radiology · Cardiology · Primary Care · Dermatology · Remote ICU · Other Telehealth Applications · (Note: Other telehealth applications include nutrition, nursing, pharmacy, dentistry, audiology, neurology, rehabilitation, pathology, and surgery.) · mHealth Applications · Cardiology · Diabetes · Respiratory Conditions · Neurology · Other mHealth Applications · (Note: Other mHealth applications include fitness, medication management, and rehabilitation.) · Digital Therapeutics Applications · Mental Health · Diabetes · Cardiovascular Diseases · Gastrointestinal Disorders · Neurology · Rehabilitation & Patient Care · Oncology · Respiratory Disorders · Addiction Management · Sleep Disorders · Smoking Cessation · Other Digital Therapeutics Applications · (Note: Other digital therapeutics applications include medication adherence, eye & ear diseases, dermatology, infectious & parasitic diseases, and genitourinary diseases.) · Digital Health System Applications · Practice Management · Population Health Management · Population Health Analytics · Patient Portals · Computerized Physician Order Entry (CPOE) · Clinical Decision Support (CDS) · Clinical Analytics · Financial Analytics · Other Digital Health System Applications · (Note: Other digital health system applications include operational & administrative analytics, clinical management, and referral management.) · By End User · Providers · Individual Consumers · Employers · Payers · Public Payers · Private/Out-of-pocket Payers · Other End Users · (Note: Other end users include pharmaceutical organizations and government institutes.) |
| Countries Covered | North America (U.S., Canada), Europe (Germany, France, U.K., Spain, Italy, Rest of Europe), Asia-Pacific (China, Japan, India, Rest of APAC), Latin America, and the Middle East & Africa |
| Key Companies Profiled | ResMed Inc. (U.S.), Teladoc Health, Inc. (U.S.), Noom, Inc. (U.S.), Aerotel Medical Systems (1998) Ltd. (Israel), Cerner Corporation (U.S.) (a subsidiary of Oracle Corporation), Medtronic plc (U.K.), Koninklijke Philips N.V. (Netherlands), Siemens Healthineers AG (Germany), Cisco Systems, Inc. (U.S.), Johnson and Johnson (U.S.), Allscripts Healthcare, LLC (U.S.), Omron Healthcare Inc. (Japan), GE Healthcare (U.S.), Abbott Laboratories (U.S.), International Business Machines Corporation (U.S.), and Samsung Electronics Co. Ltd. (South Korea) |
Report overview
Segments covered: component, technology, application. Regions: North America, Europe, Asia-Pacific.
The growth of this market is primarily driven by the increasing access to smartphones and the internet in developing economies, the rising adoption of fitness apps, the increasing use of mHealth and digital therapeutics, the growing adoption of wearable medical devices, and the increasing focus on preventive healthcare. Moreover, the focus on developing advanced medical technologies, the shift toward intelligent health ecosystems, and the growing adoption of remote patient monitoring and home healthcare are expected to generate growth opportunities for the players operating in the digital health market.
Report infographic
Market dynamics
5 factors across 3 forcesIncreasing Focus on Preventive Healthcare
Preventive care helps avoid illness and aids early disease diagnosis while promoting good health. Receiving preventive care lowers the probability of disabilities, diseases, and premature death. However, many patients worldwide do not have access to preventive care due to factors such as the absence of primary care providers, high costs, geographical barriers, and lack of awareness. Digital therapeutics help patients prevent disease onset via clinically verified preventive care activities.
Major market players and governments worldwide are increasingly prioritizing investments, policies, and initiatives promoting preventive healthcare. For instance, in March 2021, the European Commission launched the EU4Health program for the period of 2021–2027, with an investment of $6.03 billion (€5.1 billion) in the healthcare sector for disease prevention, health promotion, digital transformation of the healthcare system, integration of digital services & tools, and other areas of intervention.
Growing Adoption of Wearable Medical Devices
The adoption of wearable medical devices such as smartwatches, fitness trackers, biosensors, wearable ECG monitors, and glucometers is increasing. These devices offer self-monitoring as well as monitoring by healthcare professionals. High awareness in developed countries and rising awareness in developing countries regarding preventive care and personal health are driving the adoption of wearable devices. Additionally, the integration of advanced technologies such as artificial intelligence into wearable medical devices has improved accuracy, data interpretation, and data analysis, which are important aspects of patient care. Therefore, the growing adoption of wearable medical devices is driving the digital health market.
Table of contents
12 chapters · 199 sections · 610 pages · click to expandSegmental analysis
| Segment | Largest share (2025) | Fastest growth (2025–2032) |
|---|---|---|
| By Component | Services | Hardware |
| By Technology | Telehealth | Digital therapeutics |
| By Application | Telehealth Applications | Digital therapeutics applications |
| By End User | Payers | Individual consumers |
By Component
- The Services Segment to Dominate the Digital Health Market in 2025
- The services segment is expected to account for the largest share of 63.5% of the digital health market.
- The segment’s large market share is attributed to the adoption of telehealth services, the growing demand for remote patient monitoring, the growth in telemedicine, and the rising prevalence of chronic diseases.
- The outbreak of the COVID-19 pandemic accelerated the adoption of telehealth services, encouraging healthcare providers to scale their offerings.
- Several virtual care services, such as on-demand virtual urgent care, virtual office visits, near-virtual office visits, virtual home health services, and tech-enabled home medication administration, are in high demand.
- However, the hardware segment is projected to record the highest growth rate of 23.4% during the forecast period 2025–2032.
- This growth of this segment is driven by the growing adoption of wearable medical devices, the increasing availability of IoT-enabled medical devices, technological advancements in medical devices, including AI and ML integration, and the increasing adoption of home healthcare.
By Technology
- The Telehealth Segment to Dominate the Digital Health Market in 2025
- The telehealth segment is expected to account for the largest share of 57.6% of the digital health market.
- The segment’s large market share is attributed to the rising prevalence of chronic diseases, the shortage of healthcare professionals, growing digitalization, and rising awareness regarding the benefits of telehealth.
- The demand for more convenient care, along with the unavailability of sufficient medical professionals (particularly primary care providers), has fueled the growth of telemedicine companies.
- Many companies provide patients with access to medical treatment 24 hours a day, seven days a week, via on-call doctors, while some companies also provide extra clinical staff and specialists to hospitals and major health institutions for outsourcing specific cases (common model among teleradiology companies).
- Some companies offer telemedicine platforms that allow doctors to conduct virtual consultations with their patients.
- However, the digital therapeutics segment is expected to grow at the highest CAGR of 31.5% during the forecast period.
- The growth of this segment is driven by the growing prevalence of chronic diseases, the increasing internet and smartphone penetration in developing countries, the rising demand for home healthcare, and increasing investments in digital therapeutics.
- For instance, in June 2024, Wellthy Therapeutics Pvt Ltd (India), a digital care provider, received funding from Beyond Next Ventures Inc. (Japan).
- This funding is aimed at expanding Wellthy’s platform in the Japanese market.
By Application
- The telehealth applications segment is expected to account for the largest share of the digital health market.
- The segment’s large market share is attributed to the high adoption of telehealth for psychiatry, the increased adoption of telehealth since the COVID-19 pandemic, and the significant burden of chronic diseases globally.
- Telehealth in psychiatry involves the utilization of videoconferencing to allow patients in remote locations to access psychiatric services.
- It enables patients and providers to access a wide range of services, including psychiatrist consultations, clinical & educational programs, diagnosis and assessment, medication therapy management, and routine follow-up appointments.
- Patients who require convenient, affordable, and easily accessible mental health care can benefit from video-based telepsychiatry.
- The global shortage of mental health professionals also contributes to the segment’s large share.
- However, the digital therapeutics applications segment is expected to grow at the highest CAGR during the forecast period 2025 to 2032.
- This growth of the segment is driven by the rising prevalence of chronic diseases, increasing focus on preventive healthcare, and rising concerns over healthcare expenditure.
- Digital therapeutics help patients prevent disease onset via clinically verified preventive care.
- Major market players and governments worldwide are increasingly prioritizing investments, policies, and initiatives that promote preventive healthcare.
- For instance, in March 2021, the European Commission launched the EU4Health program for the period of 2021–2027, with an investment of $6.03 billion (€5.1 billion) in the healthcare sector for disease prevention, health promotion, digital transformation of the healthcare system, integration of digital services & tools, and other areas of intervention.
By End User
- The Payers Segment to Dominate the Digital Health Market in 2025
- The payers segment is expected to account for the largest share of the digital health market.
- The segment’s large market share can be attributed to the extensive healthcare coverage in developed countries, rising healthcare costs, and the adoption of digital technologies by healthcare payers.
- However, the individual consumers segment is expected to grow at the highest CAGR during the forecast period.
- The growth of this segment is driven by the rising awareness regarding personal health, the growing adoption of preventive healthcare, increasing access to the internet and smartphones, the growing digitalization of healthcare, and the increasing availability and accessibility of digital health technologies for consumers.
Geographic analysis
North America
Largest shareIn 2025, North America is expected to account for the largest share of 43.6% of the digital health market. Between the U.S. and Canada, in 2025, the U.S. is expected to account for the larger share of the digital health market in North America. The country’s large market share is attributed to the high burden of chronic diseases, high awareness regarding digital health technologies, the high adoption of home healthcare compared to other developed countries, high healthcare expenditure, insurance coverage for remote patient monitoring in Medicare, and the high adoption of digital therapeutics and telemedicine. By Geography: North America to Dominate the Digital Health Market in 2025
Asia-Pacific
Fastest growthHowever, Asia-Pacific is slated to register the highest CAGR of 23.2% during the forecast period. The growth of this regional market is driven by favorable government initiatives for digitalization, growing healthcare expenditure, growing internet and smartphone penetration in rural areas, the shortage of healthcare professionals, and growing awareness regarding digital health technologies.
Competitive landscape
- October 2024
PT BitHealth Teknologi Pintar (Indonesia), a digital health solutions provider, partnered with InterSystems Corporation (U.S.) to create digital data management and integration solutions for the healthcare sector in Indonesia.
- April 2024
Ubie Inc. (U.S.) entered into an agreement with Takeda Pharmaceutical Co., Ltd. (Japan). Under this agreement, Takeda will promote the detection of diseases and provide guidance for appropriate medical examinations using Ubie’s Symptom Checker.
- May 2021
Teladoc Health launched myStrength Complete, an integrated mental health service providing personalized, targeted care to consumers in a single, comprehensive experience.
- ResMed Inc. (U.S.)
- Teladoc Health, Inc. (U.S.)
- Noom, Inc. (U.S.)
- Aerotel Medical Systems (1998) Ltd. · Israel
- Medtronic plc (U.K.)
- Koninklijke Philips N.V. · Netherlands
- Siemens Healthineers AG · Germany
- Cisco Systems, Inc. (U.S.)
- Johnson and Johnson (U.S.)
- Allscripts Healthcare, LLC (U.S.)
- Omron Healthcare Inc. · Japan
- GE Healthcare (U.S.)
- Abbott Laboratories (U.S.)
- International Business Machines Corporation (U.S.)
- Samsung Electronics Co. Ltd. · South Korea
Frequently asked questions
This report covers the market sizes & forecasts for the digital health market based on component, technology, application, and end user. The digital health market report analyzes various segments and sub-segments of the digital health market at the regional and country levels.
Cite this report
Meticulous Research. (2024). Digital Health Market - Global Opportunity Analysis and Industry Forecasts (2025-2032) (Report No. MRHC - 1041215). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/digital-health-market-5898