Digital Therapeutics Market (2024-2031)
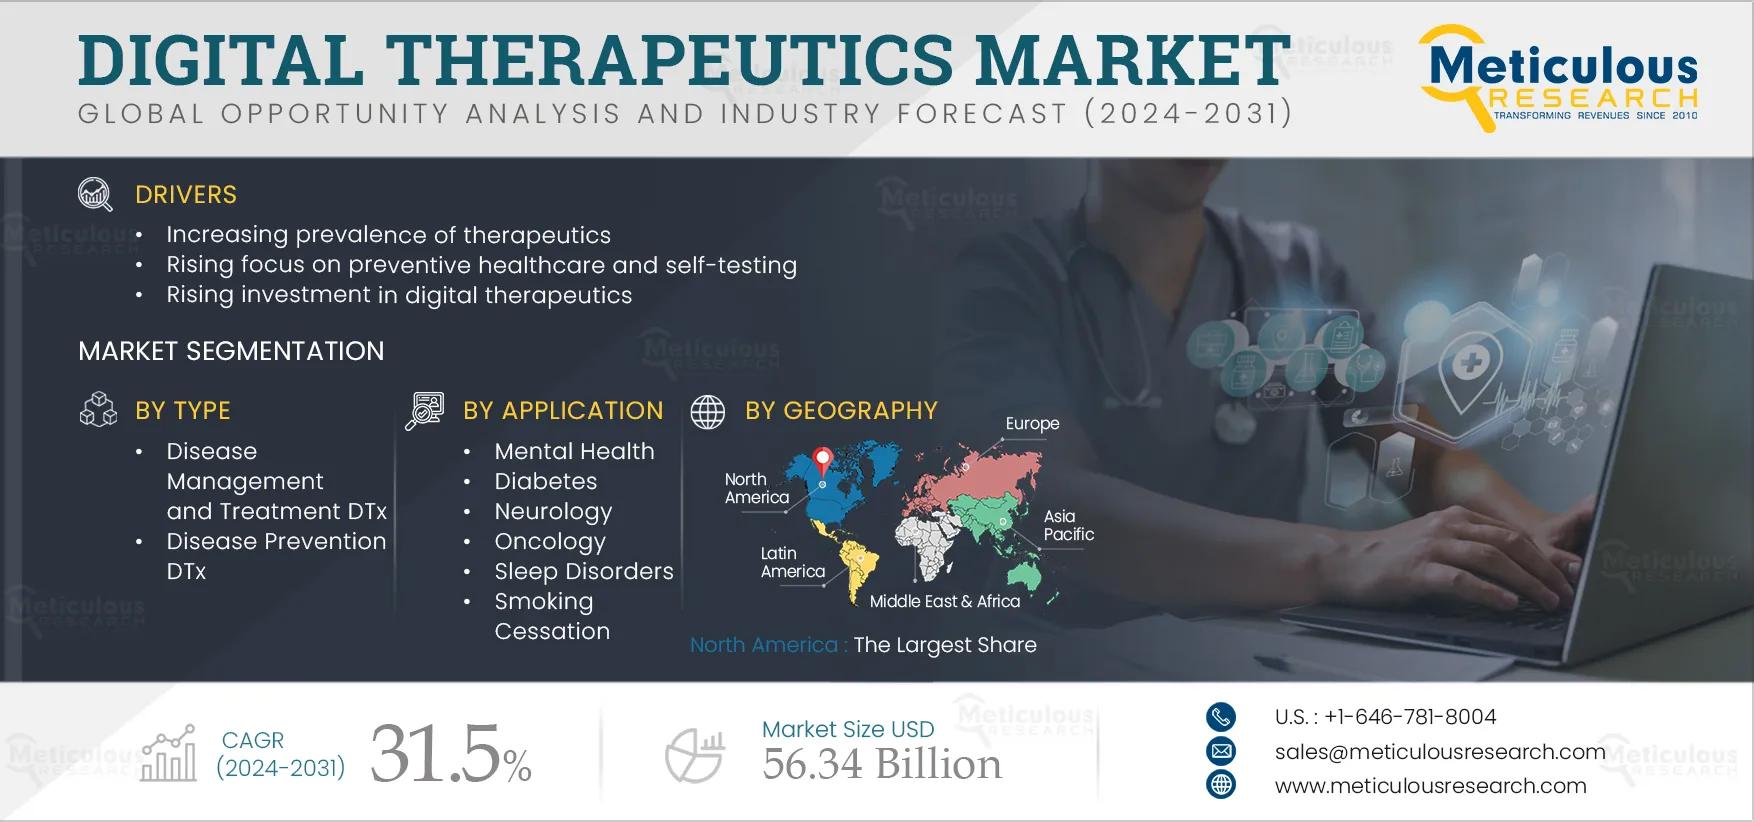
The Digital Therapeutics Market was valued at $6.46 billion in 2023. This market is expected to reach $56.34 billion by 2031 from an estimated $8.26 billion in 2024, at a CAGR of 31.5% during the forecast period of 2024-2031 Digital Therapeutics Market Size & Forecast The increasing prevalence of therapeutics,
- Published
- Nov 2024
- Pages
- 197
- Format
- PDF + Excel
- Report ID
- MRHC - 104743
- Base year
- 2023
- 2023 · BASELINE
- $6.46B
- 2031
- $56.34B
- CAGR 2024–2031
- 31.5%
2023 baseline · 2024–2031 forecast at 31.5% CAGR · hover a bar for the value
Key highlights
By Type: The Disease Management and Treatment DTx Segment Dominates the Digital Therapeutics Market in 2024
By Application: The Mental Health Segment to Dominate the Digital Therapeutics Market in 2024
By End User: The Providers Segment is Expected to Dominate the Digital Therapeutics Market in 2024
By Geography: North America to Dominate the Digital Therapeutics Market in 2024
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 198 |
| Format | |
| Forecast Period | 2024–2031 |
| Base Year | 2023 |
| CAGR (Value) | 31.5% |
| Market Size (Value) | USD 56.34 Billion by 2031 |
| Segments Covered | By Type · Disease Management and Treatment DTx · Disease Prevention DTx · By Application · Mental Health · Diabetes · Cardiovascular Diseases · Gastrointestinal Disorders · Neurology · Rehabilitation & patient care · Oncology · Respiratory Disorders · Addiction management · Sleep Disorders · Smoking Cessation · Other Applications · (Note: Other applications include medication adherence, eyes and ear diseases, dermatology, infectious and parasitic diseases, and genitourinary diseases) · By End User · Providers · Individual Consumers · Employers · Payers · Other End Users · (Note: Other end users include pharmaceutical organizations and government institutes) |
| Countries Covered | North America (U.S. and Canada), Europe (Germany, France, U.K., Italy, Spain, Switzerland and Rest of Europe), Asia-Pacific (China, Japan, India, Australia, and Rest of Asia-Pacific), Latin America (Brazil, Mexico, and Rest of Latin America), and Middle East & Africa |
| Key Companies | Noom, Inc. (U.S.), 2Morrow Inc. (U.S.), GAIA AG (Germany), ResMed Inc. (U.S.), Canary Health (U.S.), Welldoc, Inc. (U.S.), DarioHealth Corp. (U.S.), Akili, Inc. (U.S.), Biofourmis Inc. (U.S.), Big Health (U.S.), Teladoc Health, Inc. (U.S.), Limbix Health, Inc. (U.S.), Kaia Health Software Inc. (Germany), Glooko, Inc. (U.S.), and Virta Health Corp. (U.S.). |
Report overview
Segments covered: type, disease management, treatment dtx, disease prevention dtx, application, mental health, diabete, cardiovascular disease, gastrointestinal disorder, neurology, rehabilitation & patient care, oncology, respiratory disorder, addiction management, sleep disorder, smoking cessation, other application, end user, provider, individual consumer, employer, payer, other end user. Regions: North America, Europe, Asia-Pacific, Latin America.
The increasing prevalence of therapeutics, rising focus on preventive healthcare and self-testing, rising investment in digital therapeutics, and increasing internet users are driving the growth of this market. Furthermore, the untapped market in emerging economies and the growing pipeline of digital therapeutics are expected to generate growth opportunities for the stakeholders in this market.
Report infographic
Market dynamics
3 factors across 2 forcesThe Rising Prevalence of Chronic Diseases is Driving the Growth of this Market
The global prevalence of chronic diseases and conditions, such as diabetes, arthritis, and heart disease, is steadily rising. According to the WHO, in 2020, chronic diseases affected an estimated 57% of the global population, and each year, 41 million people die from these conditions, accounting for 71% of all global deaths. The growth of the aging population and changes in social behaviors are major contributors to the increasing number of individuals suffering from chronic diseases. For example, the International Diabetes Federation reported that, in 2019, 19.3% of people aged 65 and above were affected by diabetes. In North America and the Caribbean, the prevalence of diabetes in this age group rose from 26.3% in 2017 to 27.0% in 2019, with projections indicating it will reach 27.3% by 2030. Similarly, in Europe, diabetes prevalence among people aged 65 and above increased from 20.4% in 2017 to 24.2% in 2019, with an expected increase to 24.7% by 2030. As a result, the growing prevalence of chronic diseases is driving the adoption of digital therapeutic solutions for continuous health monitoring and management.
The global population aged 65 years or older is projected to more than double, increasing from 761 million in 2021 to 1.6 billion by 2050 (Source: United Nations). Developing regions such as Asia, Latin America, and Africa are expected to have the highest proportions of individuals aged 65 and above, followed by Europe and North America. The geriatric population is particularly vulnerable to a range of chronic diseases. As a result, the growing aging population, combined with the rising prevalence of chronic conditions, is driving the growth of the digital therapeutics market.
Increasing Focus on Preventive Healthcare and Self-testing is Driving the Market
Preventive care plays a crucial role in preventing illness, enabling early disease diagnosis, and promoting a healthy lifestyle. By focusing on prevention, it reduces the likelihood of disabilities, diseases, and premature death. However, many patients worldwide lack access to preventive care due to factors such as the shortage of primary care providers, high costs, geographical barriers, and limited awareness.
Digital therapeutics support disease prevention by offering clinically validated preventive care interventions. As the focus on preventive healthcare grows, major market players and governments worldwide are ramping up investments, policies, and initiatives to promote this approach. For example, in March 2021, the European Commission launched the EU4Health program for 2021–2027, with an investment of USD 6.03 billion (EUR 5.1 billion) aimed at disease prevention, health promotion, digital transformation of the healthcare system, and the integration of digital services and tools, among other key areas of intervention.
Digital therapeutics, which utilize software solutions and connected devices, are increasingly being adopted for self-testing. The rising focus on self-testing for improved disease management is contributing to the growing adoption of digital therapeutics, thereby driving the market's growth.
Table of contents
11 chapters · 120 sections · 197 pages · click to expandSegmental analysis
| Segment | Largest share (2024) | Fastest growth (2024–2031) |
|---|---|---|
| By Type | Disease Management and Treatment DTx | — |
By Type
- The disease management and treatment DTx segment is expected to account for the largest share of 76.5% of the digital therapeutics market.
- The large market share of this segment is driven by the availability of cost-effective digital therapeutics solutions for disease management, the increasing need to reduce healthcare costs due to the rising economic burden of healthcare, and higher investments in digital therapeutics.
- For example, in December 2021, Limbix Health, Inc. secured USD 15 million in funding to develop mental health solutions for adolescents.
- Similarly, in May 2021, Noom Inc. (U.S.) raised USD 540 million to expand its behavior-change platform into virtual treatments for conditions such as high blood pressure, diabetes, stress, and sleep disorders.
- Additionally, the growing global burden of chronic diseases is driving the demand for digital therapeutics (DTx) solutions for disease management and treatment.
- Digital therapeutics aim to improve care delivery, enhance patient outcomes, and boost patient engagement and empowerment.
- These solutions have the potential to transform healthcare by optimizing care processes, expanding access to treatment, and fostering patient-centered approaches to care.
Geographic analysis
North America
Largest shareIn 2024, North America is estimated to account for the largest share of 43.6% of the digital therapeutics market. The large share of the North American digital therapeutics market is driven by several factors, including the increasing prevalence of chronic diseases, a surge in the use of digital health products, and growing awareness among patients about digital therapeutics solutions. Additionally, the region is home to a high number of digital therapeutics companies, such as 2Morrow Inc., Welldoc, Inc., BigHealth, Teladoc Health, Inc., and DarioHealth Corp., all based in the U.S. The U.S. government has also been supportive of digital therapeutics, particularly during the COVID-19 pandemic. For example, in April 2020, the U.S. Food and Drug Administration (FDA) relaxed certain premarket requirements for smartphone apps and programs designed to support the treatment of conditions like anxiety, obsessive-compulsive disorder, insomnia, and depression. These factors have significantly contributed to North America's dominant position in the digital therapeutics market. North America Dominates the Digital Therapeutics Market in 2024
Asia-Pacific
Fastest growthHowever, Asia-Pacific is slated to register the highest CAGR of 34.1% during the forecast period. The growth of digital health infrastructure in the APAC region is being driven by several factors, including a shortage of healthcare professionals, the need to reduce healthcare costs, the increasing prevalence of chronic diseases, and the growing consumer preference for mobile applications to manage digital health. These factors are collectively fueling the growth of the digital health market in the region.
Competitive landscape
- June 2024
Teijin Pharma Limited (Japan) and CureApp, Inc. (U.S.) signed a joint marketing and sales agreement for the Prescription Digital Therapeutic App for Hypertension. Through the partnership, the companies aim to expand the use of CureApp HT, which supports lifestyle modifications for hypertension treatment.
- May 2024
Otsuka Pharmaceutical Co., Ltd. (Japan) launched a subsidiary, Otsuka Precision Health, to commercialize its digital therapeutic Rejoyn and other digital therapeutics and connected health products.
- April 2024
Otsuka Pharmaceutical Co., Ltd. (Japan) and Therapeutics, Inc. (U.S.) jointly developed the mobile app Rejoyn received FDA clearance for use as an adjunct to medication in the treatment of major depressive disorder.
- January 2024
Big Health (U.S.) raised USD 75 million in a series C funding round to accelerate the company’s commercial reimbursement model and product platform, including six new digital therapeutics by 2024. The funding was provided by SoftBank Vision Fund (U.S.), with participation from ArrowMark Partners (U.S.) and existing investors Octopus Ventures (U.K.), Gilde Healthcare (Netherlands), Kaiser Permanente Ventures (KPV) (U.S.), and Morningside Ventures (U.S.).
- January 2023
Kaia Healthcare Software Inc. (Germany) Kaia Back Pain got permanently listed on the DiGA platform, making it free for consumers with statutory health insurance.
- Noom, Inc. (U.S.)
- 2Morrow Inc. (U.S.)
- GAIA AG · Germany
- ResMed Inc. (U.S.)
- Canary Health (U.S.)
- Welldoc, Inc. (U.S.)
- DarioHealth Corp. (U.S.)
- Akili, Inc. (U.S.)
- Biofourmis Inc. (U.S.)
- Big Health (U.S.)
- Teladoc Health, Inc. (U.S.)
- Limbix Health, Inc. (U.S.)
- Kaia Health Software Inc. · Germany
- Glooko, Inc. (U.S.)
- Virta Health Corp. (U.S.)
Frequently asked questions
The global digital therapeutics market size was valued at $6.46 billion in 2023.
Cite this report
Meticulous Research. (2024). Digital Therapeutics Market - Global Opportunity Analysis And Industry Forecast (2024-2031) (Report No. MRHC - 104743). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/digital-therapeutics-market-5427