Cell Culture Market (2026-2036)
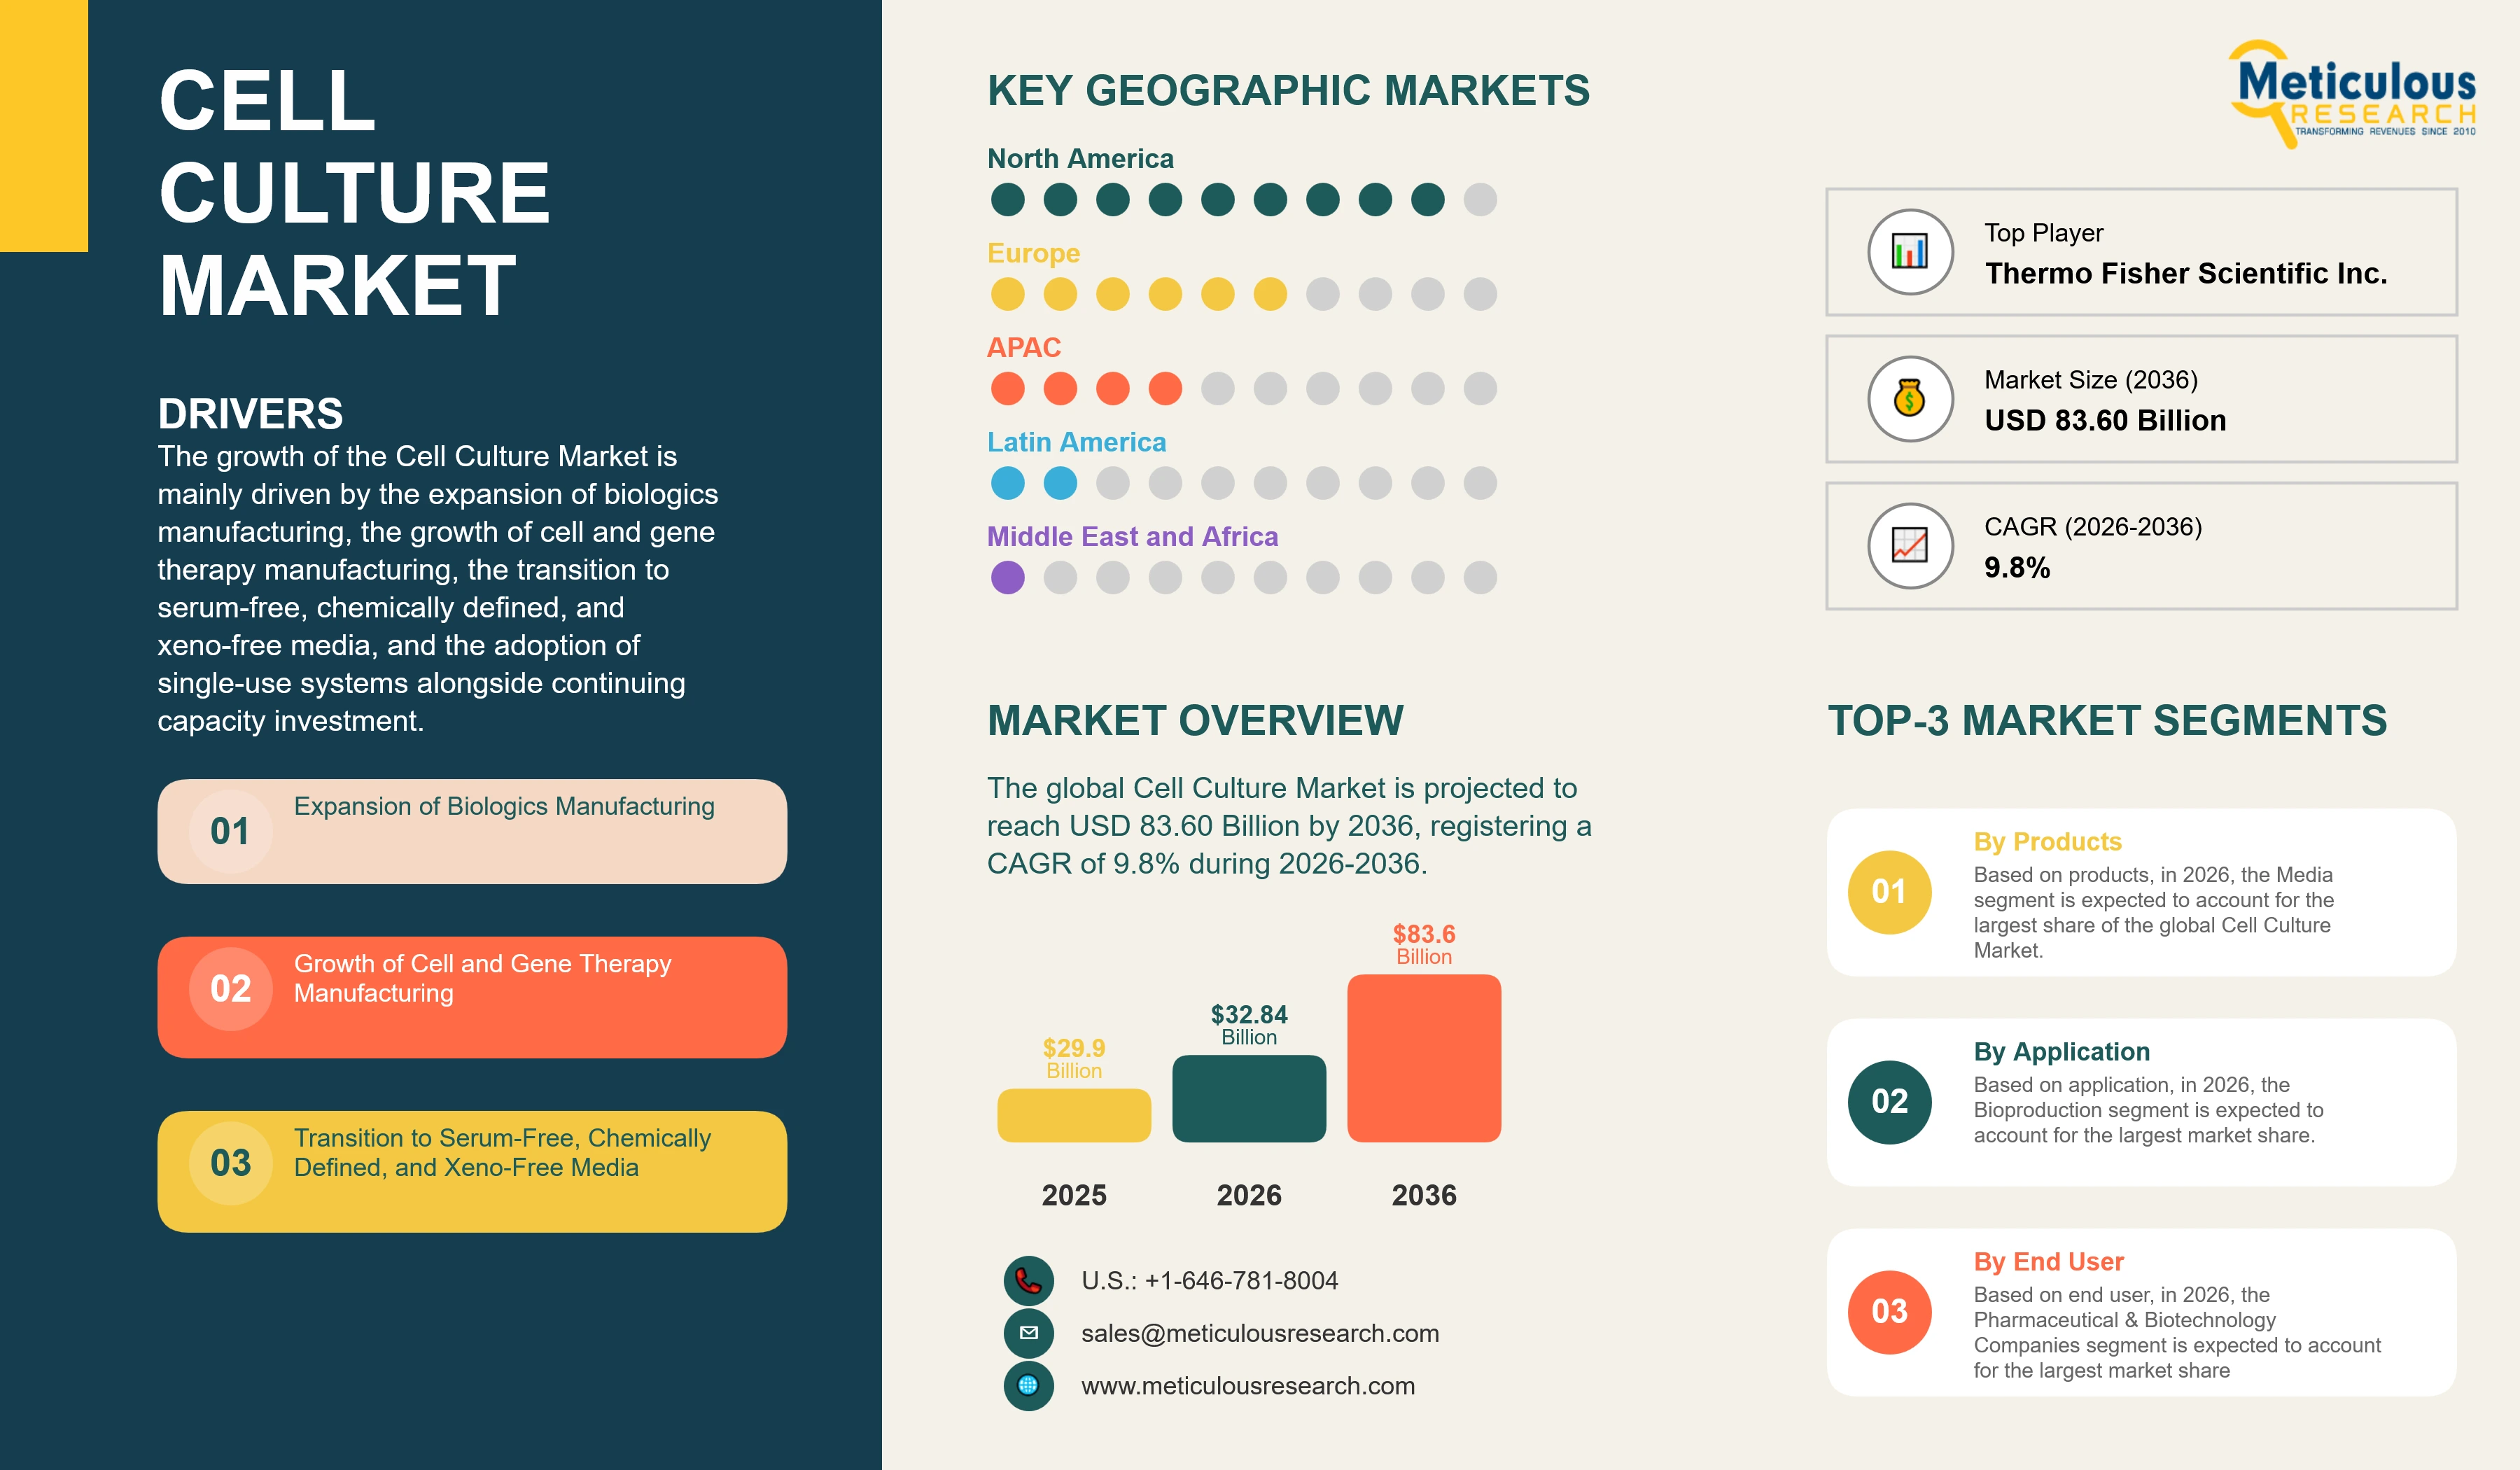
The global Cell Culture Market was valued at USD 29.90 billion in 2025. This market is expected to reach USD 83.60 billion by 2036 from an estimated USD 32.84 billion in 2026, registering a CAGR of 9.8% during the forecast period (2026-2036).
- Published
- Oct 2026
- Pages
- 338
- Format
- PDF + Excel
- Report ID
- MRHC - 104127
- Base year
- 2025
- 2025 · BASELINE
- $29.90B
- 2036
- $83.60B
- CAGR 2026–2036
- 9.8%
2025 baseline · 2026–2036 forecast at 9.8% CAGR · hover a bar for the value
Key highlights
The global Cell Culture Market is projected to reach USD 83.60 billion by 2036, driven by biologics and cell and gene therapy manufacturing, the shift to chemically defined media, single-use adoption, and regulatory support for human cell-based testing.
Bioprocessing demand has recovered strongly. In the second quarter of 2026, Merck KGaA reported Life Science net sales of EUR 2.4 billion, up 8.0% organically, with its Process Solutions business unit growing 14.7% organically to EUR 1.07 billion, led by downstream processing and single-use solutions, and upgraded its full-year Life Science guidance to net sales of approximately EUR 9.3-9.6 billion with organic growth of 5% to 7%.
Consumables are leading the upturn. In the first quarter of 2026, Sartorius AG reported group sales of EUR 899 million, up 7.5% in constant currencies, with its Bioprocess Solutions division growing 8.1% in constant currencies to EUR 735 million, and confirmed full-year guidance of constant-currency sales growth of approximately 6% to 10% for Bioprocess Solutions, driven mainly by consumables, with an underlying EBITDA margin slightly above 32%.
North America is expected to account for the largest market share in 2026, supported by the concentration of biologics and advanced therapy manufacturing and the presence of leading suppliers, while Asia-Pacific is projected to register the fastest growth during the forecast period.
By product, Media is expected to account for the largest market share in 2026, whereas Serum-Free and Chemically Defined formulations are projected to witness the fastest growth through 2036, as manufacturers eliminate animal-derived components for regulatory, consistency, and supply reasons.
Report summary
| Particulars | Details |
|---|---|
| Forecast Period | 2026-2036 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| CAGR (Value) | 9.8% |
| Format | PDF, Excel & Cloud Portal · 338 pages |
| Market Size (Value) in 2026 | USD 32.84 Billion |
| Market Size (Value) in 2036 | USD 83.60 Billion |
| Segments Covered | By Product: Consumables (Media [by Form: Dry Media, Liquid Media; by Type: Off-the-Shelf Media, Custom Media; by Formulation: Serum-Free Media, Chemically Defined Media, Classical Media, Xeno-Free & Animal Component-Free Media], Sera, Reagents & Supplements [Growth Factors & Cytokines, Cryoprotective Reagents, Antibiotics & Antimycotics, Cell Dissociation Reagents, Buffers & Balanced Salt Solutions], Vessels & Single-Use Consumables), Equipment (Bioreactors & Fermenters, Incubators & CO2 Incubators, Centrifuges & Cell Counters, Biosafety Cabinets, Filtration & Storage Equipment). By Cell Type: Mammalian Cells (Chinese Hamster Ovary Cells, Other Mammalian Cell Lines), Human Primary & Stem Cells (Primary Human Cells, Induced Pluripotent Stem Cells, Other Stem Cells), Microbial & Yeast Cells, Insect & Other Cells. By Application: Bioproduction (Monoclonal Antibody Production, Therapeutic Protein Production, Vaccine Production, Cell & Gene Therapy Manufacturing), Research Applications (Cancer Research, Stem Cell Research, Drug Screening & Toxicology, Other Research), Diagnostics, Other Applications. By End User: Pharmaceutical & Biotechnology Companies, Contract Development & Manufacturing Organizations, Academic & Research Institutes, Other End Users. |
| Countries Covered | North America: U.S., Canada. Europe: Germany, Switzerland, U.K., France, Ireland, Italy, Spain, Rest of Europe. Asia-Pacific: China, India, South Korea, Japan, Singapore, Australia, Rest of Asia-Pacific. Latin America: Brazil, Mexico, Rest of Latin America. Middle East & Africa: Saudi Arabia, UAE, Rest of Middle East & Africa. |
| Key Companies | Thermo Fisher Scientific Inc., Merck KGaA, Danaher Corporation (Cytiva), Sartorius AG, Lonza Group AG, Corning Incorporated, Becton, Dickinson and Company, Avantor, Inc., Bio-Rad Laboratories, Inc., Agilent Technologies, Inc., Eppendorf SE, FUJIFILM Holdings Corporation, Getinge AB, Greiner Bio-One International GmbH, Miltenyi Biotec B.V. & Co. KG, and HiMedia Laboratories Pvt. Ltd. |
Report overview
Segments covered: product, media type, application, end user.
The growth of this market is mainly driven by the expansion of biologics manufacturing, including monoclonal antibodies, antibody-drug conjugates, and therapeutic proteins, each of which consumes cell culture media and single-use consumables in proportion to production volume; the growth of cell and gene therapy manufacturing, which requires specialised media and closed-system consumables at high cost per batch; the continuing transition from serum-containing to chemically defined, serum-free, and xeno-free formulations driven by regulatory and supply considerations; and the adoption of single-use bioreactors and consumables, which converts capital equipment spending into recurring consumable demand. In addition, regulatory initiatives promoting human cell-based alternatives to animal testing, the growth of three-dimensional culture, organoid, and organ-on-chip systems, the expansion of vaccine and biosimilar manufacturing, and the build-out of biomanufacturing capacity in Asia-Pacific are further supporting the growth of this market.
The Cell Culture Market, also referred to as the cell culture consumables and equipment market, cell culture reagents market, or cell cultivation market, comprises the media, sera, reagents, vessels, bioreactors, and ancillary equipment used to grow and maintain cells outside the organism for research, diagnostic, and manufacturing purposes. The market includes classical, serum-free, chemically defined, and xeno-free media supplied in dry and liquid forms as off-the-shelf or custom formulations; animal sera and serum substitutes; growth factors and cytokines; cryoprotective reagents; antibiotics and antimycotics; cell dissociation reagents; buffers and balanced salt solutions; culture vessels, flasks, plates, and single-use bags and bioreactors; and incubators, centrifuges, biosafety cabinets, cell counters, and filtration and storage equipment. The market ecosystem extends from media, reagent, and equipment manufacturers to biopharmaceutical manufacturers, contract development and manufacturing organizations, cell and gene therapy developers, vaccine manufacturers, diagnostic companies, academic and research institutes, and the regulators whose expectations shape media composition and process design.
Cell culture is the foundation on which the biologics industry rests. Every monoclonal antibody, therapeutic protein, viral vector, and cell therapy is produced by cells growing in a defined environment, and the composition of that environment determines yield, product quality, and consistency. Media and feeds are consumed in proportion to production volume, which makes this market a direct function of biomanufacturing output rather than of instrument placement, and it is why media represents the largest single product category and the one most closely coupled to industry growth.
The market has recovered from a difficult period. Following the pandemic, biopharmaceutical manufacturers and contract manufacturers had accumulated substantial inventories of media and single-use consumables, and the subsequent destocking depressed supplier revenues for several quarters in a way that reflected inventory correction rather than any decline in underlying production. In the second quarter of 2026, Merck KGaA reported Life Science net sales of EUR 2.4 billion, up 8.0% organically, with its Process Solutions business unit growing 14.7% organically to EUR 1.07 billion, led by downstream processing and single-use solutions, and upgraded its full-year Life Science guidance to net sales of approximately EUR 9.3-9.6 billion with organic growth of 5% to 7%. In the first quarter of 2026, Sartorius AG reported group sales of EUR 899 million, up 7.5% in constant currencies, with its Bioprocess Solutions division growing 8.1% in constant currencies to EUR 735 million, and confirmed full-year guidance of constant-currency sales growth of approximately 6% to 10% for Bioprocess Solutions, driven mainly by consumables, with an underlying EBITDA margin slightly above 32%. Growth of 14.7% organically in process solutions and 8.1% in bioprocess consumables indicates that destocking has concluded and that demand now tracks production.
Cell and gene therapy manufacturing is the fastest-growing source of demand and the most demanding technically. According to a pipeline assessment published in January 2026, six cell and gene therapy products had been submitted to the U.S. Food and Drug Administration with prescription drug user fee act dates falling in 2026, with a further 18 products anticipated in 2027, of which 12 were in Phase 3. In July 2026, the U.S. Food and Drug Administration expanded the approval of CASGEVY, the first CRISPR-based gene-editing therapy, to children aged two years and older with sickle cell disease or transfusion-dependent beta thalassemia, with the therapy available at more than 75 authorized treatment centres in the U.S. These processes require media supporting the expansion of primary human cells, often without animal-derived components, in closed single-use systems and at batch sizes far smaller than antibody production, which means cost per batch is high and the media must be qualified to a standard appropriate to a product administered as a single irreversible dose.
Regulatory expectations are shaping media composition directly. In May 2026, the FDA Center for Biologics Evaluation and Research issued final guidance that removed the fixed requirement for three process performance qualification lots for process validation of cell and gene therapy products and permitted concurrent validation and release, while noting that changes in source materials, such as a switch from fetal bovine serum to human albumin, require comparability studies. The explicit identification of a change from fetal bovine serum to human albumin as requiring comparability studies illustrates how closely media composition is tied to regulatory filings, and why manufacturers prefer to establish chemically defined formulations early rather than to change them after clinical data has been generated.
A second regulatory current is expanding the research market for human cell culture. In September 2026, the FDA announced a direct final rule replacing the terms animal tests and animal studies with nonclinical tests and nonclinical studies throughout its regulations, clarifying that non-animal methods including human cell-based platforms and organ-on-chip systems can be used where appropriate to test the safety of drugs and biological products, and in June 2026 the European Commission published its roadmap towards phasing out animal testing for chemical safety assessments across 15 regulatory domains. Where safety assessment moves from animal studies toward human cell-based systems, organoids, and organ-on-chip platforms, the demand created falls on cell culture media, specialised reagents, and three-dimensional culture consumables, which positions this part of the market to benefit from a regulatory shift originating outside biomanufacturing entirely.
Capacity investment sustains the equipment and consumables cycle. In the first half of 2026, Lonza Group AG reported sales of CHF 3.4 billion, up 16.0% at constant exchange rates, with all business platforms growing at double-digit rates, raised its full-year CORE EBITDA margin guidance to 33-34%, and brought its large-scale mammalian asset in Visp, Switzerland into commercial operation as planned. New manufacturing capacity consumes equipment on commissioning and media and single-use consumables for as long as it operates, and the continuing build-out of capacity by contract manufacturers and by biopharmaceutical companies in both established and emerging markets underpins demand across the forecast period.
The market includes diversified life science suppliers such as Thermo Fisher Scientific, Merck KGaA, Danaher through Cytiva, Sartorius, Corning, Becton Dickinson, Avantor, Bio-Rad Laboratories, Agilent Technologies, Eppendorf, Greiner Bio-One, and Getinge, together with Lonza and FUJIFILM Holdings, which supply media and services alongside contract manufacturing, Miltenyi Biotec in cell therapy reagents and systems, and regional suppliers including HiMedia Laboratories. Participants compete on media performance and yield, lot-to-lot consistency, regulatory support documentation and change control, security and geographic diversity of supply, custom formulation and process development capability, single-use portfolio breadth, and total cost of ownership.
At the same time, the market faces challenges, including the volatility that inventory cycles introduce into supplier revenues, price pressure on commodity media and consumables, the cost and lead time of qualifying a media change once a process is established, continuing dependence on animal-derived serum in parts of the research market and in some manufacturing processes, supply security concerns for critical raw materials and growth factors, and the sustainability burden of single-use plastics. As a result, suppliers that combine high-performing chemically defined formulations, documented regulatory support, geographically diversified and secure supply, custom development capability, and credible sustainability programmes are expected to capture the largest share of growth over the forecast period.
Report infographic
Market dynamics
15 factors across 5 forcesExpansion of Biologics Manufacturing
The expansion of biologics manufacturing is a major factor driving the Cell Culture Market, because media and single-use consumables are consumed in proportion to production volume rather than purchased once. Monoclonal antibodies, antibody-drug conjugates, therapeutic proteins, and biosimilars are all produced in mammalian cell culture, and each additional approved product and each expansion of an existing product into new indications or geographies increases media consumption directly. In the second quarter of 2026, Merck KGaA reported Life Science net sales of EUR 2.4 billion, up 8.0% organically, with its Process Solutions business unit growing 14.7% organically to EUR 1.07 billion, led by downstream processing and single-use solutions, and upgraded its full-year Life Science guidance to net sales of approximately EUR 9.3-9.6 billion with organic growth of 5% to 7%.
The recovery in supplier revenues demonstrates the coupling. Process solutions growth of 14.7% organically, led by downstream processing and single-use solutions, and bioprocess consumables growth of 8.1% in constant currencies, reflect production activity rather than capital investment cycles, and confirm that the destocking that depressed the market has concluded. In the first quarter of 2026, Sartorius AG reported group sales of EUR 899 million, up 7.5% in constant currencies, with its Bioprocess Solutions division growing 8.1% in constant currencies to EUR 735 million, and confirmed full-year guidance of constant-currency sales growth of approximately 6% to 10% for Bioprocess Solutions, driven mainly by consumables, with an underlying EBITDA margin slightly above 32%.
Growth of Cell and Gene Therapy Manufacturing
The growth of cell and gene therapy manufacturing is significantly driving market growth, and does so at a higher value per unit of output than conventional biologics. According to a pipeline assessment published in January 2026, six cell and gene therapy products had been submitted to the U.S. Food and Drug Administration with prescription drug user fee act dates falling in 2026, with a further 18 products anticipated in 2027, of which 12 were in Phase 3. In July 2026, the U.S. Food and Drug Administration expanded the approval of CASGEVY, the first CRISPR-based gene-editing therapy, to children aged two years and older with sickle cell disease or transfusion-dependent beta thalassemia, with the therapy available at more than 75 authorized treatment centres in the U.S. Expanding primary human cells requires media formulated without animal-derived components, supplemented with specific cytokines and growth factors, and supplied in closed single-use systems, and because batches are small, often serving a single patient, media and consumable cost per batch is high.
Transition to Serum-Free, Chemically Defined, and Xeno-Free Media
The transition to serum-free, chemically defined, and xeno-free media is an important driver of demand and of value. Animal serum varies between lots, carries adventitious agent risk, is subject to supply constraints and ethical concern, and complicates regulatory filings, whereas chemically defined media provide consistent composition, better process control, and simpler regulatory justification. In May 2026, the FDA Center for Biologics Evaluation and Research issued final guidance that removed the fixed requirement for three process performance qualification lots for process validation of cell and gene therapy products and permitted concurrent validation and release, while noting that changes in source materials, such as a switch from fetal bovine serum to human albumin, require comparability studies.
The identification by regulators of a change from fetal bovine serum to human albumin as requiring comparability studies illustrates why this transition is made early rather than late. Once a process has generated clinical data, changing the media requires a comparability package, which creates a strong incentive to establish a defined formulation before pivotal studies and makes media selection a decision with consequences across the product lifecycle.
Adoption of Single-Use Systems and Capacity Investment
The adoption of single-use systems and continuing capacity investment supports market growth. Single-use bioreactors, bags, and tubing sets eliminate cleaning validation, shorten changeover, and allow a facility to run multiple products, and in doing so they convert what was capital equipment spending into recurring consumable demand. In the first half of 2026, Lonza Group AG reported sales of CHF 3.4 billion, up 16.0% at constant exchange rates, with all business platforms growing at double-digit rates, raised its full-year CORE EBITDA margin guidance to 33-34%, and brought its large-scale mammalian asset in Visp, Switzerland into commercial operation as planned. New capacity consumes equipment at commissioning and media and single-use consumables for as long as it operates.
Table of contents
12 chapters · 178 sections · 338 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Product | Media | Serum-Free and Chemically Defined formulations |
| By Cell Type | Mammalian Cells | Human Primary & Stem Cells |
| By Application | Bioproduction | Cell & Gene Therapy Manufacturing |
| By End User | Pharmaceutical & Biotechnology Companies | Contract Development & Manufacturing Organizations |
By Product
- Consumables are further segmented into Media, Sera, Reagents & Supplements, and Vessels & Single-Use Consumables, while Media is further segmented by form into Dry Media and Liquid Media, by type into Off-the-Shelf Media and Custom Media, and by formulation into Serum-Free Media, Chemically Defined Media, Classical Media, and Xeno-Free and Animal Component-Free Media.
- Reagents & Supplements are further segmented into Growth Factors & Cytokines, Cryoprotective Reagents, Antibiotics & Antimycotics, Cell Dissociation Reagents, and Buffers & Balanced Salt Solutions.
- Equipment is further segmented into Bioreactors & Fermenters, Incubators & CO2 Incubators, Centrifuges & Cell Counters, Biosafety Cabinets, and Filtration & Storage Equipment.
- The Media segment is expected to account for the largest share of the global Cell Culture Market.
- The large share of this segment is mainly due to the consumption of media in direct proportion to production volume across every biologics and advanced therapy process, the value of custom and chemically defined formulations relative to commodity products, and the coupling of media demand to biomanufacturing output, demonstrated by organic growth of 14.7% in process solutions at Merck KGaA in the second quarter of 2026.
- Within media, the Serum-Free and Chemically Defined formulations are projected to register the highest CAGR during the forecast period, attributed to regulatory preference for defined composition, the consistency and process control they provide, the elimination of adventitious agent and supply risk associated with animal serum, and their requirement in cell and gene therapy manufacturing.
- The Equipment segment is expected to grow more slowly than consumables, reflecting the shift of value from capital equipment toward recurring single-use consumption.
By Cell Type
- Cell Culture Market Analysis by Cell Type
- Mammalian Cells are further segmented into Chinese Hamster Ovary Cells and Other Mammalian Cell Lines, while Human Primary & Stem Cells are further segmented into Primary Human Cells, Induced Pluripotent Stem Cells, and Other Stem Cells.
- The Mammalian Cells segment is expected to account for the largest share of the market.
- The large share of this segment is mainly due to the production of monoclonal antibodies, therapeutic proteins, and many vaccines in mammalian cell culture, the dominance of Chinese hamster ovary cell lines in commercial biologics manufacturing, and the scale of production volumes in this category relative to all others.
- However, the Human Primary & Stem Cells segment is projected to register the highest CAGR during the forecast period.
- The rapid growth of this segment is attributed to cell and gene therapy manufacturing, which expands primary human cells rather than established cell lines, the growth of induced pluripotent stem cell research and manufacturing, and the expansion of human cell-based models for safety assessment following regulatory recognition of non-animal methods.
By Application
- Cell Culture Market Analysis by Application
- Bioproduction is further segmented into Monoclonal Antibody Production, Therapeutic Protein Production, Vaccine Production, and Cell & Gene Therapy Manufacturing, while Research Applications are further segmented into Cancer Research, Stem Cell Research, Drug Screening & Toxicology, and Other Research.
- Other Applications include cultivated food and industrial biotechnology.
- The Bioproduction segment is expected to account for the largest share of the market.
- The large share of this segment is mainly due to the volume of media and single-use consumables consumed in commercial and clinical biologics manufacturing, the scale of monoclonal antibody and therapeutic protein production, and the recovery in bioprocessing demand following the conclusion of customer destocking.
- Within bioproduction, Cell & Gene Therapy Manufacturing is projected to register the highest CAGR during the forecast period, attributed to the pipeline reaching registration, the high media and consumable cost per batch in these processes, and the transition of approved products into recurring commercial supply.
- The Research Applications segment is expected to grow steadily, supported by three-dimensional culture adoption and by regulatory recognition of human cell-based testing methods.
By End User
- Other End Users include diagnostic companies, cultivated food companies, and industrial biotechnology organizations.
- The Pharmaceutical & Biotechnology Companies segment is expected to account for the largest share of the market.
- The large share of this segment is mainly due to their ownership of commercial biologics manufacturing capacity, the scale of in-house production of antibodies and therapeutic proteins, and their research activity in addition to manufacturing.
- However, the Contract Development & Manufacturing Organizations segment is projected to register the highest CAGR during the forecast period.
- The rapid growth of this segment is attributed to the continuing outsourcing of biologics and advanced therapy manufacturing, the concentration of cell and gene therapy production in contract facilities, and sustained capacity investment by these organizations.
- In the first half of 2026, Lonza Group AG reported sales of CHF 3.4 billion, up 16.0% at constant exchange rates, with all business platforms growing at double-digit rates, raised its full-year CORE EBITDA margin guidance to 33-34%, and brought its large-scale mammalian asset in Visp, Switzerland into commercial operation as planned.
Geographic analysis
North America
Largest shareIn 2026, North America is expected to account for the largest share of the global Cell Culture Market. The large share of this region is mainly attributed to the concentration of biologics and advanced therapy manufacturing capacity, the number of products in clinical development and reaching registration, substantial research activity, and the presence of leading suppliers including Thermo Fisher Scientific, Danaher through Cytiva, Corning, Becton Dickinson, Avantor, and Bio-Rad Laboratories. In May 2026, the FDA Center for Biologics Evaluation and Research issued final guidance that removed the fixed requirement for three process performance qualification lots for process validation of cell and gene therapy products and permitted concurrent validation and release, while noting that changes in source materials, such as a switch from fetal bovine serum to human albumin, require comparability studies.
Europe
Europe is expected to account for a significant share of the market, supported by substantial biologics and contract manufacturing capacity, the presence of major suppliers including Merck KGaA, Sartorius, Eppendorf, Greiner Bio-One, and Getinge, and contract manufacturing capability including Lonza. In the second quarter of 2026, Merck KGaA reported Life Science net sales of EUR 2.4 billion, up 8.0% organically, with its Process Solutions business unit growing 14.7% organically to EUR 1.07 billion, led by downstream processing and single-use solutions, and upgraded its full-year Life Science guidance to net sales of approximately EUR 9.3-9.6 billion with organic growth of 5% to 7%. In September 2026, the FDA announced a direct final rule replacing the terms animal tests and animal studies with nonclinical tests and nonclinical studies throughout its regulations, clarifying that non-animal methods including human cell-based platforms and organ-on-chip systems can be used where appropriate to test the safety of drugs and biological products, and in June 2026 the European Commission published its roadmap towards phasing out animal testing for chemical safety assessments across 15 regulatory domains.
Asia-Pacific
Fastest growthAsia-Pacific is projected to register the highest CAGR during the forecast period. The growth of this region is driven by biologics and biosimilar manufacturing capacity expansion in China, India, and South Korea, government industrial policy supporting biomanufacturing, the growth of contract manufacturing serving both domestic and international clients, the scale of vaccine production in the region, and the qualification of regional media and consumable suppliers as manufacturers seek geographic diversity of supply.
Latin America
Latin America and the Middle East & Africa are expected to account for smaller shares of the market. In Latin America, vaccine and biosimilar manufacturing in Brazil and Mexico is expected to support demand, while in the Middle East, investment in local biomanufacturing capability in Gulf countries and in Saudi Arabia in particular is expected to support growth.
Competitive landscape
The global Cell Culture Market is moderately consolidated, with a group of diversified life science suppliers holding substantial shares across media, reagents, and single-use consumables, alongside equipment specialists, cell therapy reagent providers, and regional media manufacturers. Market participants compete on media performance and yield, lot-to-lot consistency, regulatory support documentation and change control, security and geographic diversity of supply, custom formulation and process development capability, single-use portfolio breadth, and total cost of ownership.
Leading companies are expanding media and single-use manufacturing capacity, developing chemically defined and xeno-free formulations for advanced therapy applications, investing in process development and custom formulation services, establishing regional manufacturing to address supply security requirements, and developing products for three-dimensional culture and human cell-based testing. Recent market context includes organic growth of 14.7% in Process Solutions at Merck KGaA in the second quarter of 2026 led by single-use solutions, constant-currency growth of 8.1% in Bioprocess Solutions at Sartorius in the first quarter of 2026 with full-year consumables-led guidance of 6% to 10%, and the commissioning of large-scale mammalian capacity by Lonza in Visp.
The report provides a comprehensive competitive assessment of the leading companies operating in the global Cell Culture Market. The key players profiled in the report include Thermo Fisher Scientific Inc. (U.S.), Merck KGaA (Germany), Danaher Corporation (Cytiva) (U.S.), Sartorius AG (Germany), Lonza Group AG (Switzerland), Corning Incorporated (U.S.), Becton, Dickinson and Company (U.S.), Avantor, Inc. (U.S.), Bio-Rad Laboratories, Inc. (U.S.), Agilent Technologies, Inc. (U.S.), Eppendorf SE (Germany), FUJIFILM Holdings Corporation (Japan), Getinge AB (Sweden), Greiner Bio-One International GmbH (Austria), Miltenyi Biotec B.V. & Co. KG (Germany), and HiMedia Laboratories Pvt. Ltd. (India).
- Thermo Fisher Scientific Inc.
- Merck KGaA
- Danaher Corporation · Cytiva
- Sartorius AG
- Lonza Group AG
- Corning Incorporated
- Becton
- Dickinson and Company
- Avantor, Inc.
- Bio-Rad Laboratories, Inc.
- Agilent Technologies, Inc.
- Eppendorf SE
- FUJIFILM Holdings Corporation
- Getinge AB
- Greiner Bio-One International GmbH
- Miltenyi Biotec B.V. & Co. KG
- HiMedia Laboratories Pvt. Ltd
Expert perspectives
The Cell Culture Market has emerged from a period in which reported results said more about customer inventories than about underlying demand. With Process Solutions at Merck KGaA growing 14.7% organically and Bioprocess Solutions at Sartorius growing 8.1% in constant currencies with consumables-led full-year guidance of 6% to 10%, destocking has concluded and supplier revenues once again track biomanufacturing output. The binding constraint is shifting from inventory correction to the composition and security of supply, because a manufacturer that has qualified a formulation cannot readily change it, which makes media selection a decision with consequences across a product lifecycle.
Three structural changes are expected to shape competitive positions through 2036. First, the transition to chemically defined and xeno-free formulations is expected to continue and to raise average selling prices, favouring suppliers with defined-media development capability. Second, cell and gene therapy manufacturing is expected to grow fastest and to consume media at a far higher value per batch than conventional biologics, which rewards suppliers able to serve small-batch, highly documented processes. Third, regulatory recognition of human cell-based testing methods is expected to create research demand for culture products from a source outside biomanufacturing entirely.
For companies planning entry or expansion, the most defensible positions over the forecast period are likely to be found in chemically defined and xeno-free media for advanced therapy manufacturing, custom formulation and process development services, three-dimensional culture and organoid consumables, single-use systems for small-batch production, and regional manufacturing serving supply security requirements in Asia-Pacific. For established suppliers, the principal priorities are demonstrating supply resilience, deepening process development relationships that insulate against price competition, and addressing the sustainability profile of single-use systems.
Overall, the market is expected to grow strongly, with media, mammalian cells, bioproduction applications, and pharmaceutical and biotechnology companies in North America providing the core of demand, and serum-free and chemically defined formulations, human primary and stem cells, cell and gene therapy manufacturing, contract development and manufacturing organizations, and Asia-Pacific providing the fastest growth.
Customer perspectives
Insights gathered during primary interviews with biologics manufacturing leaders, cell therapy process development heads, and procurement directors highlight where priorities are shifting. The following perspectives reflect recurring themes raised across these discussions.
“This reflects performance rather than price as the purchasing basis.”
“This indicates why defined formulations are adopted early.”
“This points to supply security as a qualification requirement.”
Frequently asked questions
The global Cell Culture Market is estimated at USD 32.84 billion in 2026.
Cite this report
Meticulous Research. (2026). Cell Culture Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MRHC - 104127). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/cell-culture-market-4788