Cancer/Tumor Profiling Market (2024-2031)
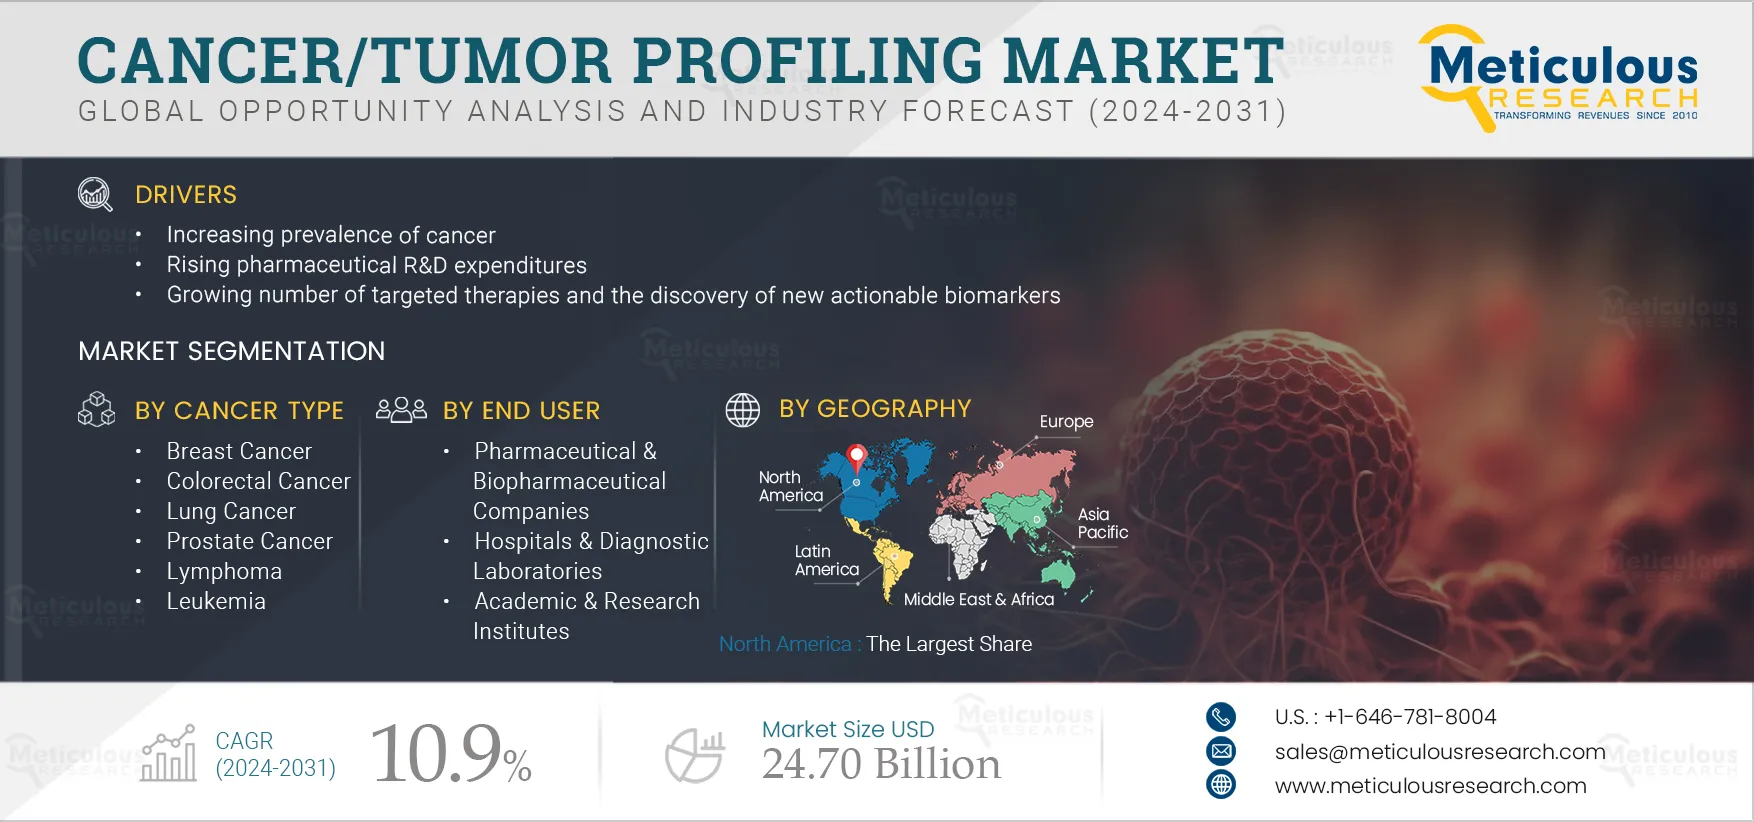
The Cancer/Tumor Profiling Market is projected to reach $24.70 billion by 2031 at a CAGR of 10.9% from 2024 to 2031.
- Published
- Jul 2024
- Pages
- 270
- Format
- PDF + Excel
- Report ID
- MRHC - 104947
- Base year
- 2023
- 2031 · FORECAST
- $24.70B
- 2031
- $24.70B
- CAGR 2024–2031
- 10.9%
2023 baseline · 2024–2031 forecast at 10.9% CAGR · hover a bar for the value
Key highlights
Based on Biomarker Type, the Genetic Biomarkers Segment is Expected to Account for the Largest Share of the Market in 2024
Based on Technology, the Next-Generation Sequencing (NGS) Segment is Expected to Account for the Largest Share of the Market in 2024
Based on Cancer Type, the Breast Cancer Segment is Expected to Account for the Largest Share of the Market in 2024
Based on Application, the Research Applications Segment is Expected to Account for the Largest Share of the Market in 2024
Based on End User, the Pharmaceutical & Biopharmaceutical Companies Segment is Expected to Account for the Largest Share of the Market in 2024
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 270 |
| Format | |
| Forecast Period | 2024-2031 |
| Base Year | 2023 |
| CAGR | 10.9% |
| Estimated Market Size (Value) | $24.70 billion by 2031 |
| Segments Covered | By Biomarker Type · Protein Biomarkers · Genetic Biomarkers · By Technology · Next-Generation Sequencing (NGS) · Polymerase Chain Reaction (PCR) · In-situ hybridization (ISH) · Immunohistochemistry (IHC) · Other Technologies · (Note: Other technologies include immunoassays, microarrays, mass spectrometers, Sanger sequencing, pyrosequencing, and fragment analysis) · By Application · Clinical Applications · Research Applications · By Cancer Type · Breast Cancer · Colorectal Cancer · Lung Cancer · Prostate Cancer · Lymphoma · Leukemia · Cervical Cancer · Other Cancer Types · (Note: Other cancer types include bladder cancer, melanoma, kidney cancer, stomach cancer, ovarian cancer, thyroid cancer, and head & neck cancers) · By End User · Pharmaceutical & Biopharmaceutical Companies · Hospitals & Diagnostic Laboratories · Academic & Research Institutes · Contract Research Organizations (CROs) |
| Countries Covered | North America (U.S. and Canada), Europe (Germany, France, U.K., Italy, Spain, and Rest of Europe), Asia-Pacific (Japan, China, India, and Rest of Asia-Pacific), Latin America and Middle East & Africa |
| Key Companies | The key players operating in the global cancer/tumor profiling market are Thermo Fisher Scientific Inc. (U.S.), Illumina, Inc. (U.S.), QIAGEN N.V. (Netherlands), F. Hoffmann-La Roche Ltd. (Switzerland), Agilent Technologies, Inc. (U.S.), NanoString Technologies, Inc. (U.S.), HTG Molecular Diagnostics, Inc. (U.S.), Agendia Inc. (U.S.), Personalis, Inc. (U.S.), Exact Sciences Corporation (U.S.), and Tempus Labs, Inc. (U.S.). |
Report overview
Segments covered: biomarker type. Regions: North America, Europe, Asia-Pacific.
The rise in cancer cases, the growing research of novel molecules, and the increasing number of genomic research projects have increased the demand for cancer/tumor profiling. The emergence of tumor profiling has removed the restraints of traditional cancer/tumor classification approaches, which rely on the morphology of the cancerous cells and the surrounding tissues. Today, cancer/tumor profiling is accepted as the standard technique for classifying tumors, with the guidelines associated with the European Society for Molecular Oncology (ESMO) and the College of American Pathologists (CAP).
The profiling of tumors with advanced technologies such as ISH, NGS, IHC, and PCR has successfully analyzed the genes, amplicons, and gene regions with familiar involvement with tumors. This approach, also known as targeted treatment, delivers high sensitivity for detecting tumor subclones or rare mutations, providing increased visibility regarding important mutations acting as drivers of cancer.
The growth of the cancer/tumor profiling market is attributed to the increasing prevalence of cancer, the rising pharmaceutical R&D expenditures, the growing number of targeted therapies and the discovery of new actionable biomarkers, increasing investments in cancer research, the declining costs of NGS-based profiling, and advancements in multi-omics tumor profiling. However, the high capital investments required for NGS setups and long turnaround times restrain the growth of this market.
Additionally, the increasing focus on developing personalized medicines and the rising awareness and adoption of targeted therapies are expected to generate market growth opportunities. However, the lack of genetic experts for interpreting results, the non-availability of in-house tumor profiling technologies, and the high number of false biomarker discoveries are major challenges for the stakeholders in the cancer/tumor profiling market.
Report infographic
Market dynamics
4 factors across 2 forcesAdvancements in Multi-omics Tumor Profiling and Cancer Research
Cancer research has benefited from the advancement in omics technologies from genomics to transcriptomics and from a wide variety of resources obtained from multiple omics datasets originating from the patients. Multi-omics approaches offer a unique opportunity to identify cancer patients' clinical and molecular features. In transcriptomics and genomics, there is an unmet need to distinguish between inconsistency in related biological procedures, like differences in variability or post-translational changes in the expression profiles due to the role of mRNA transcripts in the development of cancer.
Recent advancements in proteomics have facilitated the emergence of proteogenomic approaches. These approaches seamlessly integrate genomic data with proteomics data, including insights into post-translational modifications such as acetylation and protein phosphorylation. These developments in multi-omics tumor profiling and cancer research are expected to drive the growth of the cancer/tumor profiling market.
Increasing Prevalence of Cancer
The burden of cancer is growing globally. According to GLOBOCAN 2020, cancer incidence is expected to increase from 19.3 million in 2020 to 30.2 million in 2040. Moreover, the mortality due to cancer is estimated to increase from 9.9 million in 2020 to 16.3 million in 2040. Nearly 70% of the total deaths due to cancer occur in low and middle-income countries. Early detection is extremely important in reducing mortality, improving patients’ chances of survival, and saving on treatment costs. Various methods are used to detect cancer. The demand for cancer/tumor profiling for cancer diagnosis is expected to grow significantly in the coming years.
Advancements in Multi-omics Tumor Profiling
During the last decade, genomics and proteomics approaches have become effective and crucial tools in the clinical research of biological pathways involved in cancer pathogen replication, host response, and disease progression. Genomics and proteomics are important for discovering and understanding host-pathogen interactions. They offer the opportunity to improve personalized treatments and disease prevention in advanced cancer cases. Genomics primarily aims to sequence, assemble, and analyze the functions and structures of genomes. At the same time, proteomics helps in the large–scale study of the complete set of proteins within an organism. Such developments in genomics and proteomics are expected to drive the cancer/tumor profiling market.
Table of contents
13 chapters · 108 sections · 270 pages · click to expandSegmental analysis
| Segment | Largest share (2024) | Fastest growth (2024–2031) |
|---|---|---|
| By Biomarker Type | Genetic Biomarkers | — |
| By Technology | Next-Generation Sequencing (NGS) | — |
| By Cancer Type | Breast Cancer | — |
| By Application | Research Applications | — |
| By End User | Pharmaceutical & Biopharmaceutical Companies | — |
By Biomarker Type
- The genetic biomarkers segment is expected to account for the largest share of 72.0% of the cancer/tumor profiling market.
- The large market share of this segment is attributed to the benefits offered by genetic biomarkers, including their reliability in identifying drug-resistant cancer cells, assisting in identifying genetic patterns responsible for future cancer recurrence, and their increased use for the early detection of cancer.
By Technology
- The next-generation sequencing (NGS) segment is expected to account for the largest share of the cancer/tumor profiling market.
- The large market share of this segment is attributed to the benefits offered by NGS, such as high-throughput production, efficient instrument runs, and cost-effectiveness compared to traditional first-generation sequencing methods.
- Additionally, NGS is highly preferred for large-scale genomic profiling and transcriptomic sequencing.
By Cancer Type
- The breast cancer segment is expected to account for the largest share of the cancer/tumor profiling market.
- The large market share of this segment is attributed to the rising incidence of breast cancer cases and the increasing adoption of tumor profiling for breast cancer.
By Application
- The research applications segment is expected to account for the largest share of the cancer/tumor profiling market.
- The large market share of this segment is attributed to the decreasing cost of sequencing procedures, the rising research and development efforts by pharmaceutical and biopharmaceutical companies in drug and biomarker discovery, the high sensitivity and throughput offered by advanced profiling technology, and the expanding applications of cancer/tumor profiling in various clinical and research areas.
By End User
- The pharmaceutical & biopharmaceutical companies segment is expected to account for the largest share of 40.9% of the cancer/tumor profiling market.
- The large market share of this segment is attributed to the declining costs of sequencing, the increase in research and development activities by pharmaceutical and biopharmaceutical companies, and the extensive utilization of advanced profiling solutions for cancer studies.
Geographic analysis
North America
Largest shareIn 2024, North America is expected to account for the largest share of 42.7% of the cancer/tumor profiling market. North America’s significant market share can be attributed to the high prevalence of cancer, substantial healthcare expenditure, widespread adoption of advanced molecular technologies, and substantial investment in pharmaceutical R&D.
Competitive landscape
- May 2023
Thermo Fisher Scientific Inc. (U.S.) launched the Orbitrap Astral mass spectrometer, which combines high sensitivity, fast throughput, and deep proteome coverage, allowing researchers to identify new clinical biomarkers and develop new interventions from cardiovascular disease to cancer.
- March 2023
Thermo Fisher Scientific Inc. (U.S.) collaborated with Arsenal Biosciences, Inc. (U.S.), a clinical-stage cell therapy company operating in solid tumor therapies for developing advanced manufacturing processes for new cancer treatments.
- March 2023
Illumina, Inc. (U.S.) partnered with Myriad Genetics, Inc. (U.S.) to expand the partnership for broadening the accessibility and availability of oncology homologous recombination deficiency (HRD) testing in the U.S. This partnership also opened new doors for companion diagnostic (CDx) alliance for the pharmaceutical industry, enabling clinical research in gene-based and targeted therapies.
- September 2022
Illumina, Inc. (U.S.) launched its NovaSeq 6000 Dx, the first FDA-registered and CE-marked in vitro diagnostic (IVD) high-throughput sequencer, along with Illumina Complete Long-Reads, XLEAP-SBS Chemistry, NextSeq 1000/2000 Roadmap, and NovaSeq X Series (NovaSeq X and NovaSeq X Plus).
- Thermo Fisher Scientific Inc. (U.S.)
- Illumina, Inc. (U.S.)
- QIAGEN N.V. · Netherlands
- F. Hoffmann-La Roche Ltd. · Switzerland
- Agilent Technologies, Inc. (U.S.)
- NanoString Technologies, Inc. (U.S.)
- HTG Molecular Diagnostics, Inc. (U.S.)
- Agendia Inc. (U.S.)
- Personalis, Inc. (U.S.)
- Exact Sciences Corporation (U.S.)
- Tempus Labs, Inc. (U.S.)
Frequently asked questions
The global cancer/tumor profiling market report covers the qualitative analysis and market sizing of biomarker type, cancer type, technology, application, and end user. This report involves the analysis of various segments of cancer/tumor profiling at the regional and country level. The report also provides insights on factors impacting market growth, factor analysis, case studies, regulatory analysis, pricing analysis, and Porter’s five forces analysis.
Cite this report
Meticulous Research. (2024). Cancer/Tumor Profiling Market - Global Opportunity Analysis and Industry Forecast (2024-2031) (Report No. MRHC - 104947). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/cancer-tumor-profiling-market-5630