Building Insulation Systems Market (2026-2036)
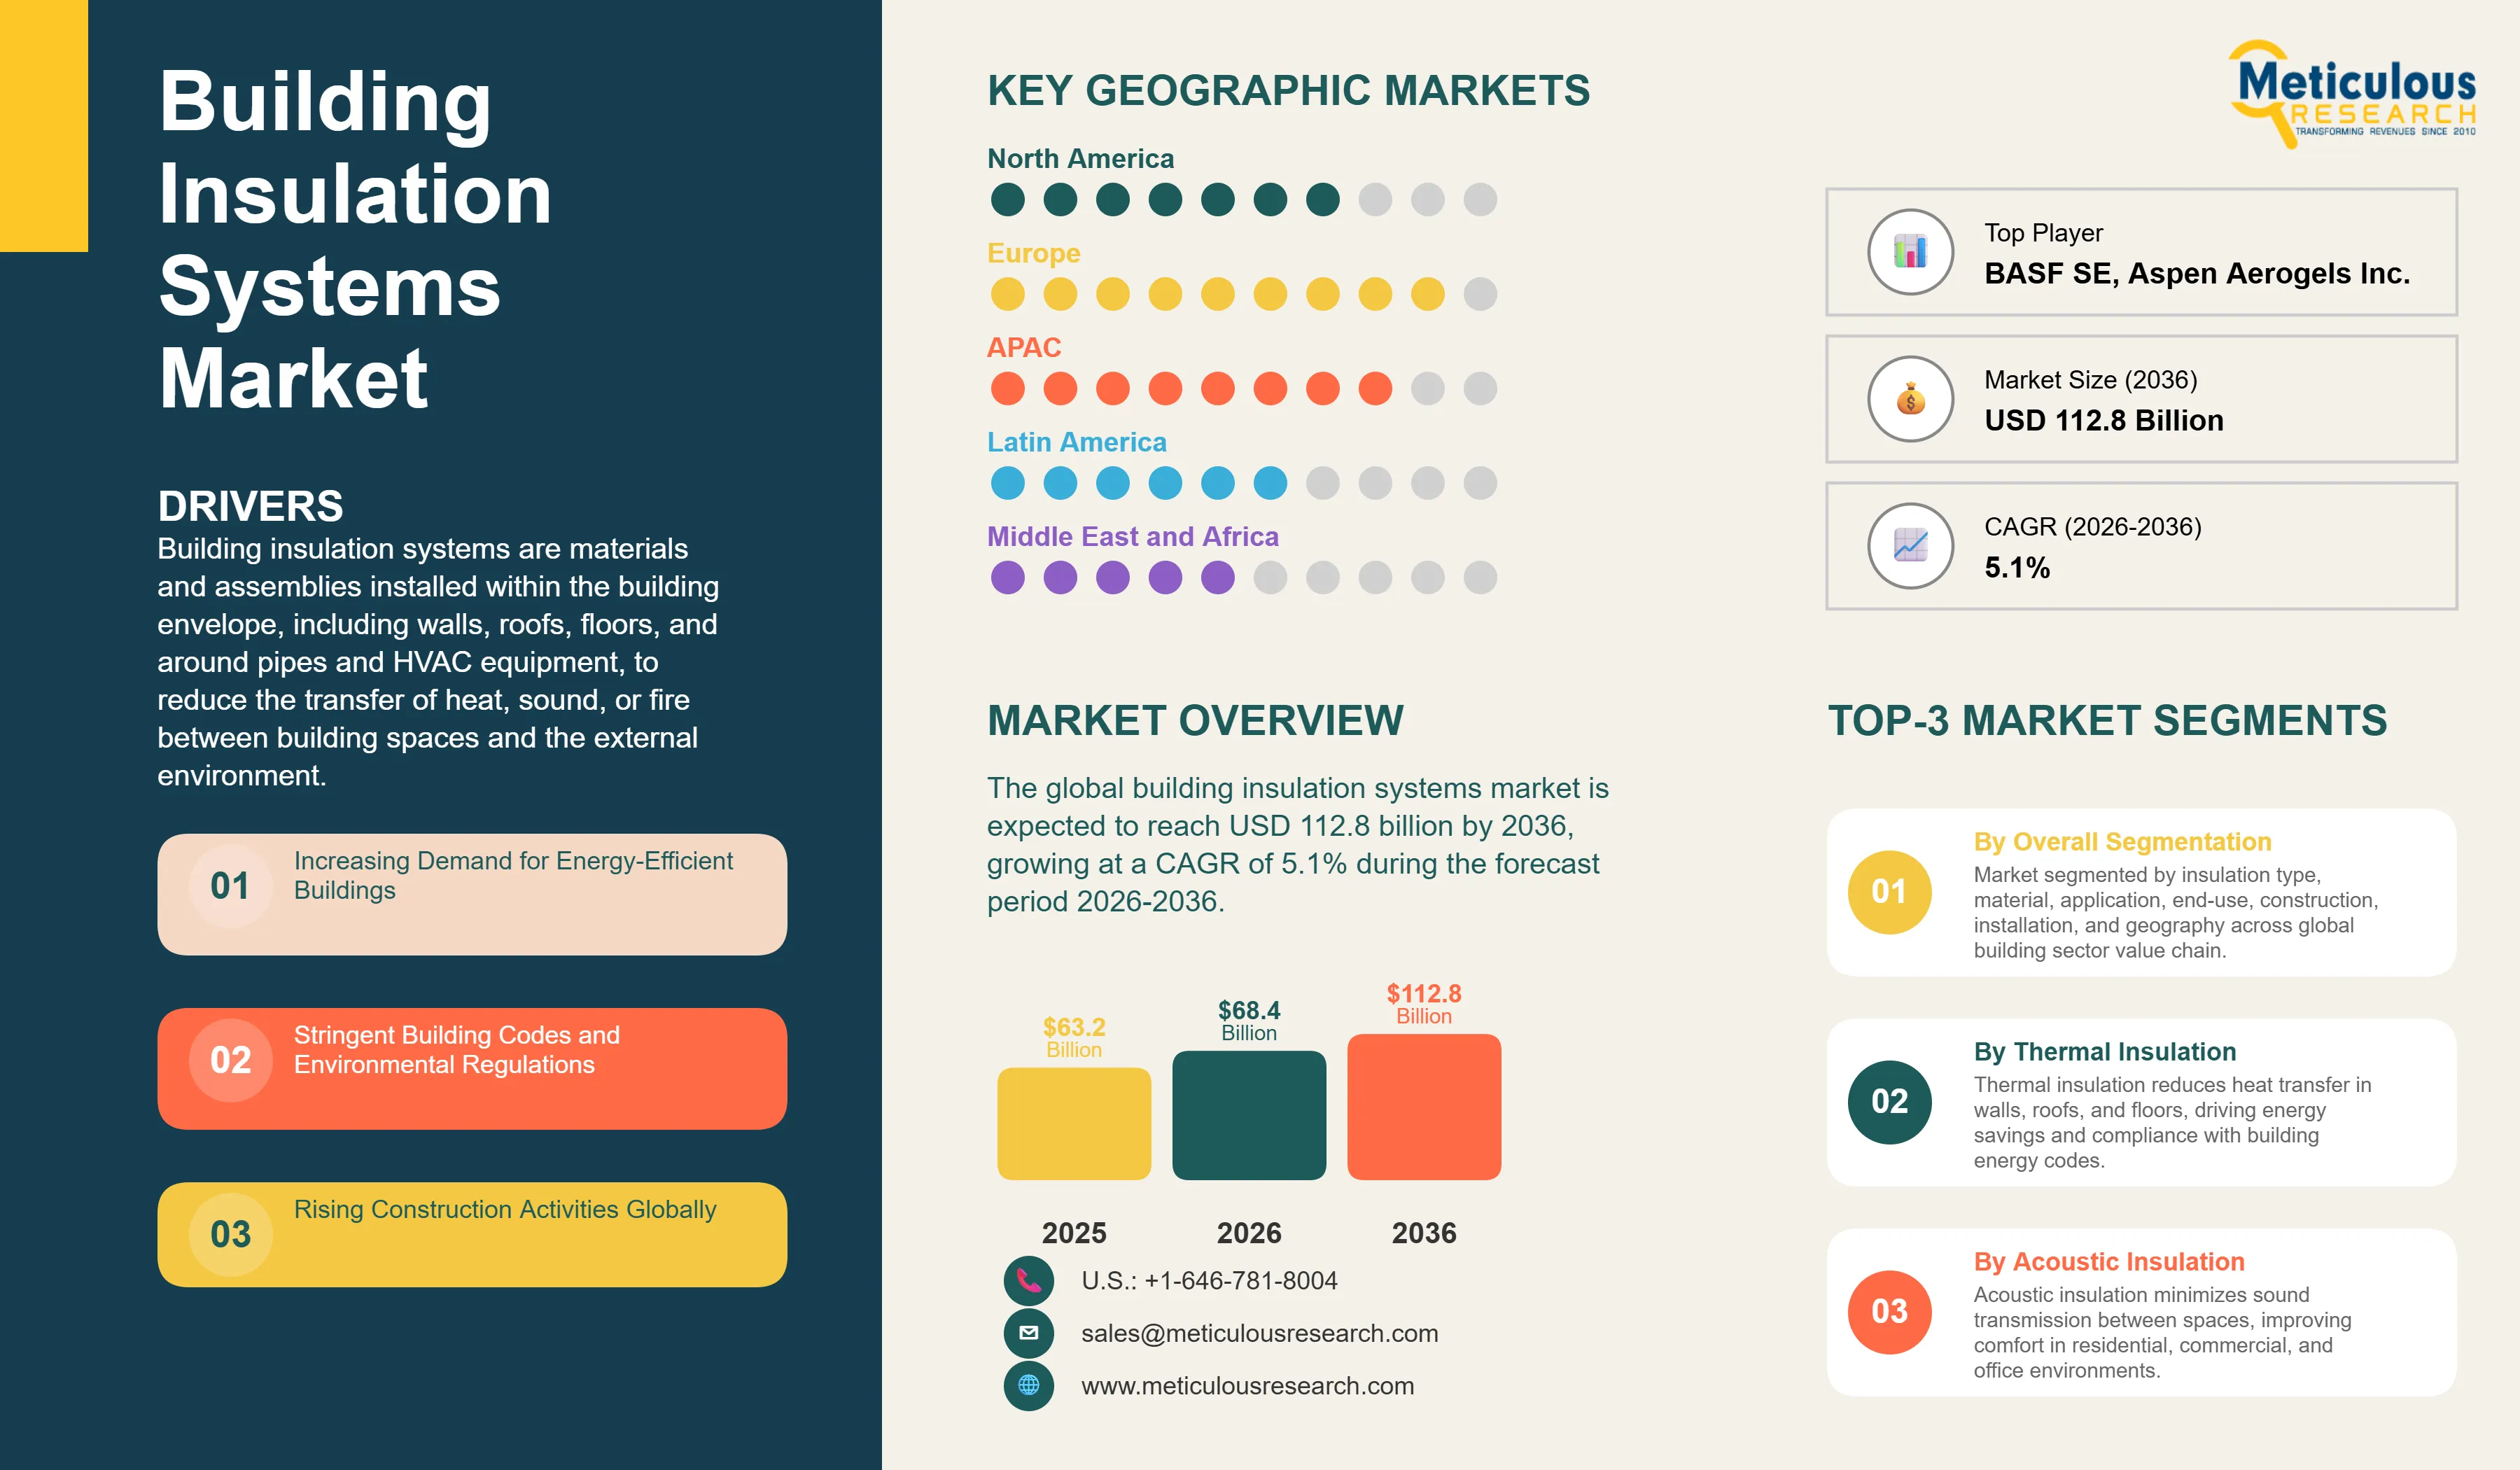
The global building insulation systems market was valued at USD 63.2 billion in 2025. This market is expected to reach USD 112.8 billion by 2036 from an estimated USD 68.4 billion in 2026, growing at a CAGR of 5.1% during the forecast period 2026-2036.
- Published
- Apr 2026
- Pages
- 270
- Format
- PDF + Excel
- Report ID
- MRSE - 1041945
- Base year
- 2025
- 2025 · BASELINE
- $63.20B
- 2036
- $112.8B
- CAGR 2026–2036
- 5.1%
2025 baseline · 2026–2036 forecast at 5.1% CAGR · hover a bar for the value
Key highlights
The global building insulation systems market is projected to reach USD 112.8 billion by 2036.
The market is expected to grow at a CAGR of 5.1% during the forecast period 2026-2036.
The global building insulation systems market was valued at USD 63.2 billion in 2025 and is estimated to reach USD 68.4 billion in 2026.
Europe is expected to dominate the global building insulation systems market with the largest market share in 2026, while Asia-Pacific is projected to register the highest CAGR during the forecast period.
By insulation type, the thermal insulation segment is expected to hold the largest share of the market in 2026, while the fire-resistant insulation segment is projected to register the highest CAGR during the forecast period.
By material type, the mineral wool segment is expected to hold the largest share in 2026, while the advanced materials (aerogels and VIPs) segment is projected to register the highest CAGR during the forecast period.
By application, the walls segment is expected to hold the largest share in 2026, while the HVAC and pipes segment is projected to register the highest CAGR during the forecast period.
By end-use sector, the residential buildings segment is expected to hold the largest share in 2026, while the commercial buildings segment is projected to register the highest CAGR during the forecast period.
By construction type, the new construction segment is expected to hold the largest share in 2026, while the renovation and retrofit segment is projected to register the highest CAGR during the forecast period.
By installation type, the post-installed systems segment is expected to hold the largest share in 2026, while the pre-installed systems segment is projected to register the highest CAGR during the forecast period.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 112.8 Billion |
| Market Size in 2026 | USD 68.4 Billion |
| Market Size in 2025 | USD 63.2 Billion |
| Revenue Growth Rate (2026-2036) | CAGR of 5.1% |
| Format | PDF, Excel & Cloud Portal · 270 pages |
| Dominating Insulation Type | Thermal Insulation |
| Fastest Growing Insulation Type | Fire-Resistant Insulation |
| Dominating Material Type | Mineral Wool |
| Fastest Growing Material Type | Advanced Materials (Aerogels, VIPs) |
| Dominating Application | Walls |
| Fastest Growing Application | HVAC and Pipes |
| Dominating End-Use Sector | Residential Buildings |
| Fastest Growing End-Use Sector | Commercial Buildings |
| Dominating Construction Type | New Construction |
| Fastest Growing Construction Type | Renovation and Retrofit |
| Dominating Installation Type | Post-Installed Systems |
| Fastest Growing Installation Type | Pre-Installed Systems |
| Dominating Geography | Europe |
| Fastest Growing Geography | Asia-Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
Report overview
Segments covered: insulation type, material type, application, end-use sector.
Buildings account for approximately 36% of global final energy consumption and nearly 40% of energy-related carbon dioxide emissions, according to the International Energy Agency, making building insulation one of the most commercially impactful segments of the broader energy transition.
Building insulation systems are materials and assemblies installed within the building envelope, including walls, roofs, floors, and around pipes and HVAC equipment, to reduce the transfer of heat, sound, or fire between building spaces and the external environment. Effective thermal insulation keeps buildings warm in winter and cool in summer, cutting heating and cooling energy demand by 30 to 50% compared with uninsulated structures, according to the European Insulation Manufacturers Association. Beyond energy savings, insulation improves occupant comfort, reduces condensation and moisture damage, and provides fire containment and acoustic privacy. Given that a poorly insulated home can lose up to 35% of its heat through the roof and 25% through walls, quality insulation installation is one of the highest-return energy efficiency investments available.
The market is growing because governments globally are tightening building energy performance standards at an accelerating pace. The European Union's Energy Performance of Buildings Directive now requires all new buildings to be nearly zero energy buildings, directly mandating higher insulation standards across the 27-member bloc. In the U.S., the Department of Energy's adoption of ASHRAE 90.1-2022 energy efficiency standards in federal buildings is driving specification upgrades across the commercial sector. The U.S. Inflation Reduction Act of 2022 allocated over USD 4 billion in tax rebates for home energy efficiency improvements including insulation, creating direct consumer demand. China's 14th Five-Year Plan sets explicit energy intensity reduction targets for buildings that require substantial insulation upgrades across its enormous new construction pipeline. These regulatory and financial incentives are creating a sustained, policy-backed demand environment across all major markets simultaneously.
Two major opportunities are shaping the market's next phase. The retrofitting of Europe's 220 million existing buildings, over 75% of which are considered energy inefficient by EU standards, represents what the European Commission has called the largest investment opportunity in the building sector in decades. The EU's Renovation Wave strategy targets doubling the energy renovation rate from 1% to at least 2% annually by 2030. Simultaneously, aerogel-based insulation materials, which offer thermal performance up to ten times better than conventional mineral wool at the same thickness, are transitioning from aerospace and industrial niche applications to broader building use. Aspen Aerogels reported aerogel building product revenues growing over 40% year-on-year in recent results, signaling the commercial momentum building in this premium segment.
Report infographic
Market dynamics
7 factors across 3 forcesIncreasing Demand for Energy-Efficient Buildings
Buildings consume approximately 36% of global final energy, with heating and cooling accounting for roughly half of that consumption according to IEA data. The direct link between insulation quality and energy consumption means that every improvement in building insulation standards translates directly into measurable energy savings and carbon emission reductions. A home insulated to current best-practice standards can reduce heating energy demand by 50 to 80% compared with a typical building constructed before 2000. For homeowners, this translates into significant energy bill reductions: the U.S. Department of Energy estimates that a well-insulated and air-sealed home can save 15% or more on heating and cooling costs. As energy prices remain elevated globally and as household energy affordability becomes a political priority, the financial case for insulation investment is stronger than it has been in decades, driving both new installation and retrofit demand across all building types.
Stringent Building Codes and Environmental Regulations
Building energy codes are becoming progressively more stringent in every major construction market globally, and compliance with these codes requires increasingly high levels of insulation performance. The EU's Energy Performance of Buildings Directive mandates that all new buildings must be nearly zero energy buildings, and the revised directive published in 2024 tightens these requirements further. In the U.S., the International Energy Conservation Code is updated every three years with increasingly demanding insulation requirements, and over 90% of U.S. states have adopted versions of this code. California's Title 24 building energy standards are among the world's most demanding, requiring very high levels of wall, roof, and foundation insulation in new construction. Australia's National Construction Code 7-Star energy rating requirement for new homes, introduced in 2023, has significantly increased insulation specification in a market where thin wall insulation was previously common. Each regulatory tightening in these markets creates a direct procurement demand for better-performing insulation products.
Table of contents
14 chapters · 174 sections · 270 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Insulation Type | Thermal Insulation | Fire-resistant insulation |
| By Material Type | Mineral Wool | Advanced materials (aerogels and VIPs) |
| By Application | Walls | HVAC and pipes |
| By End-Use Sector | Residential Buildings | Commercial buildings |
By Insulation Type
- Thermal Insulation to Dominate
- The thermal insulation segment is expected to account for the largest share of the global building insulation systems market.
- Reducing heat transfer is the primary function of building insulation in the vast majority of applications globally, and thermal insulation products represent the largest procurement category by volume and value.
- The direct link between thermal insulation quality and building energy consumption, combined with rising energy costs and tightening building energy codes, ensures that thermal insulation remains the dominant application driver across all markets and building types.
- However, the fire-resistant insulation segment is projected to register the highest CAGR during the forecast period.
- Following high-profile fire incidents in multi-story residential buildings, including the Grenfell Tower fire in London in 2017 that claimed 72 lives and led to a comprehensive review of building cladding and insulation fire performance requirements across the UK and internationally, fire safety has become a primary specification criterion for insulation materials in multi-family residential and commercial buildings.
- The resulting regulatory changes mandating non-combustible or limited-combustibility insulation in buildings above certain heights have created strong and sustained demand growth for mineral wool and other fire-resistant insulation products.
By Material Type
- Mineral Wool to Hold the Largest Share
- The mineral wool segment is expected to account for the largest share of the global building insulation systems market.
- Glass wool and stone wool collectively represent the most widely used building insulation material globally, valued for their combination of thermal performance, fire resistance, acoustic absorption, and competitive cost.
- Rockwool International, which produces stone wool insulation under its Rockwool and Roxul brands, serves customers in over 40 countries and reported revenues of approximately EUR 3.8 billion in 2023, making it the world's largest dedicated insulation manufacturer and illustrating the commercial scale of the mineral wool market.
- However, the advanced materials segment, particularly aerogels and vacuum insulated panels, is projected to register the highest CAGR during the forecast period.
- As aerogel production costs fall with manufacturing scale-up and as the premium performance of these materials becomes better understood among architects and contractors, adoption in building applications is accelerating.
- The retrofit market in particular is creating strong commercial pull for ultra-thin high-performance insulation that can improve building thermal performance without consuming valuable interior floor space.
By Application
- Walls to Hold the Largest Share
- The walls segment is expected to account for the largest share of the global building insulation systems market.
- Wall insulation covers by far the largest surface area in most building types and represents the single most impactful insulation application by both heat loss reduction potential and total material volume.
- External wall insulation systems, where insulation boards are fixed to the outside of the existing wall and covered with a render or cladding finish, have become the dominant retrofit insulation solution in Europe, with the European market for these systems growing strongly driven by renovation programs.
- However, the HVAC and pipes segment is projected to register the highest CAGR during the forecast period.
- The rapid growth of district energy networks, the expansion of industrial and commercial HVAC infrastructure, and growing awareness of heat loss and condensation risks in uninsulated pipework are driving above-average growth in pipe and duct insulation.
- Armacell, the world's leading flexible foam insulation manufacturer, has specifically highlighted HVAC and technical insulation as its fastest-growing product category, with the segment benefiting from both new installation demand and significant retrofit activity in energy system optimization programs.
By End-Use Sector
- Residential Buildings to Hold the Largest Share
- The residential buildings segment is expected to account for the largest share of the global building insulation systems market.
- Housing construction and renovation represent the largest single source of insulation demand globally by volume, driven by the very large number of housing units built and renovated each year, the strong government support for residential energy efficiency improvements in most major markets, and the high political priority attached to household energy affordability.
- In the U.S. alone, residential buildings account for 21% of total energy consumption, and improving home insulation is among the most cost-effective interventions available for reducing energy bills and carbon emissions.
- However, the commercial buildings segment is projected to register the highest CAGR during the forecast period.
- New commercial construction is growing rapidly, particularly in data centers where the thermal management requirements are extreme, in logistics and warehousing where large floor areas require significant insulation to meet energy codes, and in healthcare and laboratory facilities where precise temperature control requires high-performance building envelopes.
- The commercial sector's larger average building size means that individual project insulation procurement values are significantly higher than in residential construction, driving strong revenue growth.
Geographic analysis
Europe
Largest shareIn 2026, Europe is expected to account for the largest share of the global building insulation systems market. Europe leads because it has the most stringent building energy performance regulations of any region, the most mature and policy-driven renovation market, and the highest per-square-meter insulation performance requirements in new construction. Germany is the largest European market, driven by its very large new construction and renovation volumes and its Federal Funding for Efficient Buildings program that disbursed over EUR 13 billion in energy efficiency grants in 2022 alone. France's RE2020 regulation, which came into force for new residential buildings in January 2022, introduces carbon lifecycle requirements in addition to energy performance standards that are already driving specification shifts in insulation materials. The UK's revised building regulations and ambitious national retrofit programs are creating sustained demand across Britain's housing stock of over 28 million homes, approximately 19 million of which are estimated to have energy ratings of D or below according to the UK Department for Energy Security and Net Zero. Scandinavia, particularly Sweden and Norway, maintains among the world's highest insulation performance standards and is an important market for premium insulation products and innovative installation systems.
Asia-Pacific
Fastest growthHowever, the Asia-Pacific building insulation systems market is expected to grow at the fastest CAGR during the forecast period. China is both the world's largest construction market by volume, with annual new building completions exceeding 2 billion square meters at the peak of the construction cycle, and a country that has recently established ambitious building energy efficiency policies including the requirement for green building certification for all new urban buildings by 2025. India is experiencing one of the fastest rates of urbanization in the world, with over 500 million people expected to live in cities by 2050 according to United Nations projections, driving an enormous new construction pipeline. India's construction sector is also increasingly adopting energy efficiency requirements, with the Energy Conservation Building Code being strengthened and extended to residential buildings. Rapidly growing economies in Southeast Asia including Vietnam, Indonesia, and Thailand are constructing enormous volumes of residential and commercial buildings, and awareness of the energy savings and comfort benefits of insulation is growing alongside rising energy costs. Japan's very high construction quality standards and commitment to zero-energy housing by 2030 make it an important market for premium insulation products.
North America
North America is a large and technically sophisticated insulation market, with the U.S. supported by the Inflation Reduction Act's USD 4.3 billion in home energy efficiency rebates and tax credits that directly subsidize insulation upgrades. The U.S. Department of Energy's weatherization assistance program, which provides free insulation and energy efficiency improvements to low-income households, supported over 100,000 homes annually and represents consistent baseline demand. Canada's greener homes program has also provided significant grants for insulation upgrades.
Latin America
Latin America and the Middle East and Africa are earlier-stage markets where growing energy costs, rising urbanization, and the construction of new commercial and residential buildings are creating growing insulation demand, with the Gulf states' massive new urban development programs including NEOM in Saudi Arabia representing a significant procurement opportunity for specialized insulation systems.
Competitive landscape
- Saint-Gobain S.A. · France
- Owens Corning (U.S.)
- Kingspan Group plc · Ireland
- Rockwool International A/S · Denmark
- BASF SE · Germany
- Knauf Insulation · Germany
- Johns Manville/Berkshire Hathaway (U.S.)
- Covestro AG · Germany
- Huntsman Corporation (U.S.)
- GAF Materials Corporation (U.S.)
- Recticel Group · Belgium
- Armacell International S.A. · Luxembourg
- Fl
Frequently asked questions
The global building insulation systems market is expected to reach USD 112.8 billion by 2036 from an estimated USD 68.4 billion in 2026, at a CAGR of 5.1% during the forecast period 2026-2036. The market is underpinned by the fact that buildings account for approximately 36% of global energy consumption, making insulation improvement one of the most cost-effective and widely accessible energy efficiency interventions available globally.
Cite this report
Meticulous Research. (2026). Building Insulation Systems Market - Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MRSE - 1041945). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/building-insulation-systems-market-6628