Battery Energy Storage System Market (2026-2036)
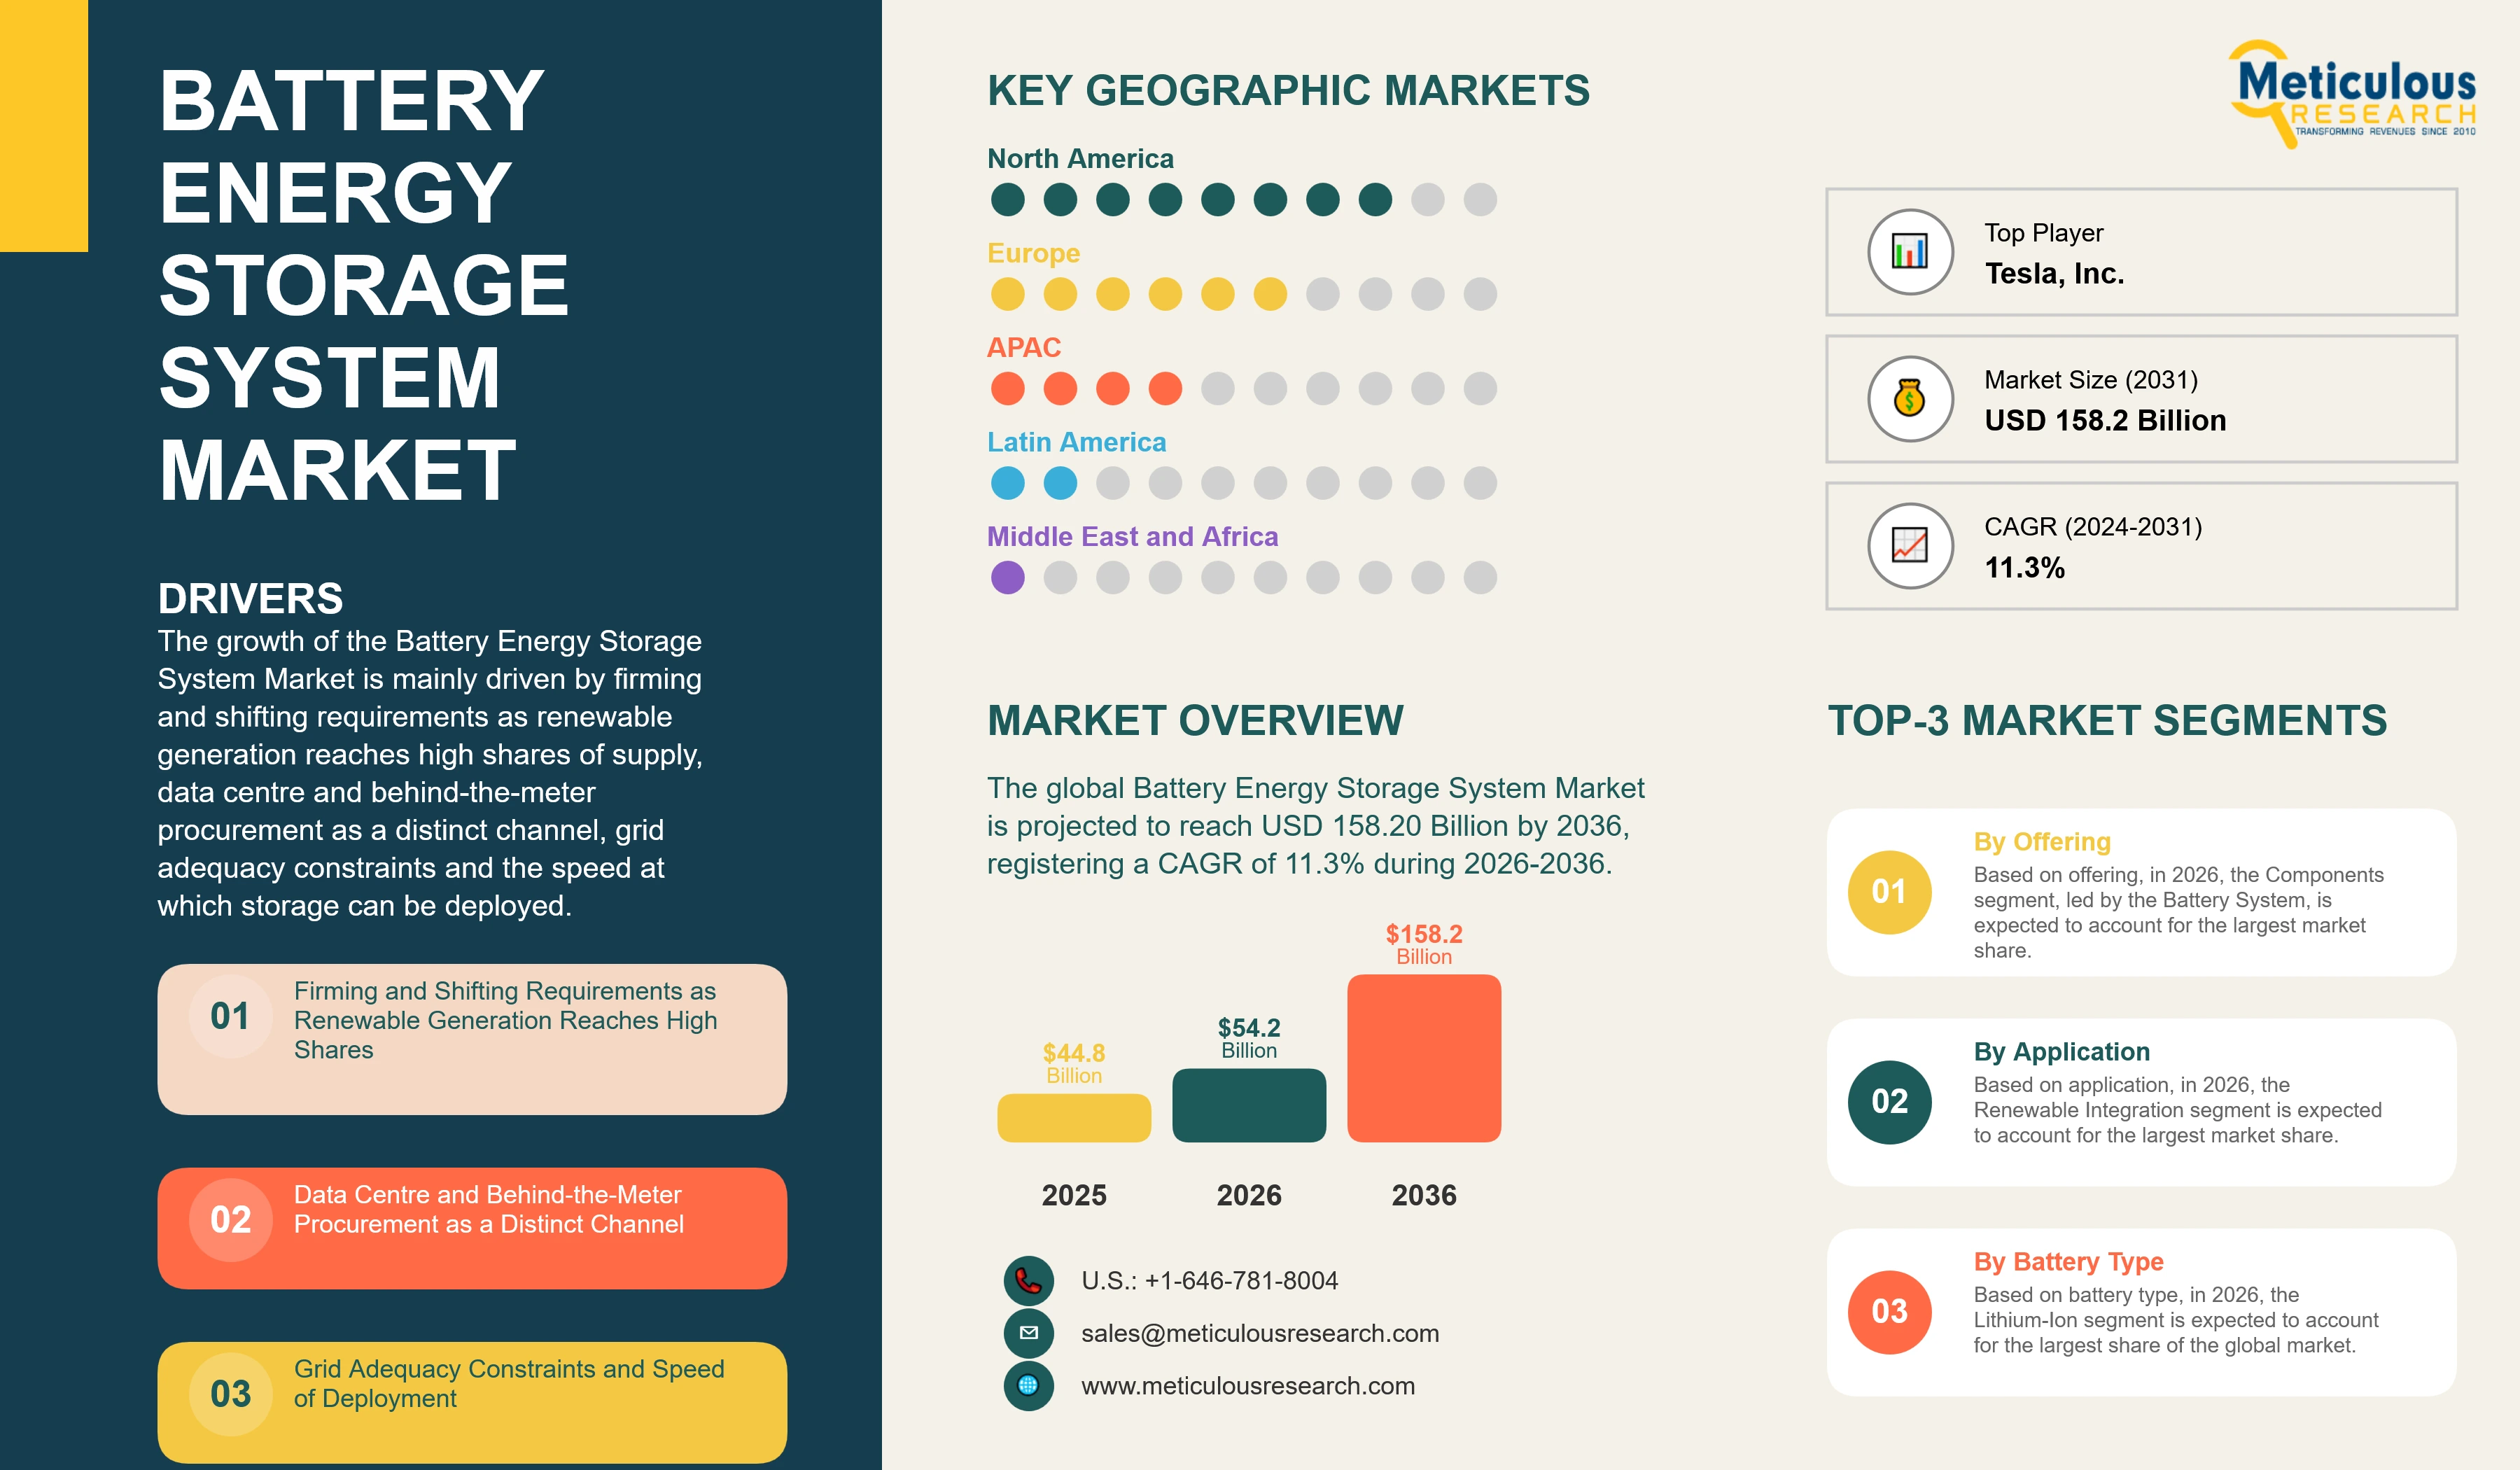
The global Battery Energy Storage System Market was valued at USD 44.80 billion in 2025. This market is expected to reach USD 158.20 billion by 2036 from an estimated USD 54.20 billion in 2026, registering a CAGR of 11.3% during the forecast period (2026-2036).
- Published
- Oct 2026
- Pages
- 294
- Format
- PDF + Excel
- Report ID
- MREP - 104650
- Base year
- 2025
- 2025 · BASELINE
- $44.80B
- 2036
- $158.2B
- CAGR 2026–2036
- 11.3%
2025 baseline · 2026–2036 forecast at 11.3% CAGR · hover a bar for the value
Key highlights
The global Battery Energy Storage System Market is projected to reach USD 158.20 billion by 2036, driven by renewable firming, data centre and behind-the-meter demand, grid adequacy requirements and continuing system cost decline.
Deployment volumes continue to set records. In the third quarter of 2026, ended 30 September 2026, Tesla, Inc. deployed 13.7 GWh of energy storage products, the second-highest quarterly deployment in company history.
Installed capacity is scaling rapidly. According to the U.S. Energy Information Administration, operators added 8.3 GW of battery storage capacity in the United States during the first half of 2026, bringing installed battery storage capacity to nearly 52 GW, and planned a further 14 GW of additions in the second half of the year.
Demand indicators are at record levels. In the third quarter of fiscal 2026, ended 30 June 2026, Fluence Energy, Inc. reported revenue of USD 649.8 million, up approximately 7.9%, with order intake of more than USD 1.44 billion against approximately USD 508.8 million a year earlier, a record backlog of approximately USD 6.4 billion, and an energy storage pipeline of 45.6 GW and 163.7 GWh, up 28% and 34% respectively.
A new demand channel has opened. Fluence Energy stated that it had secured approximately USD 850.0 million of data centre business through July 2026, including its first large behind-the-meter order, signed during the third quarter of fiscal 2026, and approximately USD 550.0 million of awards from a hyperscaler in July 2026.
Asia-Pacific is expected to account for the largest market share in 2026, supported by the scale of deployment and cell manufacturing in China, while North America is projected to register the fastest growth during the forecast period.
Report summary
| Particulars | Details |
|---|---|
| Forecast Period | 2026-2036 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| CAGR (Value) | 11.3% |
| Format | PDF, Excel & Cloud Portal · 294 pages |
| Market Size (Value) in 2026 | USD 54.20 Billion |
| Market Size (Value) in 2036 | USD 158.20 Billion |
| Segments Covered | By Battery Type: Lithium-Ion, Redox Flow Battery, Sodium-Sulfur, Nickel-Cadmium, Nickel-Metal Hydride, Other Battery Types. By Offering: Components (Battery System, Power Conversion System, Energy Management System, Battery Management System, Supervisory Control and Data Acquisition, Heating, Ventilation & Air Conditioning, Other Components), Services. By Connection Type: On-Grid, Off-Grid. By Ownership: Third-Party-Owned, Utility-Owned, Customer-Owned. By Energy Capacity: Below 100 MWh, 100 MWh to 500 MWh, More Than 500 MWh. By Application: Renewable Integration, Peak Shaving, Load Shifting, Grid Services, Microgrids, Utilities Black Start, Industries, Data Centers, EV Charging Infrastructure, Telecommunications, Marine, Healthcare. |
| Countries Covered | Asia-Pacific: China, Japan, India, South Korea, Australia, Rest of Asia-Pacific. North America: U.S., Canada. Europe: Germany, U.K., France, Italy, Spain, Rest of Europe. Latin America: Brazil, Chile, Mexico, Rest of Latin America. Middle East & Africa: Saudi Arabia, UAE, South Africa, Rest of Middle East & Africa. |
| Key Companies | Tesla, Inc., Contemporary Amperex Technology Co., Limited, BYD Company Limited, Sungrow Power Supply Co., Ltd., Fluence Energy, Inc., LG Energy Solution, Ltd., Samsung SDI Co., Ltd., EVE Energy Co., Ltd., Beijing HyperStrong Technology Co., Ltd., Envision Energy Co., Ltd., Trina Solar Co., Ltd., Canadian Solar Inc., JinkoSolar Holding Co., Ltd., Hitachi Energy Ltd., Delta Electronics, Inc., and NextEra Energy, Inc. |
Report overview
Segments covered: battery type, offering, connection type, ownership, energy capacity, application.
Deployment measured in gigawatt hours is expected to grow considerably faster than market value over the forecast period, because system prices per kilowatt hour continue to decline as cell manufacturing capacity expands and lithium iron phosphate chemistry displaces higher-cost alternatives. Value growth therefore reflects volume expansion net of price decline, and a forecast built on deployment volumes alone would substantially overstate the revenue available to suppliers.
The growth of this market is mainly driven by the requirement for firming and shifting capacity as variable renewable generation reaches high shares of supply; the emergence of data centre and behind-the-meter demand as a distinct procurement channel, including direct orders from hyperscale operators; the deterioration of grid adequacy and the resulting need for capacity that can be built faster than transmission or thermal generation; and the continuing decline in system cost, which has brought storage within economic reach of applications that could not previously support it. In addition, capacity market and ancillary service revenue stacking, interconnection queue reform favouring co-located and hybrid projects, mandates and procurement targets in several large markets, and the extension of storage into industrial, electric vehicle charging and telecommunications applications are further supporting the growth of this market.
The Battery Energy Storage System Market, also referred to as the BESS market, grid-scale battery storage market or electrochemical energy storage system market, comprises the complete systems that store electrical energy in batteries and return it to a grid, a facility or a microgrid. A system comprises the battery modules and racks, the power conversion system that converts between direct and alternating current, the battery management system, the energy management system, supervisory control and data acquisition, thermal management through heating, ventilation and air conditioning, enclosures, fire detection and suppression, and the engineering, installation, commissioning, operations, maintenance and warranty services supplied with them. The market ecosystem extends from cell and component manufacturers through system integrators, engineering and construction contractors and software providers to utilities, independent power producers, grid operators, commercial and industrial consumers, data centre operators and the regulators whose market rules and procurement determine where storage is deployed.
The market has passed from a stage in which deployment depended on subsidy and mandate to one in which it is driven by system need. Storage is now built because variable renewable generation cannot be firmed without it, because capacity is required faster than transmission or thermal plant can be delivered, and because the arbitrage and ancillary service revenue available in several markets supports a project on its own economics. The result is a volume of deployment that would have appeared implausible when the previous generation of forecasts was prepared.
The scale is evident in deployment by individual suppliers. In the third quarter of 2026, ended 30 September 2026, Tesla, Inc. deployed 13.7 GWh of energy storage products, the second-highest quarterly deployment in company history. Quarterly deployment at this level from a single supplier indicates both the maturity of manufacturing and the depth of demand, and it is a volume comparable to the annual output of the entire industry only a few years earlier.
Installed capacity data confirm the pace at national level. According to the U.S. Energy Information Administration, operators added 8.3 GW of battery storage capacity in the United States during the first half of 2026, bringing installed battery storage capacity to nearly 52 GW, and planned a further 14 GW of additions in the second half of the year. Additions of 8.3 GW in six months against a cumulative installed base of nearly 52 GW indicate that a substantial proportion of all capacity in operation has been built very recently, with the implication that operating experience, degradation data and warranty exposure across the fleet remain comparatively shallow.
Demand indicators across the supply base are at record levels. In the third quarter of fiscal 2026, ended 30 June 2026, Fluence Energy, Inc. reported revenue of USD 649.8 million, up approximately 7.9%, with order intake of more than USD 1.44 billion against approximately USD 508.8 million a year earlier, a record backlog of approximately USD 6.4 billion, and an energy storage pipeline of 45.6 GW and 163.7 GWh, up 28% and 34% respectively. Order intake nearly tripling year over year and a pipeline rising 34% in gigawatt hours terms indicate that the constraint on growth lies in delivery rather than in demand.
That constraint is real and is the most important correction to the prevailing view of this market. Fluence Energy reported third-quarter fiscal 2026 GAAP gross profit of USD 33.2 million, a margin of 5.1% against 14.8% a year earlier, an adjusted EBITDA loss of USD 29.3 million, and revised full-year fiscal 2026 revenue guidance to USD 2.9 billion to USD 3.1 billion from USD 3.2 billion to USD 3.6 billion, citing construction-related delays affecting the start-up of a new United States contract manufacturing facility and approximately USD 400.0 million of project deliveries expected to move into fiscal 2027. A gross margin falling from 14.8% to 5.1% while backlog reaches a record demonstrates that record demand and profitable delivery are different matters, and that supply chain localisation, contract manufacturing ramp and project execution are now the binding issues for integrators rather than order capture.
A new demand channel has opened that did not exist when the previous edition of this analysis was prepared. Fluence Energy stated that it had secured approximately USD 850.0 million of data centre business through July 2026, including its first large behind-the-meter order, signed during the third quarter of fiscal 2026, and approximately USD 550.0 million of awards from a hyperscaler in July 2026. Data centre operators require capacity faster than grid interconnection can provide it and are willing to contract storage behind the meter to bridge the gap, to firm on-site generation and to manage demand charges, and because these buyers procure on construction timelines rather than regulatory ones, the channel converts to revenue quickly.
Technology within the market is consolidating rather than diversifying. Lithium iron phosphate has displaced nickel-based lithium chemistries in stationary applications on cost, cycle life and thermal stability, and the practical competition is now between lithium iron phosphate and a small set of alternatives addressing requirements it does not serve, principally durations beyond four to eight hours, where redox flow chemistries are being deployed, and cost-sensitive applications where sodium-ion cells are entering the market. Sodium-sulfur, nickel-cadmium and nickel-metal hydride systems retain only legacy and niche positions.
The market includes cell manufacturers that have integrated forward into systems, system integrators, and inverter and power electronics manufacturers that have integrated into complete offerings, among them Tesla, CATL, BYD, Sungrow, Fluence Energy, LG Energy Solution, Samsung SDI, EVE Energy, HyperStrong, Envision Energy, Trina Solar, Canadian Solar, JinkoSolar, Hitachi Energy, Delta Electronics and NextEra Energy. Participants compete on delivered cost per kilowatt hour, round-trip efficiency and degradation guarantees, warranty terms and the balance sheet behind them, safety record and fire protection design, controls and energy management capability, delivery certainty against contracted dates, and domestic content where procurement rules or tariffs reward it.
At the same time, the market faces challenges, including the execution and margin pressure visible across the integrator base, concentration of cell supply in a small number of countries and the trade measures responding to it, interconnection queue delays that defer revenue regardless of equipment availability, safety and permitting constraints following high-profile thermal events, degradation and warranty exposure across a fleet with limited operating history, and the dependence of project economics on market rules that regulators can revise. As a result, suppliers that combine competitive delivered cost, demonstrated delivery certainty, credible warranty backing, strong safety engineering and diversified supply are expected to capture the largest share of growth over the forecast period.
Report infographic
Market dynamics
15 factors across 5 forcesFirming and Shifting Requirements as Renewable Generation Reaches High Shares
The requirement for firming and shifting capacity as variable renewable generation reaches high shares of supply is a major factor driving the Battery Energy Storage System Market. Solar generation peaks hours before system demand peaks and wind generation does not follow demand at all, so beyond a certain penetration a system cannot absorb further renewable capacity without storage to move energy in time, and curtailment of otherwise economic generation becomes the alternative to building it.
The resulting build is visible in national capacity data. According to the U.S. Energy Information Administration, operators added 8.3 GW of battery storage capacity in the United States during the first half of 2026, bringing installed battery storage capacity to nearly 52 GW, and planned a further 14 GW of additions in the second half of the year. Additions at that rate indicate that storage is being procured as a system requirement rather than as an incremental resource, and because it can be permitted and constructed faster than transmission or thermal generation, it is frequently the only capacity that can be delivered within the timeframe the system operator requires.
Data Centre and Behind-the-Meter Procurement as a Distinct Channel
Data centre and behind-the-meter procurement is significantly driving market growth and represents the most important new source of demand in this market. Fluence Energy stated that it had secured approximately USD 850.0 million of data centre business through July 2026, including its first large behind-the-meter order, signed during the third quarter of fiscal 2026, and approximately USD 550.0 million of awards from a hyperscaler in July 2026. Data centre developers face interconnection timelines far longer than their construction schedules, and storage deployed behind the meter allows a facility to energise ahead of full grid capacity, to firm on-site generation and to manage demand charges and power quality.
The commercial character of this channel differs from utility procurement in ways that favour suppliers. These buyers contract on construction timelines rather than regulatory ones, they are less price-sensitive than utilities because the alternative is a delayed facility, and they value delivery certainty above all, which rewards suppliers able to commit to dates. Awards of approximately USD 550.0 million from a single hyperscale operator in one month indicate the order sizes now available in this channel.
Grid Adequacy Constraints and Speed of Deployment
Grid adequacy constraints and the speed at which storage can be deployed is an important driver of demand. Load growth from electrification and from computing infrastructure is arriving faster than transmission can be built or thermal generation permitted, and system operators facing reserve margin deterioration require capacity that can be delivered in quarters rather than years. A battery storage project can be permitted, delivered and commissioned within such a timeframe, which makes it the resource of choice for near-term adequacy.
Procurement volumes reflect that urgency. In the third quarter of fiscal 2026, ended 30 June 2026, Fluence Energy, Inc. reported revenue of USD 649.8 million, up approximately 7.9%, with order intake of more than USD 1.44 billion against approximately USD 508.8 million a year earlier, a record backlog of approximately USD 6.4 billion, and an energy storage pipeline of 45.6 GW and 163.7 GWh, up 28% and 34% respectively. Order intake rising from approximately USD 508.8 million to more than USD 1.44 billion in a single quarter year over year, with a pipeline of 163.7 GWh, indicates buyers contracting ahead of need rather than tendering competitively at the last moment, which is characteristic of a market where delivery capacity rather than price is the scarce commodity.
Continuing Decline in System Cost
The continuing decline in system cost supports market growth by extending storage into applications that could not previously support it. Expansion of cell manufacturing capacity, the displacement of nickel-based chemistries by lithium iron phosphate and improvements in energy density at the pack and container level have reduced delivered cost per kilowatt hour substantially, and each reduction brings further applications within economic reach, including longer durations, industrial load management and electric vehicle charging support.
The same decline moderates the value forecast for this market. Because price per kilowatt hour continues to fall, deployment measured in gigawatt hours is expected to grow considerably faster than market value, and the growth in value available to suppliers is volume expansion net of price decline, which is why a forecast anchored on deployment volumes alone overstates the revenue opportunity.
Table of contents
14 chapters · 168 sections · 294 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Battery Type | Other Battery Types include sodium-ion and | Other Battery Types |
| By Offering | Components | Services |
| By Connection Type | On-Grid | — |
| By Ownership | Third-Party-Owned | Customer-Owned |
| By Energy Capacity | 100 MWh to 500 MWh | More Than 500 MWh |
| By Application | Renewable Integration | Data Centers |
By Battery Type
- Battery Energy Storage System Market Analysis by Battery Type
- Other Battery Types include sodium-ion and lead-acid systems.
- The Lithium-Ion segment is expected to account for the largest share of the global Battery Energy Storage System Market.
- The large share of this segment is mainly due to the displacement of competing chemistries by lithium iron phosphate on delivered cost, cycle life and thermal stability, the scale of manufacturing capacity dedicated to stationary storage cells, and the concentration of utility-scale and behind-the-meter procurement on four-hour and shorter durations, where lithium iron phosphate is the most economic option available.
- However, the Other Battery Types segment is projected to register the highest CAGR during the forecast period.
- The rapid growth of this segment is attributed to the commercialisation of sodium-ion cells, which avoid lithium and cobalt entirely and offer favourable low-temperature performance for cost-sensitive applications, from a base small enough that early deployment produces high growth rates.
- The Redox Flow Battery segment is also expected to grow strongly, supported by durations beyond four to eight hours, where the ability to size energy and power independently gives it an economic advantage, while Sodium-Sulfur, Nickel-Cadmium and Nickel-Metal Hydride segments are expected to remain confined to legacy installations and specialised applications.
By Offering
- Battery Energy Storage System Market Analysis by Offering
- Components are further segmented into Battery System, Power Conversion System, Energy Management System, Battery Management System, Supervisory Control and Data Acquisition, Heating, Ventilation & Air Conditioning, and Other Components.
- The Components segment is expected to account for the largest share of the market, and within it the Battery System sub-segment is expected to account for the largest share.
- The large share of these segments is mainly due to the proportion of total system cost represented by cells, modules and racks, which exceeds all other elements combined, and to the delivery of storage predominantly as complete equipment packages in which the battery system is the principal line item.
- However, the Services segment is projected to register the highest CAGR during the forecast period.
- The rapid growth of this segment is attributed to the expansion of the operating fleet, which creates demand for long-term service agreements, availability and performance guarantees, augmentation and dispatch optimisation over asset lives extending two decades, and to the lower exposure of service revenue to the equipment price deflation that constrains hardware value growth.
- One leading integrator reported a services backlog of 7.9 GW alongside its equipment backlog.
By Connection Type
- Battery Energy Storage System Market Analysis by Connection Type
- The On-Grid segment is expected to account for the largest share of the global Battery Energy Storage System Market and is also projected to register the higher growth rate during the forecast period.
- The large share and faster growth of this segment are mainly due to the concentration of deployment in utility-scale projects providing renewable firming, capacity and ancillary services to transmission and distribution systems, the scale of national capacity additions, with 8.3 GW added in the United States in the first half of 2026 alone, and the extension of grid-connected deployment into behind-the-meter installations at large loads, which remain connected to the network.
- The Off-Grid segment is expected to grow steadily, supported by microgrids serving remote communities, mining and industrial sites, telecommunications infrastructure beyond network reach, and island systems displacing diesel generation, where storage economics benefit from the high cost of the fuel it replaces.
By Ownership
- Battery Energy Storage System Market Analysis by Ownership
- The Third-Party-Owned segment is expected to account for the largest share of the market.
- The large share of this segment is mainly due to the development of utility-scale storage predominantly by independent power producers and developers contracting capacity or tolling agreements to offtakers, the availability of project finance structures suited to that model, and the preference of many utilities to contract for capacity rather than own it.
- However, the Customer-Owned segment is projected to register the highest CAGR during the forecast period.
- The rapid growth of this segment is attributed to behind-the-meter procurement by data centre operators and large industrial consumers, evidenced by approximately USD 850.0 million of data centre business secured by a single integrator through July 2026 including a first large behind-the-meter order, and by the value these buyers place on controlling an asset that determines whether their facility can energise on schedule.
- The Utility-Owned segment is expected to grow steadily, concentrated in jurisdictions where regulated rate base treatment is available for storage.
By Energy Capacity
- Battery Energy Storage System Market Analysis by Energy Capacity
- The 100 MWh to 500 MWh segment is expected to account for the largest share of the market.
- The large share of this segment is mainly due to the typical sizing of utility-scale projects at this scale, which balances interconnection capacity, land availability and offtake requirements, and to the suitability of this range for co-location with solar generation at a comparable scale.
- However, the More Than 500 MWh segment is projected to register the highest CAGR during the forecast period.
- The rapid growth of this segment is attributed to the scaling of individual projects as developers concentrate capacity at points of interconnection to amortise connection cost, the rise in energy per container, which allows larger projects on the same land area, and procurement by data centre and large industrial buyers whose facility loads require capacity at this scale.
- The Below 100 MWh segment is expected to grow steadily, supported by commercial and industrial, microgrid and distribution-level deployment.
By Application
- Battery Energy Storage System Market Analysis by Application
- The Renewable Integration segment is expected to account for the largest share of the global Battery Energy Storage System Market.
- The large share of this segment is mainly due to the inability of systems to absorb further variable generation without storage to shift energy in time, the co-location of storage with solar and wind projects as standard practice in new development, and the volume of capacity procured specifically to reduce curtailment and firm renewable output.
- However, the Data Centers segment is projected to register the highest CAGR during the forecast period.
- The rapid growth of this segment is attributed to interconnection timelines far longer than data centre construction schedules, which creates demand for behind-the-meter storage allowing a facility to energise ahead of full grid capacity, to the firming of on-site generation and management of demand charges and power quality, and to order sizes including approximately USD 550.0 million of awards from a single hyperscale operator in July 2026.
- Grid Services, Peak Shaving and Load Shifting are expected to remain substantial applications, while EV Charging Infrastructure is expected to grow strongly as charging sites use storage to avoid connection upgrades.
Geographic analysis
Asia-Pacific
Largest shareIn 2026, Asia-Pacific is expected to account for the largest share of the global Battery Energy Storage System Market. The large share of this region is mainly attributed to the scale of deployment in China, where storage is procured alongside very large additions of solar and wind capacity and supported by provincial allocation and market reform, the concentration of lithium iron phosphate cell manufacturing capacity in the region, and the presence of leading suppliers including CATL, BYD, Sungrow, EVE Energy, HyperStrong, Envision Energy, Trina Solar, JinkoSolar, LG Energy Solution, Samsung SDI and Delta Electronics. Deployment in Japan, South Korea, India and Australia adds materially to regional volume.
North America
Fastest growthNorth America is projected to register the highest CAGR during the forecast period. The growth of this region is driven by renewable firming requirements in markets with high solar penetration, reserve margin deterioration arising from load growth, the emergence of data centre and behind-the-meter procurement as a distinct channel, and procurement preferences rewarding domestically manufactured content. According to the U.S. Energy Information Administration, operators added 8.3 GW of battery storage capacity in the United States during the first half of 2026, bringing installed battery storage capacity to nearly 52 GW, and planned a further 14 GW of additions in the second half of the year. The presence of Tesla, Fluence Energy, NextEra Energy and Canadian Solar supports regional supply, although integrators have encountered material difficulty commissioning new domestic manufacturing capacity.
Europe
Europe is expected to account for a significant share of the market, supported by high renewable penetration across several national systems, capacity market and ancillary service arrangements in Great Britain, Italy, Germany and Spain, grid congestion creating value for storage at constrained nodes, and the presence of Hitachi Energy and Siemens Energy among suppliers to the region. Deployment has been slower than the resource case would suggest in several markets because connection processes and planning consent rather than project economics have governed delivery.
Latin America
Latin America and the Middle East & Africa are expected to account for smaller shares of the market while growing from low bases. In Latin America, Chile and Brazil are deploying storage alongside solar generation in systems with pronounced curtailment, while in the Middle East, very large solar and storage procurements in Saudi Arabia and the United Arab Emirates are establishing the region as a significant source of demand, and in Africa storage is being deployed in microgrid and grid-support applications where supply reliability is the principal driver.
Competitive landscape
The global Battery Energy Storage System Market is moderately consolidated, with vertically integrated cell manufacturers holding large positions supported by cost and capacity, system integrators competing on controls, services and delivery capability, and power electronics manufacturers participating through complete offerings built around their inverters. Market participants compete on delivered cost per kilowatt hour, round-trip efficiency and degradation guarantees, warranty terms and the balance sheet behind them, safety record and fire protection design, controls and energy management capability, delivery certainty against contracted dates, and domestic content where procurement rules or tariffs reward it.
Leading companies are securing long-term cell supply or investing in their own capacity, establishing manufacturing in markets where content rules reward it, raising energy per container to reduce balance of system and installation cost, developing long-duration and sodium-ion offerings for requirements lithium iron phosphate serves poorly, building service and optimisation businesses around the installed fleet, and pursuing data centre and behind-the-meter customers directly. Recent market context includes quarterly deployment of 13.7 GWh at Tesla in the third quarter of 2026, record backlog of approximately USD 6.4 billion with order intake of more than USD 1.44 billion at Fluence Energy in the third quarter of fiscal 2026 alongside gross margin compression from 14.8% to 5.1%, and approximately USD 850.0 million of data centre business secured by that integrator through July 2026.
The report provides a comprehensive competitive assessment of the leading companies operating in the global Battery Energy Storage System Market. The key players profiled in the report include Tesla, Inc. (U.S.), Contemporary Amperex Technology Co., Limited (China), BYD Company Limited (China), Sungrow Power Supply Co., Ltd. (China), Fluence Energy, Inc. (U.S.), LG Energy Solution, Ltd. (South Korea), Samsung SDI Co., Ltd. (South Korea), EVE Energy Co., Ltd. (China), Beijing HyperStrong Technology Co., Ltd. (China), Envision Energy Co., Ltd. (China), Trina Solar Co., Ltd. (China), Canadian Solar Inc. (Canada), JinkoSolar Holding Co., Ltd. (China), Hitachi Energy Ltd. (Switzerland), Delta Electronics, Inc. (Taiwan), and NextEra Energy, Inc. (U.S.).
- Tesla, Inc.
- Contemporary Amperex Technology Co., Limited
- BYD Company Limited
- Sungrow Power Supply Co., Ltd.
- Fluence Energy, Inc.
- LG Energy Solution, Ltd.
- Samsung SDI Co., Ltd.
- EVE Energy Co., Ltd.
- Beijing HyperStrong Technology Co., Ltd.
- Envision Energy Co., Ltd.
- Trina Solar Co., Ltd.
- Canadian Solar Inc.
- JinkoSolar Holding Co., Ltd.
- Hitachi Energy Ltd.
- Delta Electronics, Inc.
- NextEra Energy, Inc
Expert perspectives
The Battery Energy Storage System Market has reached the point at which demand is no longer the question. Quarterly deployment of 13.7 GWh at a single supplier, 8.3 GW of United States additions in half a year, and order intake nearly tripling year over year at a leading integrator all point the same way. What the same results show, and what a demand-led reading of this market misses, is that record demand is not translating into profitable delivery: gross margin at that integrator fell from 14.8% to 5.1%, adjusted EBITDA turned negative and full-year guidance was cut while backlog reached a record. The binding constraint is shifting from procurement to execution, because cells, contract manufacturing, construction labour, interconnection and commissioning all now govern when revenue is recognised, and none of them are solved by winning another order.
Three structural changes are expected to shape competitive positions through 2036. First, value growth is expected to run well below volume growth, because system prices per kilowatt hour continue to fall, so suppliers must either integrate upstream to capture cell margin or build service and software revenue that does not deflate with hardware. Second, data centre and behind-the-meter procurement is expected to become a major channel in its own right, contracting on construction rather than regulatory timelines and paying for delivery certainty. Third, trade measures and content requirements are expected to continue fragmenting a market whose cell supply is geographically concentrated, which rewards local qualified capacity and penalises those who cannot establish it.
For companies planning entry or expansion, the most defensible positions over the forecast period are likely to be found in behind-the-meter storage for data centres and large industrial loads, long-duration capacity beyond the four-hour standard, services, software and fleet optimisation over twenty-year asset lives, content-advantaged domestic supply, and safety and fire engineering as permitting requirements tighten. For established suppliers, the principal priorities are restoring margin through supply security and delivery discipline rather than volume, securing cell supply on terms that survive tariff change, and building the service revenue that will outlast equipment price deflation.
Overall, the market is expected to grow strongly, with lithium-ion batteries, components and battery systems, on-grid connection, third-party ownership, the 100 MWh to 500 MWh range, renewable integration applications and Asia-Pacific providing the core of demand, and other battery types including sodium-ion, services, customer ownership, projects above 500 MWh, data centre applications and North America providing the fastest growth.
Customer perspectives
Insights gathered during primary interviews with utility resource planners, independent power producer development leads, and data centre energy managers highlight where priorities are shifting. The following perspectives reflect recurring themes raised across these discussions.
“This reflects speed of deployment rather than cost as the deciding factor.”
“This indicates delivery certainty displacing price in procurement.”
“This points to interconnection timing as the driver of behind-the-meter demand.”
Frequently asked questions
The global Battery Energy Storage System Market is estimated at USD 54.20 billion in 2026.
Cite this report
Meticulous Research. (2026). Battery Energy Storage System Market - Global Opportunity Analysis And Industry Forecast (2026-2036) (Report No. MREP - 104650). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/battery-energy-storage-system-market-5336