Advanced Bioreactor Systems Market (2026-2036)
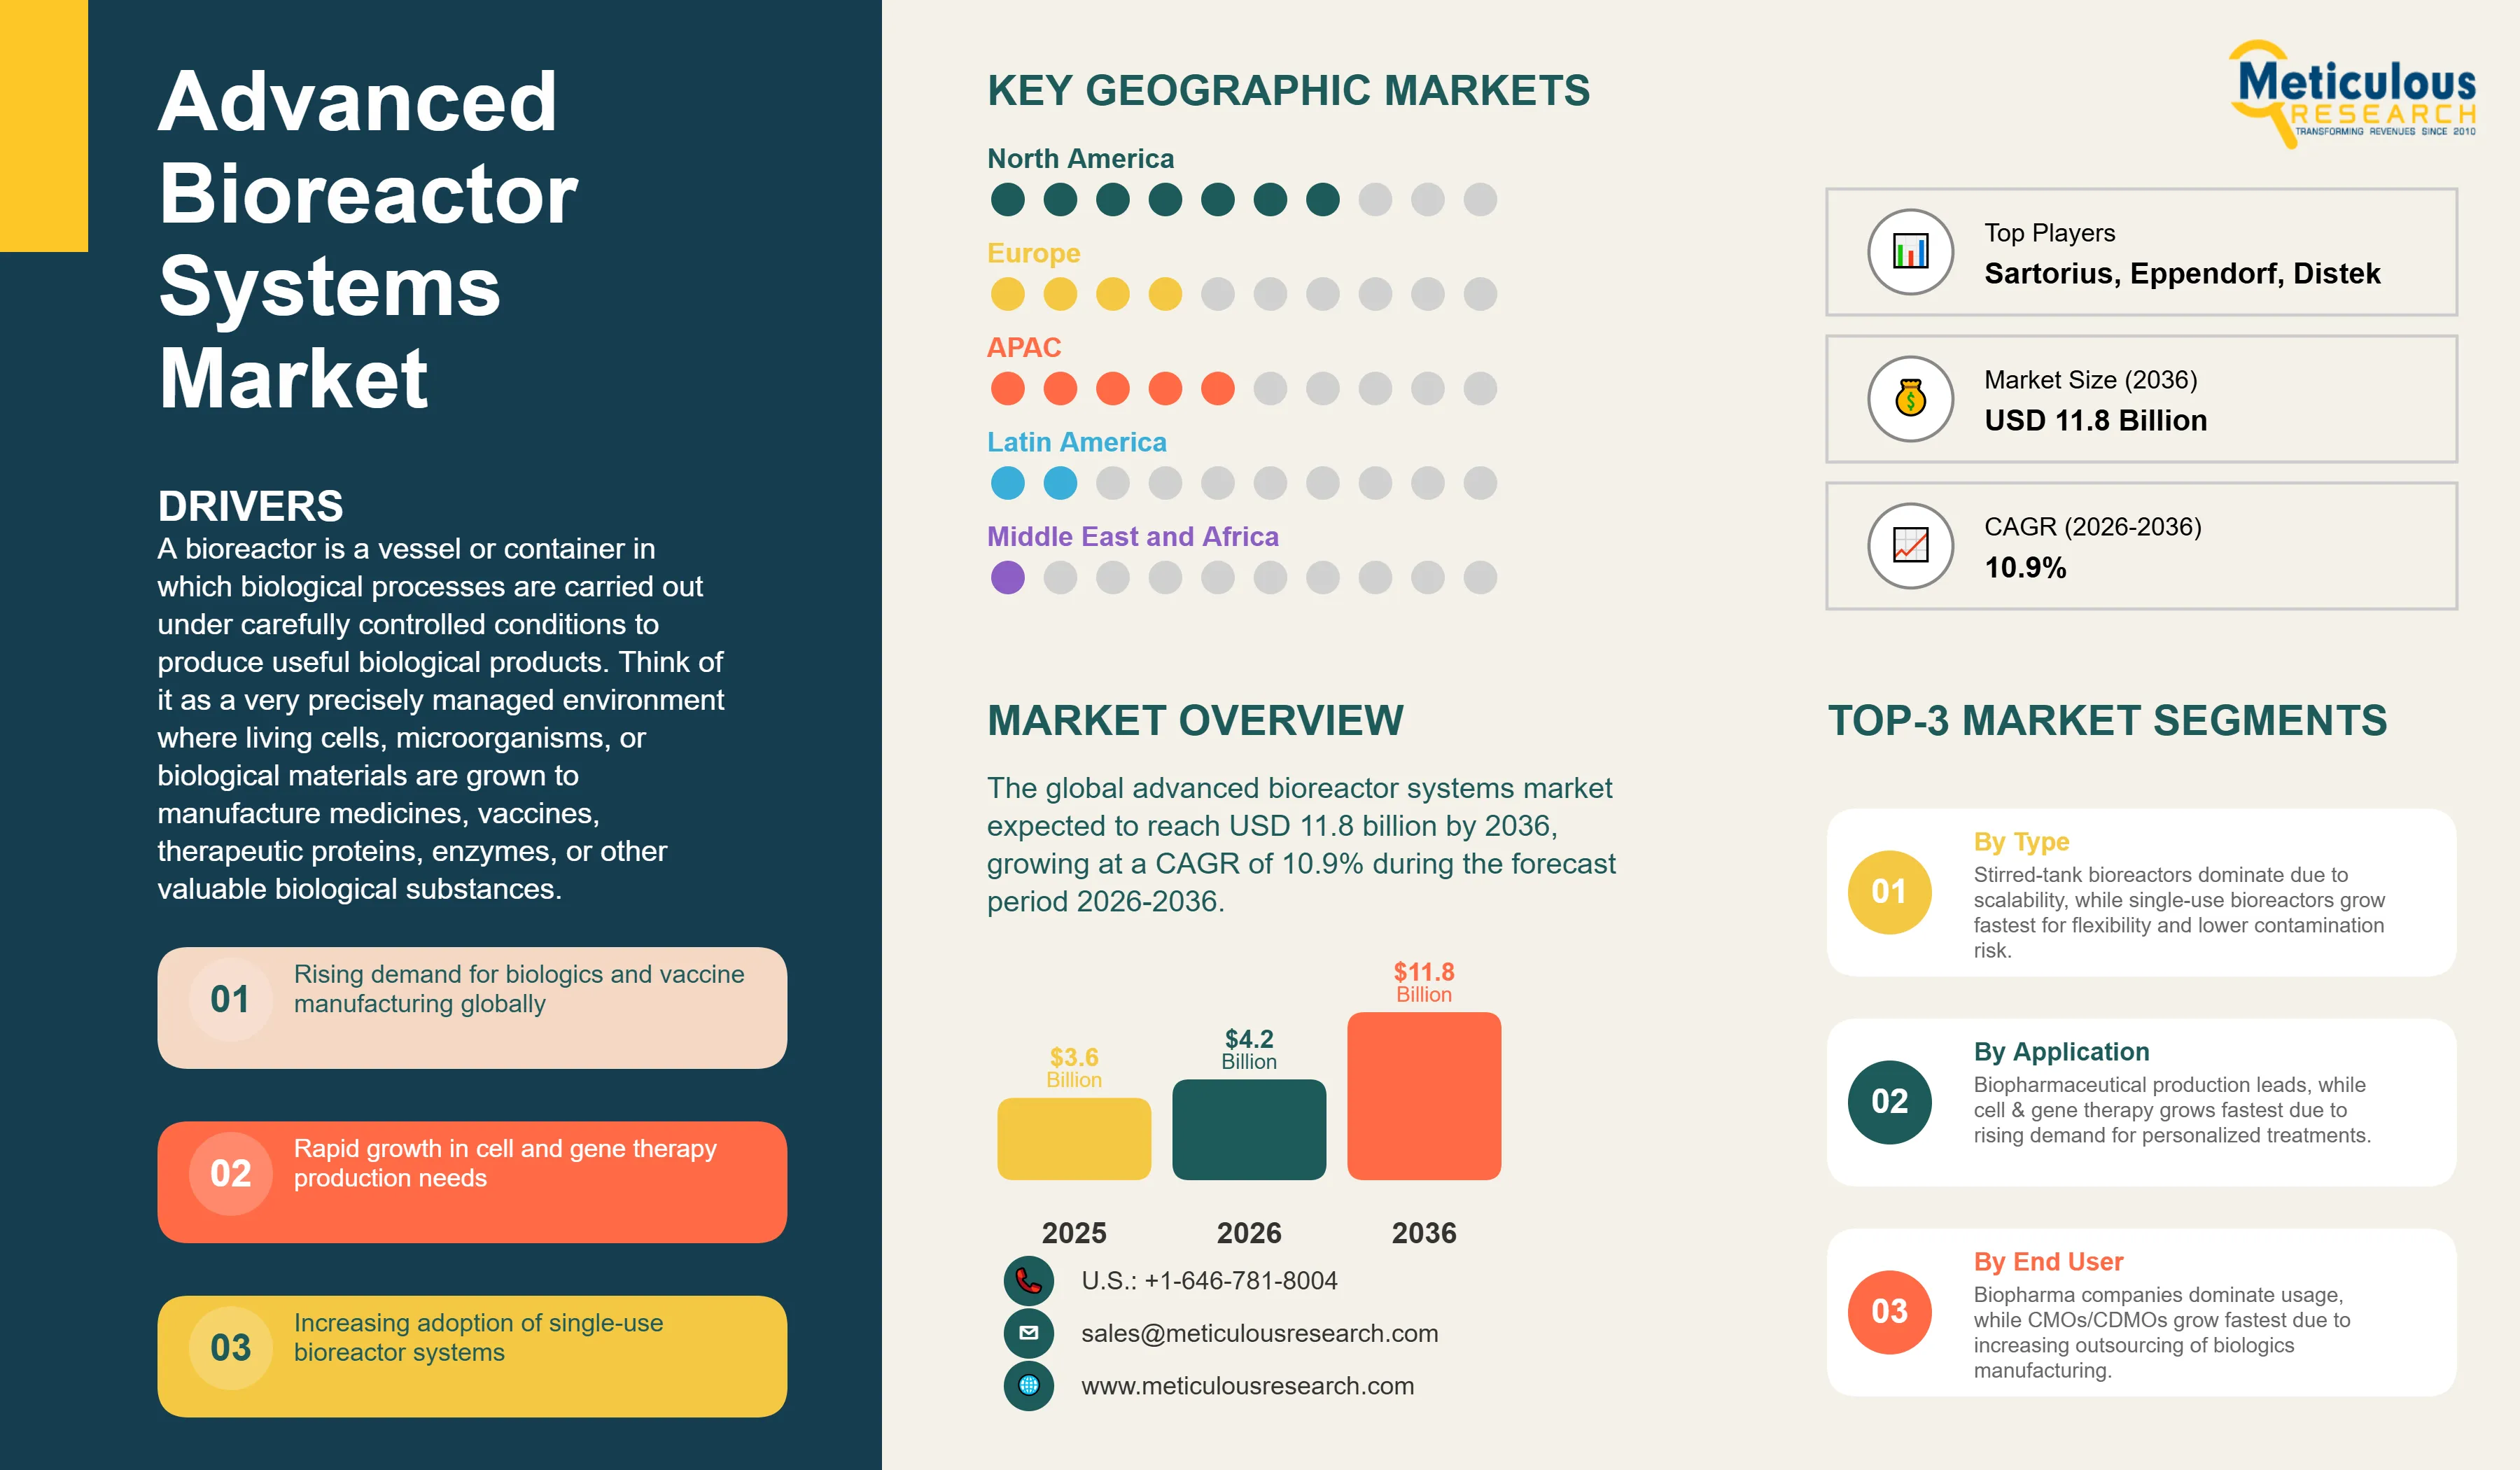
The global advanced bioreactor systems market was valued at USD 3.6 billion in 2025. This market is expected to reach USD 11.8 billion by 2036 from an estimated USD 4.2 billion in 2026, growing at a CAGR of 10.9% during the forecast period 2026-2036.
- Published
- Apr 2026
- Pages
- 312
- Format
- PDF + Excel
- Report ID
- MRHC - 1041929
- Base year
- 2025
- 2025 · BASELINE
- $3.60B
- 2036
- $11.80B
- CAGR 2026–2036
- 10.9%
2025 baseline · 2026–2036 forecast at 10.9% CAGR · hover a bar for the value
Key highlights
The global advanced bioreactor systems market is projected to reach USD 11.8 billion by 2036.
The market is expected to grow at a CAGR of 10.9% during the forecast period 2026-2036.
The global market was valued at USD 3.6 billion in 2025 and is estimated to reach USD 4.2 billion in 2026.
North America is expected to dominate the global advanced bioreactors market with the largest market share in 2026, while Asia-Pacific is projected to register the highest CAGR during the forecast period.
By bioreactor type, the stirred-tank bioreactors segment is expected to hold the largest share of the market in 2026, while the single-use bioreactors segment is projected to register the highest CAGR during the forecast period.
By scale, the commercial-scale bioreactors segment is expected to hold the largest share in 2026, while the pilot-scale bioreactors segment is projected to register the highest CAGR during the forecast period.
By application, the biopharmaceutical production segment is expected to hold the largest share in 2026, while the cell and gene therapy segment is projected to register the highest CAGR during the forecast period.
By end user, the biopharmaceutical companies segment is expected to hold the largest share in 2026, while the contract manufacturing organizations segment is projected to register the highest CAGR during the forecast period.
By mode of operation, the fed-batch processing segment is expected to hold the largest share in 2026, while the continuous processing segment is projected to register the highest CAGR during the forecast period.
By control type, the automated systems segment is expected to hold the largest share in 2026, while the AI-driven smart bioreactors segment is projected to register the highest CAGR during the forecast period.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 11.8 Billion |
| Market Size in 2026 | USD 4.2 Billion |
| Market Size in 2025 | USD 3.6 Billion |
| Revenue Growth Rate (2026-2036) | CAGR of 10.9% |
| Format | PDF, Excel & Cloud Portal · 312 pages |
| Dominating Bioreactor Type | Stirred-Tank Bioreactors |
| Fastest Growing Bioreactor Type | Single-Use (Disposable) Bioreactors |
| Dominating Scale | Commercial-Scale Bioreactors |
| Fastest Growing Scale | Pilot-Scale Bioreactors |
| Dominating Application | Biopharmaceutical Production |
| Fastest Growing Application | Cell and Gene Therapy |
| Dominating End User | Biopharmaceutical Companies |
| Fastest Growing End User | Contract Manufacturing Organizations (CMOs/CDMOs) |
| Dominating Mode of Operation | Fed-Batch Processing |
| Fastest Growing Mode of Operation | Continuous Processing (Perfusion) |
| Dominating Control Type | Automated Systems |
| Fastest Growing Control Type | AI-Driven Smart Bioreactors |
| Dominating Geography | North America |
| Fastest Growing Geography | Asia-Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
Report overview
Segments covered: bioreactor type, scale, application, end user, mode of operation, control type.
A bioreactor is a vessel or container in which biological processes are carried out under carefully controlled conditions to produce useful biological products. Think of it as a very precisely managed environment where living cells, microorganisms, or biological materials are grown to manufacture medicines, vaccines, therapeutic proteins, enzymes, or other valuable biological substances. Advanced bioreactor systems go beyond simple fermentation tanks to include sophisticated monitoring, control, and automation capabilities that allow manufacturers to maintain the exact conditions of temperature, oxygen level, pH, and nutrient supply that biological production processes require. The output of these systems can be a monoclonal antibody used to treat cancer, a vaccine antigen, a therapeutic protein for a rare disease, or a living cell therapy product manufactured for a specific patient.
The market is growing strongly because the pharmaceutical industry has fundamentally shifted toward biological medicines over the past two decades. Monoclonal antibodies, the treatment of choice for many cancers, autoimmune diseases, and inflammatory conditions, are manufactured almost entirely using bioreactor-based cell culture processes. The global market for monoclonal antibody drugs alone exceeds USD 200 billion annually and is growing rapidly, driving proportional demand for the bioreactor systems used to produce them. The COVID-19 pandemic demonstrated the critical importance of large-scale bioreactor capacity by revealing that messenger RNA vaccine manufacturing required very rapid scale-up of bioprocessing infrastructure, and this experience has driven governments and pharmaceutical companies globally to invest in expanding domestic biomanufacturing capacity in a way that is sustaining growth well beyond the pandemic period.
Two particularly significant opportunities are driving additional market growth beyond the established monoclonal antibody and vaccine applications. The emerging cell and gene therapy sector, which includes CAR-T cell therapies that reprogram a patient's own immune cells to fight cancer and viral vector gene therapy products that deliver corrective genetic material to treat previously untreatable inherited diseases, requires bioreactor systems specifically designed for the very small batch sizes and specialized cell culture conditions of these personalized therapies. This is a fast-growing and high-value application that is creating demand for new types of small-scale, highly controlled bioreactor systems. In addition, the transition from batch and fed-batch bioprocessing to continuous bioprocessing, where cells are kept growing and producing product continuously rather than in discrete batches, has the potential to dramatically reduce manufacturing costs and increase productivity, creating strong demand for perfusion bioreactors and the integrated process control platforms that continuous manufacturing requires.
Report infographic
Market dynamics
7 factors across 3 forcesIncreasing Demand for Biopharmaceuticals and Vaccines
The primary driver of the advanced bioreactor equipment market is the sustained and rapid growth of the global biopharmaceuticals market, which has become the largest and fastest-growing segment of the pharmaceutical industry over the past two decades. Monoclonal antibodies, which are manufactured using bioreactor-based mammalian cell culture processes, generated over USD 200 billion in global sales and represent the majority of the world's top-selling drugs, including blockbuster cancer treatments, autoimmune disease therapies, and inflammatory condition treatments that each individually generate billions of dollars in annual revenue. Every gram of monoclonal antibody product requires dedicated bioreactor capacity to manufacture, and the continued growth of the global monoclonal antibody market at double-digit annual rates creates proportional demand growth for the bioreactor systems used to produce them. The global COVID-19 vaccination campaign also demonstrated that rapid large-scale vaccine manufacturing requires substantial bioreactor capacity, and the resulting investment by governments and pharmaceutical companies in domestic vaccine manufacturing infrastructure has created lasting new demand for bioreactor systems at manufacturing sites around the world.
Growth in Cell and Gene Therapy Manufacturing
The rapid commercial development of cell and gene therapies represents the most significant new application driving bioreactor market growth, as these highly specialized biological medicines require dedicated bioreactor systems that are quite different from conventional pharmaceutical bioreactors and command premium pricing. The six approved CAR-T cell therapy products including Kymriah, Yescarta, Breyanzi, Abecma, Carvykti, and Tecartus collectively generated over USD 2 billion in annual revenues and are growing rapidly as clinical indications expand and as more hospitals gain experience with these treatments. The large pipeline of cell and gene therapy candidates in clinical development, with hundreds of programs across CAR-T, TCR, NK cell, and various gene therapy modalities, represents a growing wave of future demand for specialized bioreactor systems as these programs progress through clinical development and toward commercial manufacturing. The manufacturing complexity of cell and gene therapies, combined with the high commercial value of these treatments, makes this the highest-value and fastest-growing application segment in the bioreactor market.
Table of contents
14 chapters · 174 sections · 312 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Bioreactor Type | Stirred-Tank Bioreactors | Single-use bioreactors |
| By Scale | Commercial-Scale Bioreactors | Pilot-scale bioreactors |
| By Application | Biopharmaceutical Production | Cell and gene therapy |
| By End User | Biopharmaceutical Companies | Contract manufacturing organizations |
| By Mode of Operation | Fed-Batch Processing | Continuous processing |
By Bioreactor Type
- Stirred-Tank Bioreactors to Dominate
- The stirred-tank bioreactors segment is expected to account for the largest share of the global advanced bioreactor systems market.
- Stirred-tank bioreactors are the most widely used configuration in biopharmaceutical manufacturing, using mechanical agitation from an impeller to mix cells, nutrients, and gases within the bioreactor vessel.
- This is the established and proven technology for large-scale monoclonal antibody, vaccine, and recombinant protein production, with an enormous installed base at commercial manufacturing facilities globally ranging from small 200-liter development systems to large 20,000-liter commercial production bioreactors.
- However, the single-use bioreactors segment is projected to register the highest CAGR during the forecast period.
- Single-use bioreactors, which use pre-sterilized disposable plastic bags instead of fixed stainless steel vessels, eliminate the time-consuming cleaning and sterilization cycles between production runs and offer significantly faster facility setup and greater manufacturing flexibility.
- The COVID-19 pandemic response demonstrated that single-use systems can scale production of new biological products much faster than stainless steel bioreactor installations, which typically require 18 to 24 months for design, construction, and validation.
- This flexibility advantage is driving pharmaceutical manufacturers to prefer single-use systems for new facility investments and clinical manufacturing applications.
By Scale
- Commercial-Scale Bioreactors to Hold the Largest Share
- The commercial-scale bioreactors segment is expected to account for the largest share of the global advanced bioreactor systems market.
- Commercial-scale systems used in the production of approved biopharmaceutical products generate the largest revenue per unit and collectively represent the majority of total installed bioreactor capacity at the major pharmaceutical manufacturers globally.
- The large number of approved biological drugs with significant commercial scale production requirements creates sustained replacement and expansion demand for commercial-scale bioreactor systems.
- However, the pilot-scale bioreactors segment is projected to register the highest CAGR during the forecast period.
- The rapid expansion of biopharmaceutical clinical development pipelines means that more drugs are moving from discovery through process development and into clinical manufacturing, each step requiring pilot-scale bioreactor systems to develop and demonstrate the manufacturing process before committing to commercial-scale facility investment.
- The very large number of biologic drug candidates currently in clinical development globally ensures sustained and growing demand for pilot-scale development bioreactors.
By Application
- Biopharmaceutical Production to Hold the Largest Share
- The biopharmaceutical production segment is expected to account for the largest share of the global advanced bioreactor systems market.
- The production of monoclonal antibodies, vaccines, and recombinant proteins for therapeutic use represents the highest-volume and highest-value application of advanced bioreactor systems globally.
- The large annual procurement requirements of major pharmaceutical manufacturers including Roche, AbbVie, Johnson & Johnson, Pfizer, and Novartis for bioreactor systems to support their commercial biological drug manufacturing programs make biopharmaceutical production the dominant application by revenue.
- However, the cell and gene therapy segment is projected to register the highest CAGR during the forecast period.
- The combination of rapid commercial growth in approved CAR-T cell therapy products, a very large and advancing pipeline of new cell and gene therapy candidates, and the premium pricing of bioreactor systems designed for cell therapy applications makes this the fastest-growing application in the market.
- As more cell and gene therapy products receive approval and as the manufacturing industry builds out dedicated cell therapy manufacturing infrastructure, the demand for specialized bioreactor systems in this application is expected to grow at a significantly faster rate than any other segment.
By End User
- Biopharmaceutical Companies to Hold the Largest Share
- The biopharmaceutical companies segment is expected to account for the largest share of the global advanced bioreactor systems market.
- Large pharmaceutical companies including Roche Genentech, AbbVie, Regeneron, AstraZeneca, and Pfizer operate extensive in-house biomanufacturing capacity for their approved biological drugs and maintain significant ongoing investment in bioreactor systems for capacity expansion, technology upgrades, and new product launches.
- Their large scale of operations and high production volumes make them the dominant end-user category by purchasing volume.
- However, the contract manufacturing organizations segment is projected to register the highest CAGR during the forecast period.
- The growing trend of pharmaceutical companies outsourcing biological drug manufacturing to specialist CDMOs rather than investing in their own manufacturing capacity is creating rapidly growing demand for bioreactor systems at contract manufacturing facilities.
- Companies including Samsung Biologics, Lonza, Wuxi Biologics, Boehringer Ingelheim Biopharmaceuticals, and Fujifilm Diosynth Biotechnologies are all investing heavily in expanding their bioreactor capacity to serve growing outsourcing demand, and these major capital investment programs are translating into large bioreactor equipment procurement.
By Mode of Operation
- Fed-Batch Processing to Hold the Largest Share
- The fed-batch processing segment is expected to account for the largest share of the global advanced bioreactor systems market.
- Fed-batch culture, where nutrients are periodically added to the bioreactor to extend the productive phase of cell growth, is the most widely used production mode for monoclonal antibody manufacturing and represents the current industry standard for most large-scale biological drug production.
- The enormous installed base of fed-batch bioreactor systems at commercial manufacturing facilities and the regulatory approval of most existing biological drugs as fed-batch processes makes this the dominant mode of operation by market share.
- However, the continuous processing segment is projected to register the highest CAGR during the forecast period.
- The compelling productivity and cost advantages of continuous perfusion culture, combined with the regulatory frameworks being developed by FDA and EMA to accommodate continuous manufacturing, are driving pharmaceutical manufacturers to develop continuous manufacturing processes for new biological drugs and to consider converting high-volume existing products to continuous processes where the manufacturing cost savings justify the development investment.
- As more continuous bioprocessing programs reach commercial implementation, the demand for perfusion bioreactor systems and related continuous manufacturing infrastructure will grow significantly.
Geographic analysis
North America
Largest shareIn 2026, North America is expected to account for the largest share of the global advanced bioreactors market. The United States is the world's largest biopharmaceutical market by both consumption and production, home to the majority of the world's leading biopharmaceutical companies including Amgen, Genentech/Roche, Regeneron, Biogen, Gilead Sciences, and dozens of other major biological drug manufacturers, all of which operate or contract for large-scale bioreactor manufacturing capacity. The U.S. is also the center of the global cell and gene therapy industry, with the majority of CAR-T cell therapy approvals, clinical programs, and dedicated manufacturing facilities concentrated in North America. The leading bioreactor manufacturers including Thermo Fisher Scientific and several divisions of Danaher/Cytiva have strong U.S. operations, and the FDA's progressive regulatory framework for advanced biological manufacturing provides a supportive environment for technology adoption and innovation. The very large U.S. CDMO sector, anchored by companies including Lonza's U.S. operations, Samsung Biologics' U.S. client base, and numerous domestic CDMOs, generates substantial bioreactor procurement demand alongside the in-house manufacturing programs of major pharmaceutical companies.
Asia-Pacific
Fastest growthHowever, the Asia-Pacific advanced bioreactor systems market is expected to grow at the fastest CAGR during the forecast period. China's biopharmaceutical industry has grown very rapidly over the past decade, with a large and growing pipeline of domestically developed biological drugs and biosimilars creating strong domestic demand for bioreactor manufacturing capacity. Chinese CDMOs including WuXi Biologics and Shanghai Pharma Biologic have made very large investments in bioreactor capacity, making China one of the largest and most rapidly growing bioreactor markets in the world. India's biosimilar manufacturing industry, which exports to both emerging and developed markets, relies heavily on large-scale bioreactor systems and represents an important and growing Asia-Pacific market. Japan's advanced biopharmaceutical industry, South Korea's growing biologics sector supported by Samsung Biologics and Celltrion, and Singapore's strategic positioning as a regional biomanufacturing hub with government-supported life sciences manufacturing investments all contribute to the region's high growth trajectory. The rapid growth of cell and gene therapy development programs in China, Japan, and South Korea is creating new demand for specialized cell therapy bioreactor systems in Asia-Pacific.
Europe
Europe is a major and technically sophisticated bioreactor equipment market, driven by the large biopharmaceutical manufacturing operations of Roche, Novartis, AstraZeneca, and UCB, the strong European CDMO sector including Lonza Switzerland, Boehringer Ingelheim Germany, and Rentschler Biopharma, and the home base of leading bioreactor manufacturers including Sartorius in Germany, Eppendorf in Germany, Infors in Switzerland, and Kuhner in Switzerland. Switzerland in particular is disproportionately important as both the home of major biological drug producers and several leading bioreactor technology companies. Germany's strong industrial biotechnology sector and its leadership in both pharmaceutical manufacturing and bioprocess equipment manufacturing reinforces Europe's position as a major market. The strong European cell and gene therapy development ecosystem, centered in the UK, Germany, and the Netherlands, is creating growing demand for specialized cell therapy bioreactor systems alongside the large established market for conventional biopharmaceutical production systems.
Competitive landscape
- Sartorius AG · Germany
- Thermo Fisher Scientific Inc. (U.S.)
- Cytiva/Danaher Corporation (U.S.)
- Eppendorf AG · Germany
- Merck KGaA/MilliporeSigma · Germany
- GEA Group AG · Germany
- Applikon Biotechnology/Getinge Group · Netherlands/Sweden
- PBS Biotech Inc. (U.S.)
- Distek Inc. (U.S.)
- Solaris Biotechnology Srl · Italy
- Infors AG · Switzerland
- Pierre Guerin Technologies · France
- BBI Biotech GmbH · Germany
- ZETA Holding GmbH · Austria
- Kuhner AG · Switzerland
Frequently asked questions
The global market is expected to reach USD 11.8 billion by 2036 from an estimated USD 4.2 billion in 2026, at a CAGR of 10.9% during the forecast period 2026-2036.
Cite this report
Meticulous Research. (2026). Advanced Bioreactor Systems Market - Global Opportunity Analysis And Industry Forecasts (2026-2036) (Report No. MRHC - 1041929). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/advanced-bioreactor-systems-market-6612