UAV (Drone) Propulsion Market (2026-2036)
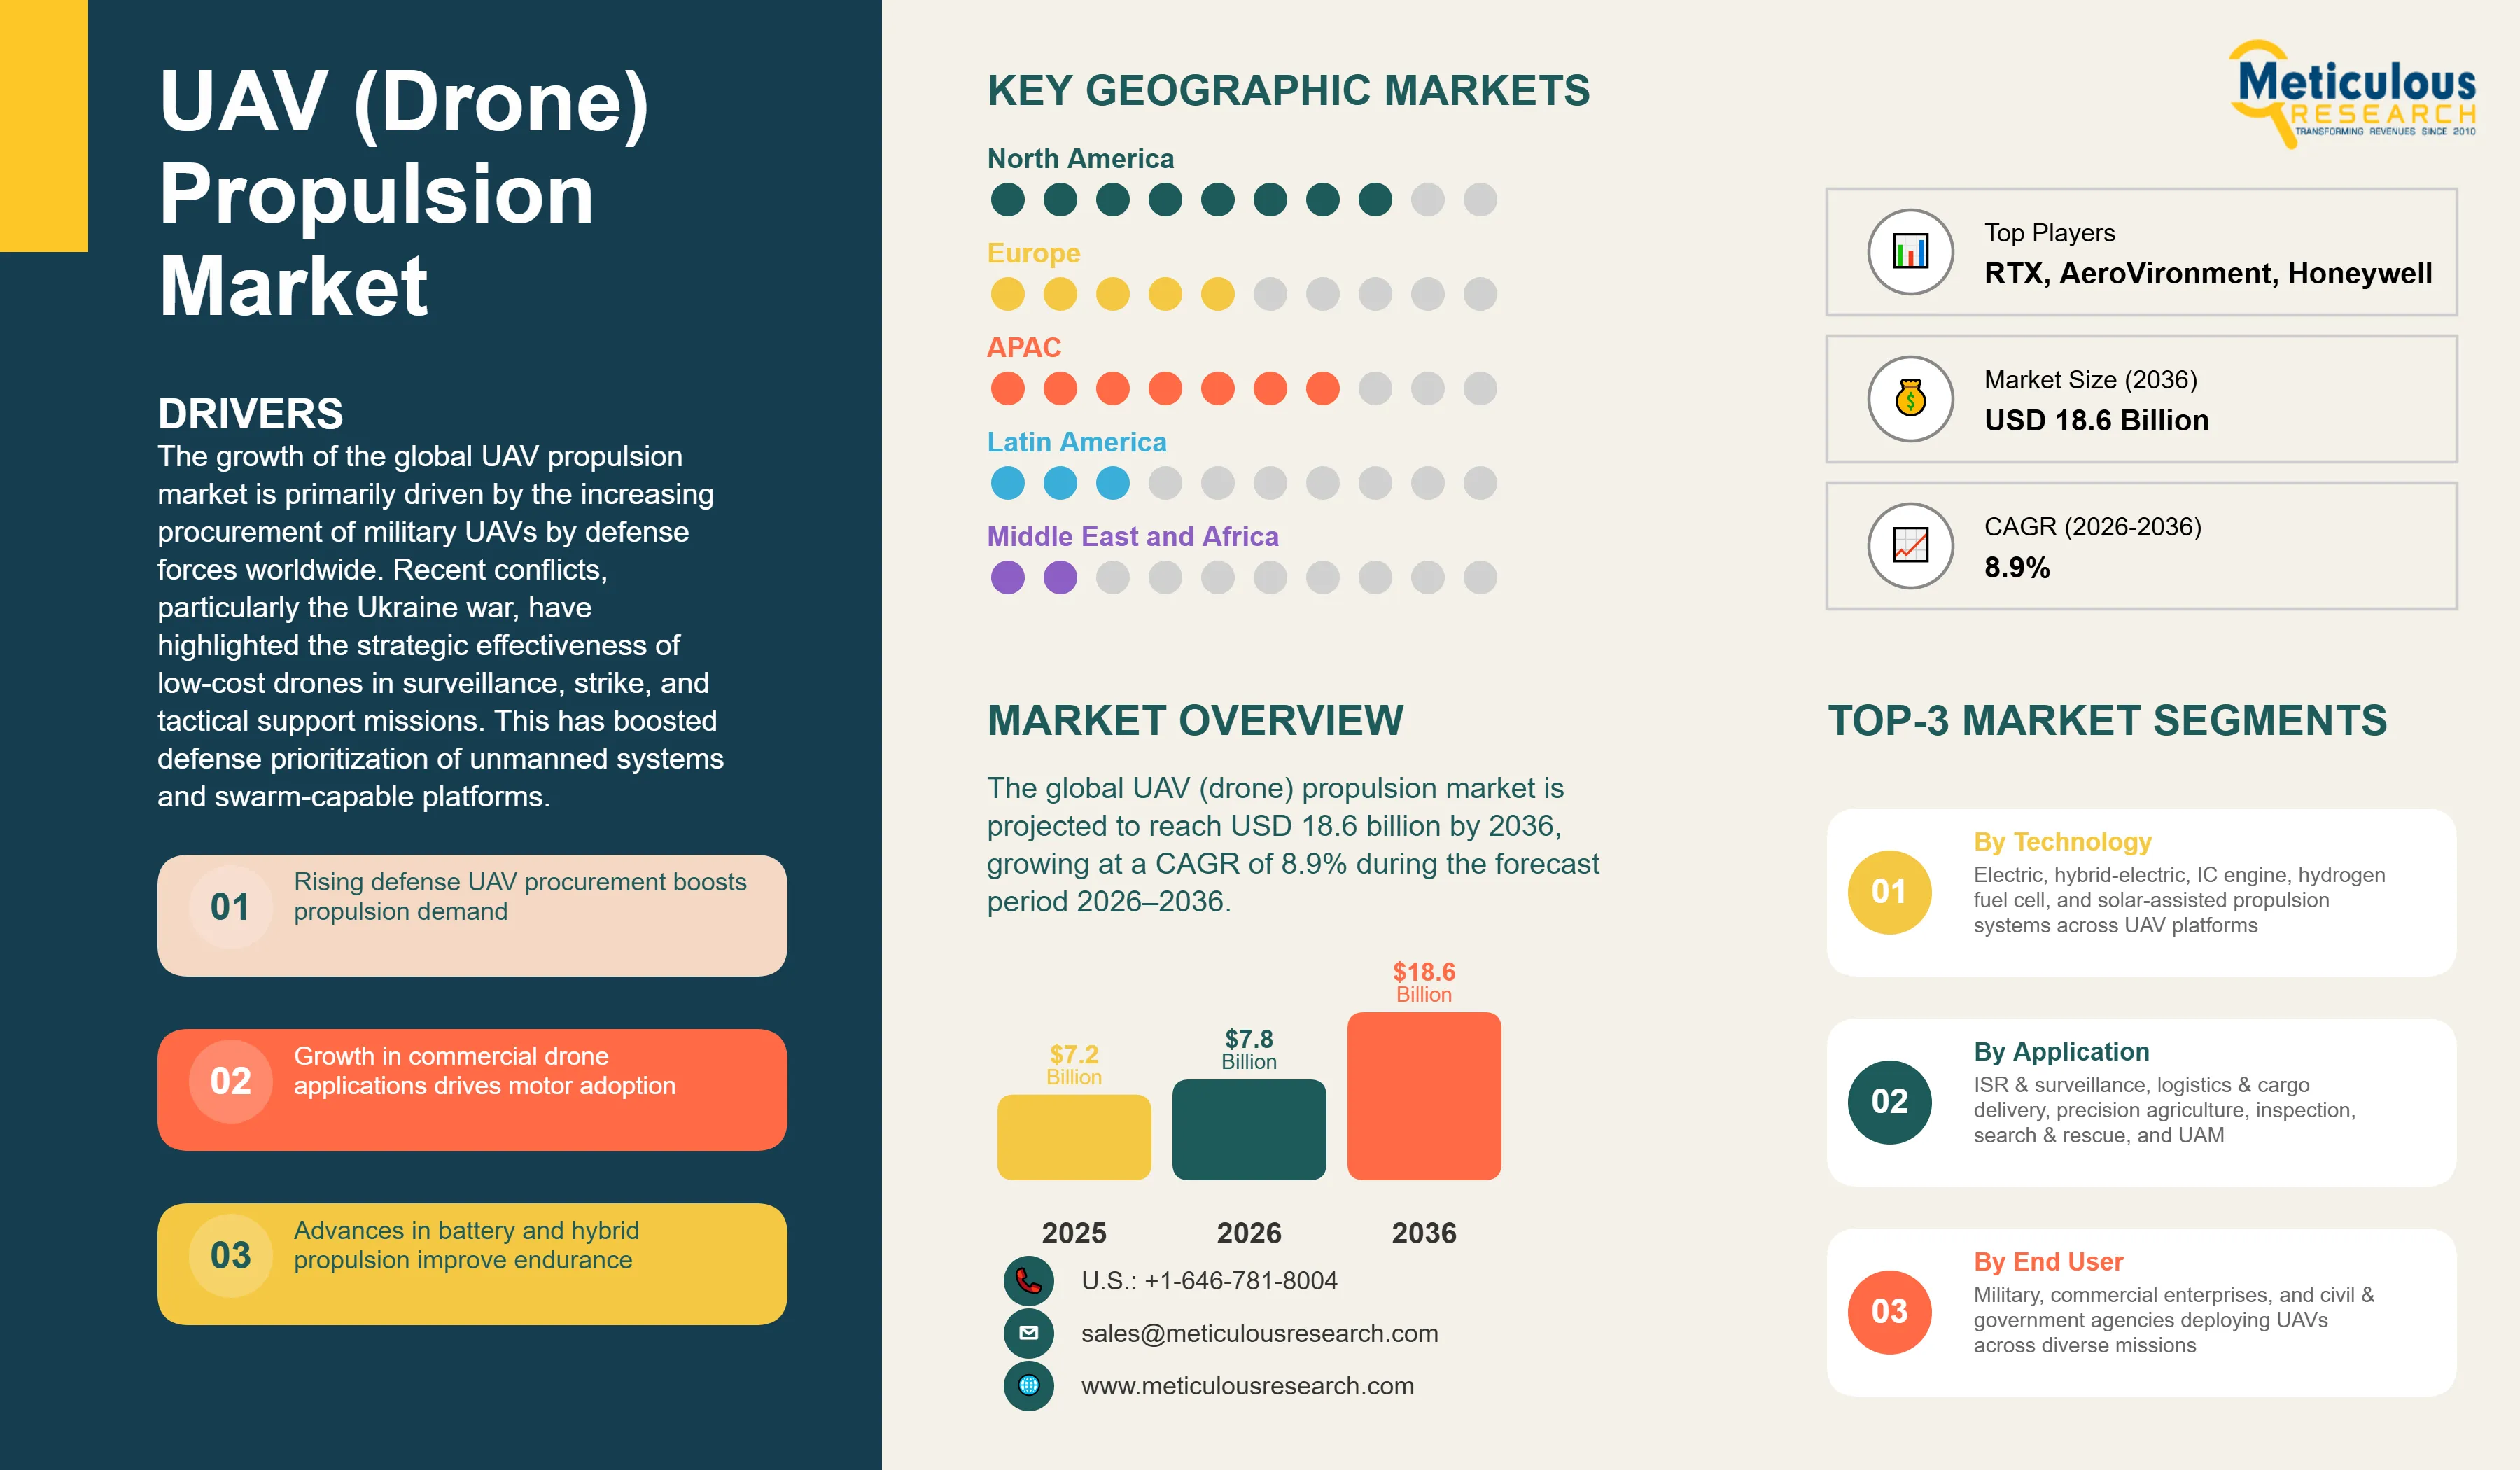
The global UAV (drone) propulsion market was valued at USD 7.2 billion in 2025. The market is projected to reach USD 18.6 billion by 2036 from an estimated USD 7.9 billion in 2026, growing at a CAGR of 8.9% during the forecast period 2026–2036.
- Published
- Apr 2026
- Pages
- 245
- Format
- PDF + Excel
- Report ID
- MR-1883
- Base year
- 2025
- 2025 · BASELINE
- $7.20B
- 2036
- $18.60B
- CAGR 2026–2036
- 8.9%
2025 baseline · 2026–2036 forecast at 8.9% CAGR · hover a bar for the value
Key highlights
The global UAV drone propulsion market is projected to reach USD 18.6 billion by 2036.
The market is expected to grow at a CAGR of 8.9% during the forecast period 2026–2036.
The global UAV propulsion market was valued at USD 7.2 billion in 2025 and is estimated to reach USD 7.9 billion in 2026.
North America is expected to dominate the global UAV propulsion market with the largest market share in 2026, driven by the U.S. defense budget, the world's largest UAV procurement base, strong R&D investment in advanced propulsion by GE Aerospace, RTX, Honeywell, General Atomics, and Kratos, and the FAA's expanding commercial drone regulatory framework enabling large-scale BVLOS operations.
Asia Pacific is projected to witness the fastest growth during the forecast period, driven by China's trillion-yuan low-altitude economy charter subsidizing domestic propulsion production, India's Atmanirbhar indigenous propulsion development initiative, and Japan's gas-turbine electric hybrid programs for urban eVTOL.
By technology, electric propulsion is expected to hold the largest market share in 2026, dominating lightweight and commercial drone applications where low noise, low maintenance, and zero-emission operation are prioritized.
By technology, hybrid-electric propulsion is projected to register the highest CAGR during the forecast period, driven by its unique ability to combine IC engine endurance with electric motor efficiency.
By component, the IC engine segment is expected to account for the largest market share in 2026, reflecting the power requirements of medium and large defense UAVs where electric propulsion alone is insufficient for long-endurance ISR and combat missions.
By component, the power source segment (batteries and fuel cells) is projected to register the highest CAGR during the forecast period, driven by advances in high-density battery chemistries and hydrogen fuel cell miniaturization enabling longer-endurance commercial and defense missions.
By platform, the military segment is expected to hold the largest market share in 2026, while the commercial segment is projected to register the fastest growth driven by logistics, agriculture, inspection, and UAM applications.
By application, ISR and surveillance is expected to hold the largest share in 2026, while logistics and cargo delivery is projected to register the highest CAGR driven by e-commerce fulfillment, medical supply, and last-mile delivery drone deployments.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 18.6 Billion |
| Market Size in 2026 | USD 7.8 Billion |
| Market Size in 2025 | USD 7.2 Billion |
| Revenue Growth Rate (2026–2036) | CAGR of 8.9% |
| Format | PDF, Excel & Cloud Portal · 245 pages |
| Dominating Technology | Electric Propulsion |
| Fastest Growing Technology | Hybrid-Electric Propulsion |
| Dominating Component | IC Engine |
| Fastest Growing Component | Power Source (Battery & Fuel Cell) |
| Dominating Platform | Military |
| Fastest Growing Platform | Commercial |
| Dominating MTOW Class | 2–25 kg |
| Fastest Growing MTOW Class | 25–150 kg |
| Dominating Application | ISR & Surveillance |
| Fastest Growing Application | Logistics & Cargo Delivery |
| Dominating Geography | North America |
| Fastest Growing Geography | Asia Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
Report overview
Segments covered: technology, component, platform, maximum takeoff weight, application, mtow.
The global UAV (drone) propulsion market comprises the complete range of power generation, energy storage, and thrust transmission systems used to propel unmanned aerial vehicles. This includes internal combustion engines (turbofan, turboprop, Wankel/rotary, piston gasoline, and heavy-fuel engines), electric motors, battery energy storage systems (Li-Ion, Li-Po, lithium-sulfur, and solid-state batteries), hydrogen fuel cells, solar photovoltaic panels, propellers and rotors, electronic speed controllers (ESCs), and associated power management and control electronics.
These propulsion systems define the core operating performance of a UAV platform. Key parameters include flight endurance, operational range, payload capacity, maximum altitude, acoustic signature, and thermal signature. Together, these factors determine the suitability of UAV platforms for specific mission profiles across military, commercial, and civil applications.
The growth of the global UAV propulsion market is primarily driven by the increasing procurement of military UAVs by defense forces worldwide. Recent conflicts, particularly the Ukraine war, have highlighted the strategic effectiveness of low-cost drones in surveillance, strike, and tactical support missions. This has boosted defense prioritization of unmanned systems and swarm-capable platforms.
The rapid expansion of commercial drone applications is another major growth driver. According to the FAA, the U.S. recorded 453,635 cumulative commercial UAS registrations and 481,760 certificated remote pilots as of November 2025. This reflects the expanding installed base of drones across inspection, mapping, agriculture, logistics, and surveillance applications, directly driving demand for motors, batteries, ESCs, and advanced propulsion systems.
Commercial deployment is also growing globally. According to Drone Industry Insights’ 2025 global survey, the study covered 768 companies across 87 countries, confirming continued enterprise-scale adoption of drones for infrastructure inspection, precision agriculture, public safety, and logistics operations.
Continuous advancements in propulsion technologies are further driving the overall growth of the UAV (drone) propulsion market. Improvements in brushless motors, lightweight battery packs, hybrid-electric systems, and hydrogen fuel cell integration are expanding the performance envelope of UAV platforms across all weight classes.
However, the market faces several restraints. The limited energy density of current lithium-ion batteries continues to restrict the endurance of pure-electric UAVs, with flight duration for many small and medium platforms still remaining below one hour depending on payload and environmental conditions. In addition, propulsion miniaturization remains a major technical challenge for micro drones and swarm UAVs, where systems must deliver sufficient thrust without compromising reliability or payload capacity.
The market offers significant growth opportunities in beyond-visual-line-of-sight (BVLOS) operations, autonomous swarm deployment, and long-endurance mission profiles. Recent regulatory progress, including the FAA’s proposed framework for normalizing BVLOS UAS operations and third-party UTM services, is expected to drive commercial deployment across logistics, infrastructure inspection, and surveillance applications. This is likely to create substantial demand for high-efficiency propulsion systems with longer endurance and improved reliability.
Another major opportunity lies in the increasing deployment of UAV swarms and micro drones for defense, border monitoring, and search-and-rescue operations. Recent developments in Ukraine indicate growing investment in multi-drone coordinated systems, with domestic production of interceptor drones scaling to around 2,000 units per day and swarm capabilities under active development. This trend is driving demand for compact, lightweight, and modular propulsion solutions that can deliver high thrust-to-weight performance, rapid response capability, and operational redundancy.
A key market trend is the increasing development of hydrogen fuel cell propulsion systems. In June 2025, H3 Dynamics and XSun announced a solar-hydrogen-electric tribrid UAV platform designed to deliver up to 12 hours of endurance and approximately 600 km range, highlighting the growing commercial viability of next-generation clean propulsion technologies. This trend is expected to significantly reshape long-endurance UAV applications across defense, infrastructure inspection, and logistics use cases over the forecast period.
IC engines continue to remain the preferred propulsion component for MALE (Medium Altitude Long Endurance), HALE (High Altitude Long Endurance), tactical ISR, combat, and long-range logistics UAVs.
This segment is further supported by the continued deployment of advanced propulsion systems such as GE Aerospace and Kratos’ GEK800 small turbine engine, which successfully completed altitude testing for next-generation unmanned systems.
In addition, rotary and heavy-fuel engines continue to play a critical role in tactical UAVs due to their superior power-to-weight ratio, smoother power delivery, and longer endurance.
Companies such as UAV Engines Ltd., LiquidPiston, Rotron Power, and BRP-Rotax continue to strengthen this segment through advanced Wankel and piston-based propulsion systems.
These engine architectures provide the energy density and specific power output required for multi-hour to multi-day missions, which remain difficult to achieve with current battery technology.
This is expected to drive strong growth in batteries and fuel cells across delivery drones, industrial inspection UAVs, and hybrid-electric platforms over the forecast period.
These platforms increasingly require hybrid-electric or IC engine propulsion systems to achieve flight endurance and payload capacity beyond the limitations of battery-only systems.
This is expected to support strong growth in propulsion demand across this segment over the forecast period.
This includes large-scale deployment of MALE and HALE platforms, such as General Atomics’ MQ-9 Reaper and Northrop Grumman’s RQ-4 Global Hawk, along with comparable international systems used for border monitoring, maritime patrol, tactical ISR, and persistent battlefield surveillance.
The segment also benefits from increasing deployment of drones for law enforcement, border security, coastal surveillance, and critical infrastructure monitoring across civil and government applications.
Large-scale delivery drone operations create recurring demand for propulsion systems, battery replacement, maintenance, repair, and overhaul (MRO) services, resulting in a strong aftermarket revenue opportunity over the forecast period.
Report infographic
Market dynamics
3 factors across 1 forceHybrid-Electric Propulsion Bridging the Endurance Gap Between Pure-Electric and IC Engine Systems
One of the key trends shaping the global UAV propulsion market is the rapid advancement of hybrid-electric propulsion systems. These systems combine a conventional internal combustion (IC) engine or hydrogen fuel cell with electric motors and battery storage to deliver improved endurance, higher operational efficiency, and optimized peak power management.
Hybrid-electric propulsion is enabling a new generation of UAV platforms that address the key limitations of both pure-electric and conventional engine architectures. While battery-powered UAVs continue to face endurance constraints due to current battery energy density limits, conventional engine systems often involve higher noise levels, vibration, and maintenance complexity. Hybrid systems offer an effective balance between these technologies.
For logistics and cargo delivery UAVs, hybrid-electric systems are increasingly preferred for missions requiring multi-hour flight endurance and payload capacities in the 5–25 kg range. These systems can typically support 3–6 hours or more of endurance, compared with approximately 30–60 minutes for battery-only platforms, depending on payload and mission profile. Electric motors are also increasingly used during hover, take-off, and low-speed operations, helping reduce acoustic signature and improve operational flexibility.
In the military and ISR segment, hybrid-electric propulsion is emerging as a strategically important architecture for long-endurance missions. Defense UAVs designed for persistent surveillance, border monitoring, and tactical reconnaissance increasingly require 12–24 hours of continuous flight capability with reduced thermal and acoustic signatures. Hybrid systems integrating heavy-fuel generators with electric motors are gaining traction in these applications.
This trend is expected to remain a key driver of propulsion innovation over the forecast period, particularly across defense, long-range logistics, and high-endurance commercial drone applications.
Hydrogen Fuel Cell Propulsion Enabling Ultra-Long-Endurance Zero-Emission UAV Missions
Hydrogen fuel cell propulsion is emerging as one of the most significant trends in the global UAV propulsion market. The commercialization of proton exchange membrane fuel cell (PEMFC)-based systems is enabling a new class of long-endurance UAV platforms capable of significantly exceeding the flight time limitations of conventional battery-powered drones.
Compared with advanced lithium-ion battery systems, hydrogen fuel cells offer materially higher usable energy density, enabling a step change in endurance, range, and mission flexibility. This is particularly important for long-range surveillance, logistics, infrastructure inspection, environmental monitoring, and defense resupply missions, where multi-hour flight capability is becoming a key performance requirement.
A major industry milestone was announced in June 2025, when H3 Dynamics and XSun unveiled a solar-hydrogen-electric tribrid UAV architecture. Based on the SolarXOne platform, the system integrates wing-mounted solar PV, battery packs for take-off power, and a compact hydrogen fuel cell for cruise propulsion. The platform is designed to support up to 12 hours of endurance and around 600 km operational range, highlighting the growing commercial viability of hydrogen-powered UAV systems.
Another key development is the growing use of hydrogen propulsion in cargo delivery and tactical logistics drones. Platforms such as HevenDrones’ H2D200 series and Honeywell’s hydrogen fuel cell systems are demonstrating longer mission duration, lower acoustic signature, and reduced maintenance compared with small internal combustion engines. Honeywell states that its hydrogen systems can provide up to three times longer runtime than battery-based alternatives.
North America continues to remain a key market for hydrogen UAV propulsion, driven by defense modernization initiatives, aerospace innovation programs, and increasing investment in clean aviation technologies.
This trend is expected to significantly reshape long-endurance UAV operations over the forecast period, mainly across defense, industrial inspection, and zero-emission logistics applications.
Additive Manufacturing and AI Integration Transforming Propulsion System Development Economics
Additive manufacturing and AI integration are emerging as key technology trends in the global UAV propulsion market. The increasing use of 3D printing for propulsion component production is significantly transforming the economics of engine design, development, and manufacturing.
Additive manufacturing enables the production of complex internal cooling channels, topology-optimized lightweight structures, and consolidated multi-part assemblies in a single print cycle. This reduces lead times, lowers tooling costs, minimizes material wastage, and accelerates prototype-to-production timelines. The technology is particularly valuable in small turbine engine development, where conventional machining of titanium and nickel-based superalloys is often expensive and time-intensive.
A key example of this trend is Beehive Industries’ USD 12.46 million contract, awarded in collaboration with the U.S. Air Force Rapid Sustainment Office and the University of Dayton Research Institute. The program focuses on the development of an additively manufactured 200-lbf small expendable turbine engine for tactical UAVs and loitering munitions. The contract includes engine design, manufacturing, qualification testing, flight validation, and an initial production run of 30 engines within 24 months. This highlights how additive manufacturing is enabling new entrants to compete with established aerospace players on both cost and scalability.
Another important trend is the growing integration of AI-driven power management and predictive maintenance systems. These platforms enable intelligent energy allocation across hybrid propulsion architectures by dynamically distributing power between batteries, fuel cells, and internal combustion generators based on real-time mission conditions, weather parameters, payload requirements, and component health.
AI-enabled predictive maintenance is also improving propulsion system uptime by identifying early signs of motor, battery, or turbine degradation. This helps reduce unscheduled downtime, extend maintenance intervals, and improve overall mission reliability, particularly for defense and long-endurance UAV applications.
This trend is expected to significantly reduce propulsion development costs and compress product development cycles over the forecast period, creating new growth opportunities for both established manufacturers and emerging defense-focused startups.
Table of contents
12 chapters · 166 sections · 245 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Technology | Electric propulsion | Hybrid-electric propulsion |
| By Platform | Military | Commercial |
| By Component | IC engine | Power source segment (batteries and fuel cells) |
| Other segments | IC engines | Power source segment (batteries and fuel cells) |
| By Maximum Takeoff Weight | — | 25–150 kg |
| By Application | ISR and surveillance | Logistics and cargo delivery |
By Technology
- The global UAV propulsion market is segmented into electric propulsion, conventional / IC engine propulsion, hybrid-electric propulsion, hydrogen fuel cell propulsion, and solar-assisted propulsion.
- The electric propulsion segment is expected to account for the largest share of the overall UAV propulsion market.
- The large share of this segment is primarily attributed to the dominant deployment of electric propulsion systems across commercial, industrial, and consumer drone applications.
- These include consumer imaging drones, agricultural spraying UAVs, inspection and mapping platforms, public safety drones, and last-mile delivery systems.
- Electric propulsion remains the preferred technology for lightweight UAV platforms due to its low acoustic signature, minimal maintenance requirements, zero direct emissions, high energy efficiency, and precise thrust control through electronic speed controllers (ESCs).
- In addition, continuous improvements in lithium-ion and lithium-polymer battery technologies, including higher energy density, faster charging capability, and improved thermal management, continue to support the adoption of electric propulsion systems.
- Lithium-based batteries accounted for more than 85% of total drone battery technology deployment in 2025, further driving the leadership of this segment.
- However, the hybrid-electric propulsion segment is projected to register the highest CAGR during the forecast period.
- The high growth of this segment is driven by its ability to overcome the endurance limitations of pure-electric systems while maintaining lower noise and thermal signatures than conventional engine-based alternatives.
- Hybrid-electric architectures enable 3–6+ hours of flight endurance, compared with around 30–60 minutes for battery-only platforms, depending on payload and mission conditions.
- This makes hybrid-electric propulsion increasingly suitable for long-range logistics drones, medium-endurance defense ISR UAVs, large agricultural drones, and persistent infrastructure monitoring platforms.
- ISR propulsion systems typically command a higher per-platform value due to the advanced propulsion architectures required for long-endurance, high-altitude, and mission-critical operations.
- These include small turbine engines, heavy-fuel IC engines, and hybrid-electric propulsion systems, which significantly increase component value compared with standard commercial drones.
By Platform
- The dominance of this segment is further driven by the large installed base of small UAVs globally.
- FAA forecasts confirm a 1.87 million-unit U.S. recreational small drone fleet entering 2025, reaching 1.93 million units by 2029, with total active fleets (including commercial) reaching 2.26 million units in 2025.
- The large share of this segment is primarily attributed to the high-value contribution of propulsion systems used in medium, large, and long-endurance UAV platforms, particularly across defense and heavy commercial applications.
- These platforms require significantly higher endurance, altitude capability, and payload capacity than battery-only systems can currently support.
- In addition, AI-enabled battery management systems, modular battery packs, and rapid charging architectures are improving energy utilization, reducing downtime, and enhancing fleet economics for commercial drone operators.
- The 2–25 kg segment is expected to account for the largest share of the global UAV propulsion market.
- The large share of this segment is primarily attributed to its position as the most commercially active and widely deployed UAV weight class globally.
- This segment includes consumer-grade photography drones, agricultural spraying systems, inspection and mapping platforms, public safety drones, and small cargo delivery UAVs.
- This weight class offers an optimal balance between portability, payload capacity, operational endurance, and regulatory flexibility, making it the most versatile UAV category across commercial and industrial applications.
- In addition, the segment benefits from strong deployment across regulated commercial operations.
- Under the FAA’s Part 107 framework, most commercial drones are required to operate below 55 pounds (approximately 25 kg), which directly supports the dominance of this MTOW category.
- The large share of this segment is primarily driven by sustained military procurement of long-endurance reconnaissance and surveillance UAVs across major defense markets.
- The strong growth of this segment is driven by the rapid commercial deployment of delivery drones by companies such as Amazon Prime Air, Wing, Zipline, and Manna, along with increasing use of drones for medical supply delivery in remote and underserved regions.
- This segment is also benefiting from the expansion of China’s low-altitude economy policy framework, which is accelerating domestic drone delivery networks and commercial UAV deployment.
By Component
- The global UAV propulsion market is segmented into IC engines (turbofan, turboprop, Wankel/rotary, piston gasoline, and heavy-fuel engines), electric motors, batteries, fuel cells, solar panels, propellers and rotors, electronic speed controllers, and other components.
- The high growth of this segment is driven by the growing adoption of advanced battery chemistries, including lithium-sulfur, solid-state, and high-density lithium-ion formats, along with the increasing commercialization of hydrogen fuel cell systems.
Other segments
- The IC engines segment is expected to account for the largest share of the global UAV propulsion market in value terms.
- However, the power source segment (batteries and fuel cells) is projected to register the highest CAGR during the forecast period.
By Maximum Takeoff Weight
- The global UAV propulsion market is segmented into less than 2 kg, 2–25 kg, 25–150 kg, and above 150 kg.
- The 2–25 kg segment is also the primary platform category for the rapidly expanding precision agriculture market.
- The 2–25 kg segment is also the primary platform category for the rapidly expanding precision agriculture market.
- Platforms such as DJI’s AGRAS series and XAG’s P100 Pro agricultural drones continue to drive high-volume demand for motors, batteries, ESCs, and rotor systems, particularly across China, Southeast Asia, and other high-adoption agricultural markets.
- However, the 25–150 kg segment is projected to register the highest CAGR during the forecast period.
- This growth is primarily driven by the increasing deployment of medium-class UAVs for long-range cargo delivery, border surveillance, defense tactical missions, and industrial heavy-lift applications.
By Application
- The global UAV propulsion market is segmented into ISR & surveillance, precision agriculture, logistics & cargo delivery, infrastructure inspection & mapping, search & rescue, urban air mobility, and combat & strike.
- The ISR & surveillance segment is expected to account for the largest share of the global UAV propulsion market.
- However, the logistics & cargo delivery segment is projected to register the highest CAGR during the forecast period.
Geographic analysis
North America
Largest shareIn 2026, North America is expected to account for the largest share of the global UAV propulsion market. North America’s dominant position is primarily supported by the world’s largest defense UAV procurement ecosystem, led by the United States Department of Defense and allied defense programs. The region continues to witness large-scale deployment of advanced UAV platforms, including the MQ-9 Reaper, RQ-4 Global Hawk, and MQ-25 Stingray, which require high-value propulsion systems such as turboprop engines, small turbine engines, hybrid propulsion modules, and advanced power management systems. The region also benefits from a strong concentration of propulsion technology companies and UAV manufacturers, including GE Aerospace, Honeywell International, RTX Corporation, General Atomics, Kratos Defense & Security Solutions, AeroVironment, and Joby Aviation. In addition, the FAA’s evolving regulatory framework, including Part 107 operations and progress toward broader BVLOS enablement, continues to support commercial UAV deployment across logistics, inspection, and surveillance applications. Recent developments further reinforce North America’s leadership. The GE Aerospace–Kratos collaboration on the GEK800 small engine platform and ongoing defense-focused propulsion innovation continue to strengthen the regional ecosystem. North America U.S. Canada Mexico
Asia-Pacific
Fastest growthHowever, Asia Pacific is expected to register the fastest growth rate during the forecast period. The strong growth of this region is primarily driven by China’s large-scale commercial drone manufacturing ecosystem, increasing defense modernization programs across India, Japan, South Korea, and Australia, and the rapid expansion of agricultural and logistics drone applications. China continues to remain the global hub for commercial drone production, led by companies such as DJI, XAG, T-Motor, Hobbywing, and Grepow, creating sustained regional demand for motors, batteries, ESCs, and hybrid propulsion systems. India is also emerging as a key growth market, supported by domestic manufacturing initiatives, defense indigenization programs, and increasing deployment of drones across agriculture, border surveillance, and infrastructure monitoring. In addition, Japan and South Korea are witnessing increasing investments in hybrid-electric and hydrogen-powered UAV platforms, including eVTOL and advanced defense drone programs. This combination of large-scale commercial deployment, regional manufacturing strength, and defense-led innovation is expected to support the fastest growth in Asia Pacific over the forecast period. By Geography (Revenue, USD Million, 2026–2036) Japan South Korea Australia Rest of Asia-Pacific
Europe
U.K. Germany France Italy Spain Netherlands Rest of Europe
Middle East & Africa
Saudi Arabia UAE Israel South Africa Rest of Middle East & Africa
Competitive landscape
- SZ DJI Technology Co., Ltd. · China
- RTX Corporation (U.S.)
- Honeywell International Inc. (U.S.)
- Rolls-Royce Holdings plc (U.K.)
- GE Aerospace (U.S.)
- T-Motor · China
- BRP-Rotax GmbH & Co KG · Austria
- General Atomics Aeronautical Systems, Inc. (U.S.)
- Kratos Defense & Security Solutions, Inc. (U.S.)
- AeroVironment, Inc. (U.S.)
- Intelligent Energy Limited (U.K.)
- Shenzhen Hobbywing Technology Co., Ltd. · China
- Shenzhen Grepow Battery Co., Ltd. · China
- Rotron Power Limited (U.K.)
- Hirth Engines GmbH · Germany
Frequently asked questions
The global UAV propulsion market is expected to reach USD 18.6 billion by 2036 from an estimated USD 7.9 billion in 2026, at a CAGR of 8.9% during the forecast period 2026–2036.
Cite this report
Meticulous Research. (2026). UAV (Drone) Propulsion Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MR-1883). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/uav-drone-propulsion-market-6566