Small Satellite Propulsion Market (2026-2036)
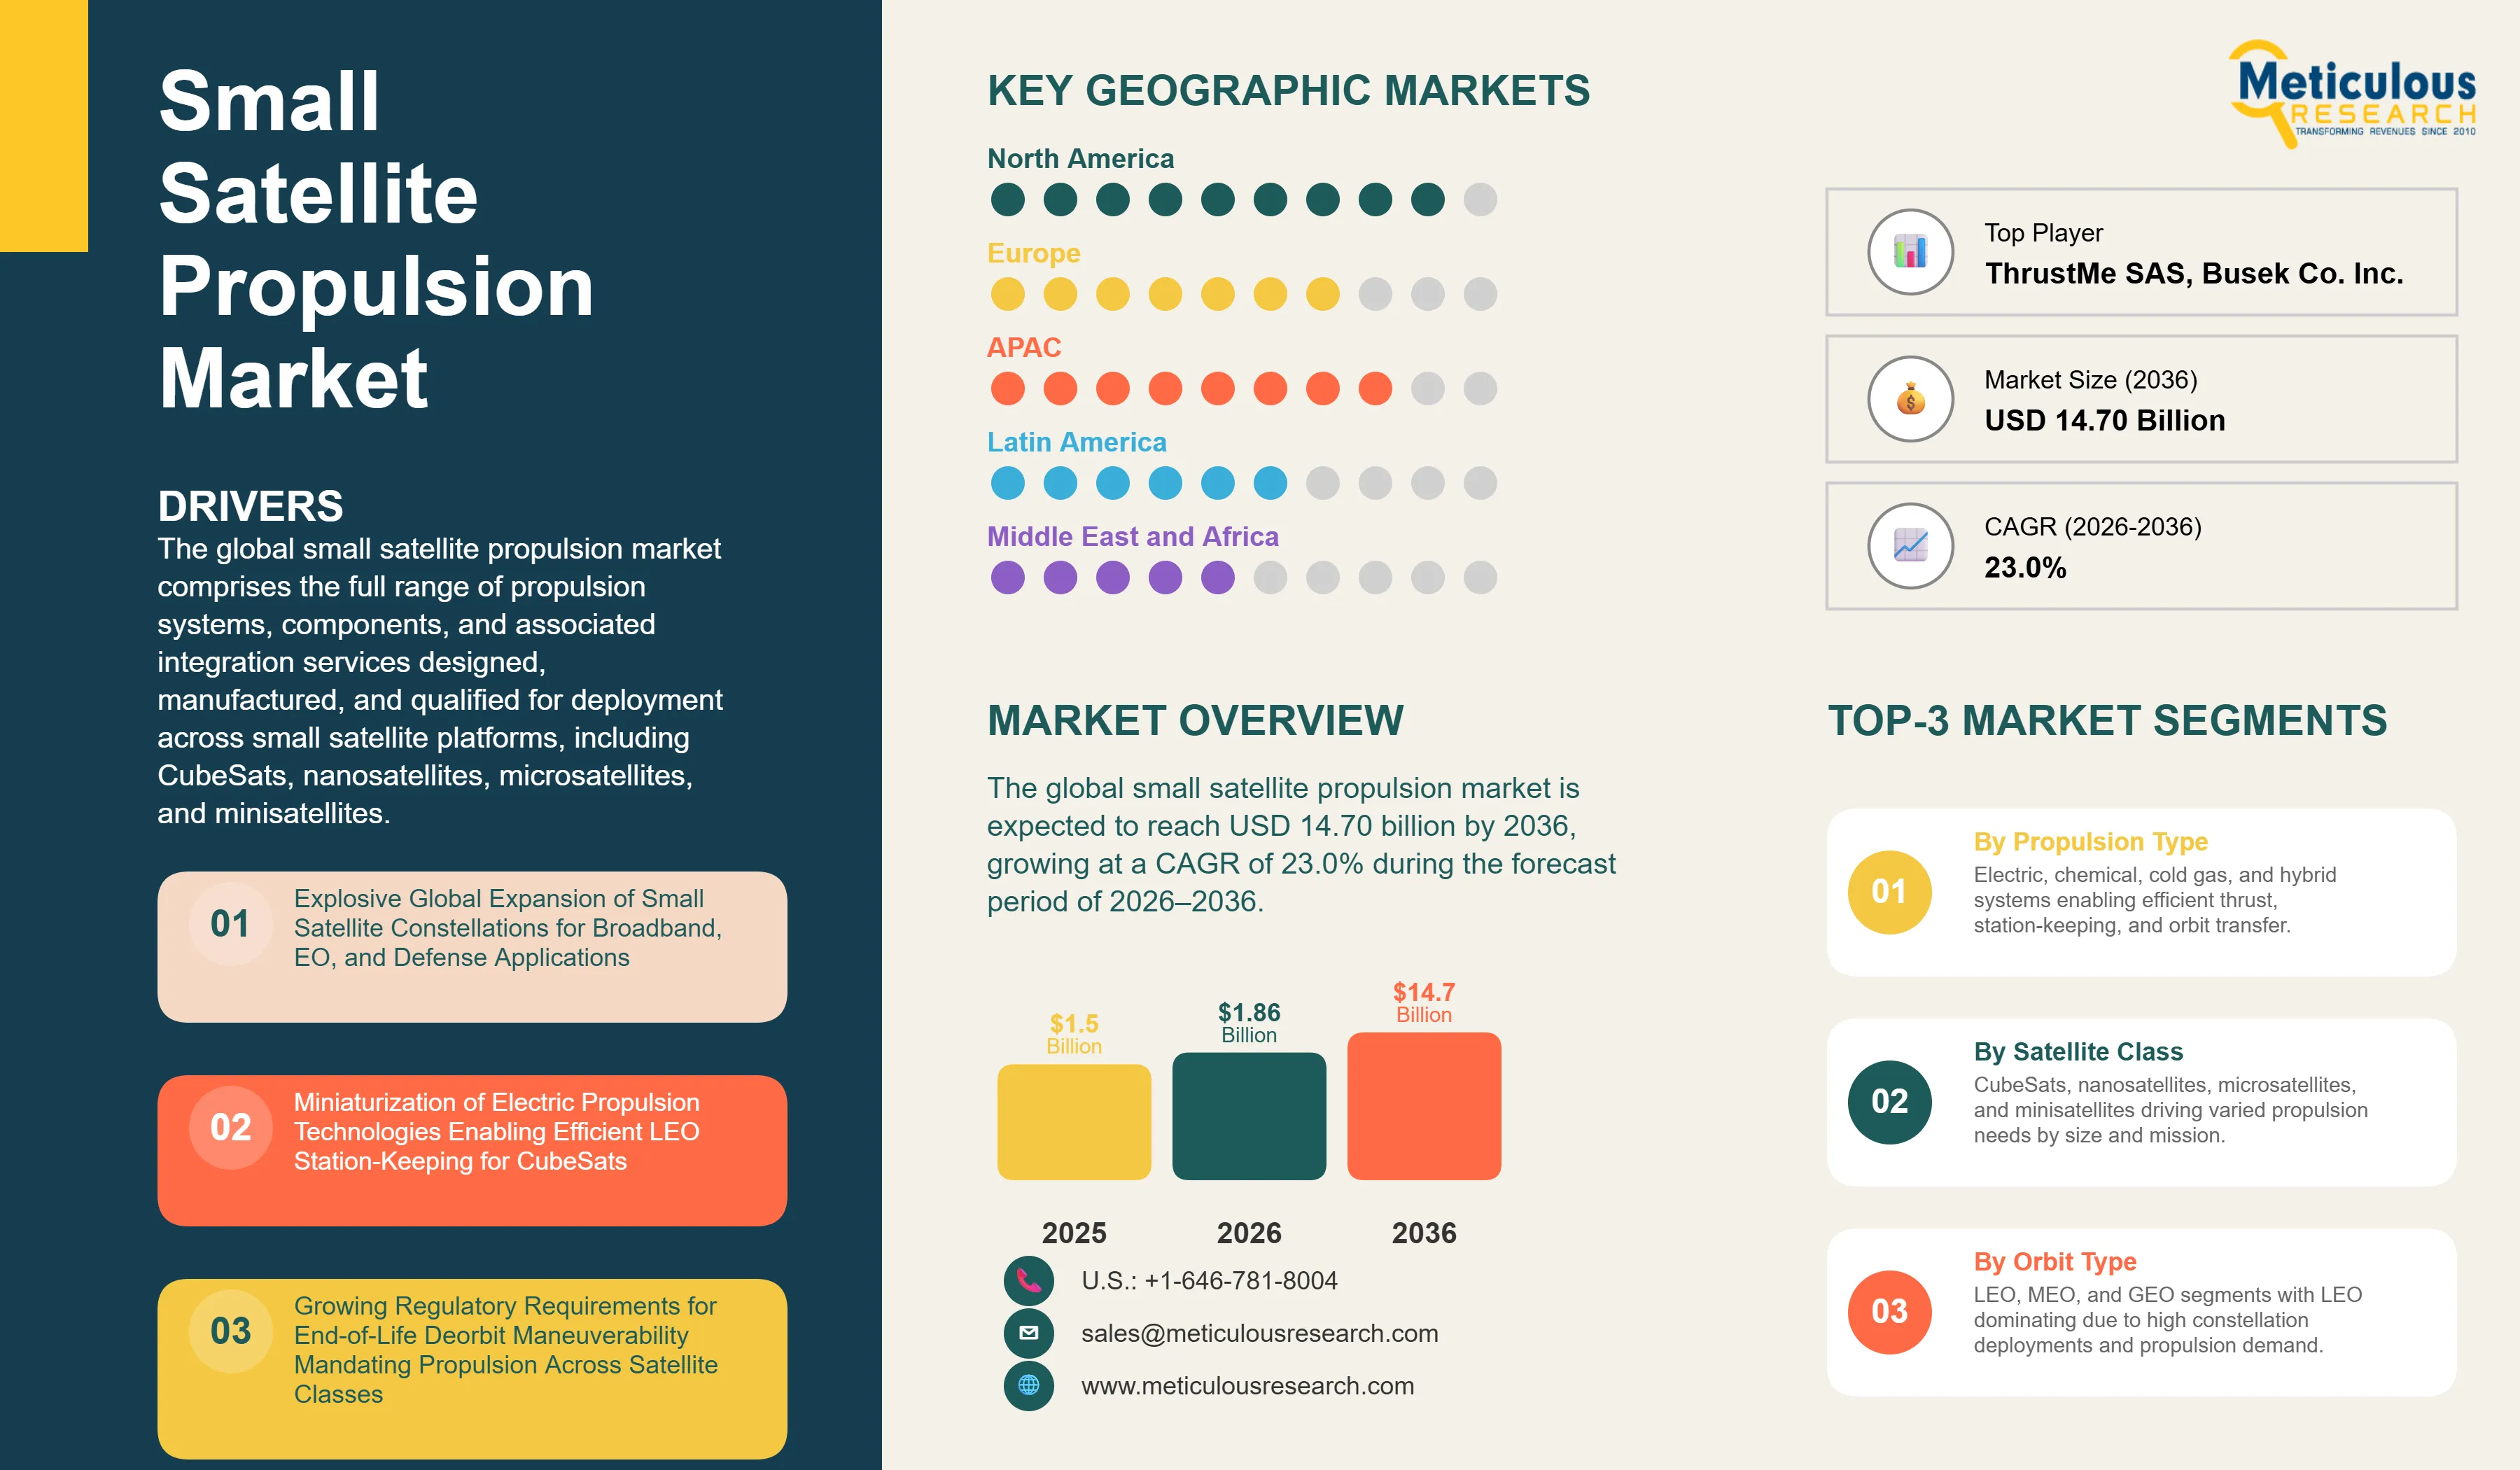
The global small satellite propulsion market was valued at USD 1.50 billion in 2025. This market is expected to reach USD 14.70 billion by 2036 from an estimated USD 1.86 billion in 2026, growing at a CAGR of 23.0% during the forecast period of 2026–2036.
- Published
- Apr 2026
- Pages
- 247
- Format
- PDF + Excel
- Report ID
- MR-1872
- Base year
- 2025
- 2025 · BASELINE
- $1.50B
- 2036
- $14.70B
- CAGR 2026–2036
- 23.0%
2025 baseline · 2026–2036 forecast at 23.0% CAGR · hover a bar for the value
Key highlights
The global small satellite propulsion market is projected to reach USD 14.70 billion by 2036.
The market is expected to grow at a CAGR of 23.0% during the forecast period 2026–2036.
The global small satellite propulsion market was valued at USD 1.50 billion in 2025 and is estimated to reach USD 1.86 billion in 2026.
North America is expected to dominate the global small satellite propulsion market with the largest market share in 2026, driven by the highest global concentration of small satellite operators and launch providers, the presence of leading propulsion technology companies including Aerojet Rocketdyne, Moog, Busek, and Bradford ECAPS, and strong government and defense procurement through NASA, DARPA, and the U.S. Space Force.
Asia Pacific is projected to witness the fastest growth during the forecast period, driven by massive national space program investments in China, India, Japan, and South Korea; the rapid expansion of commercial small satellite ecosystems; and the emergence of indigenous propulsion technology companies across the region.
By propulsion type, the electric propulsion segment is expected to hold the largest market share in 2026, accounting for around 55–60% of the market, driven by its superior specific impulse, fuel efficiency, and suitability for LEO constellation station-keeping.
By propulsion type, the hybrid propulsion segment is projected to register the highest CAGR during the forecast period, driven by the growing adoption of multi-mode systems combining chemical and electric propulsion for mission flexibility.
By satellite class, the microsatellites segment is expected to hold the largest share in 2026, while the CubeSats segment is projected to register the highest CAGR during the forecast period.
By orbit type, low earth orbit is expected to account for the largest share of the market in 2026, reflecting the dominant role of LEO constellation deployments in driving propulsion procurement volumes.
By application, the communication segment is expected to account for the largest share in 2026, while the earth observation and remote sensing segment is projected to register the highest CAGR during the forecast period.
By end user, the commercial segment is expected to hold the largest share in 2026, while the government and defense segment is projected to register the fastest growth during the forecast period.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 14.70 Billion |
| Market Size in 2026 | USD 1.86 Billion |
| Market Size in 2025 | USD 1.50 Billion |
| Revenue Growth Rate (2026–2036) | CAGR of 23.0% |
| Format | PDF, Excel & Cloud Portal · 247 pages |
| Dominating Propulsion Type | Electric Propulsion |
| Fastest Growing Propulsion Type | Hybrid Propulsion |
| Dominating Satellite Class | Microsatellites |
| Fastest Growing Satellite Class | CubeSats |
| Dominating Orbit Type | Low Earth Orbit (LEO) |
| Dominating Application | Communication |
| Fastest Growing Application | Earth Observation |
| Dominating End User | Commercial |
| Fastest Growing End User | Government & Defense |
| Dominating Geography | North America |
| Fastest Growing Geography | Asia Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
Report overview
Segments covered: propulsion type, satellite class, orbit type, application, end user.
The global small satellite propulsion market comprises the full range of propulsion systems, components, and associated integration services designed, manufactured, and qualified for deployment across small satellite platforms, including CubeSats, nanosatellites, microsatellites, and minisatellites. The market includes electric propulsion systems, such as Hall-effect thrusters, ion thrusters, electrospray thrusters, and pulsed plasma thrusters; chemical propulsion systems, including monopropellant, bipropellant, and green propellant solutions; cold gas propulsion systems; and emerging hybrid propulsion architectures.
These systems support mission-critical functions, including orbit raising from launch vehicle insertion to the designated operational orbit, station-keeping to counter atmospheric drag and solar radiation pressure, collision avoidance and conjunction management, precision attitude control, orbital transfer, and end-of-life deorbit maneuvering, which is increasingly being mandated under global space debris mitigation and orbital sustainability regulations.
The growth of the global small satellite propulsion market is primarily driven by the rapid expansion of satellite constellations for broadband connectivity, Earth observation, and national security applications, which is significantly increasing propulsion system procurement volumes.
In addition, the continued miniaturization of electric propulsion technologies is enabling efficient station-keeping, orbit-raising, collision avoidance, and end-of-life deorbiting for CubeSats, nanosatellites, and microsatellites at commercially viable cost points. The growing emphasis on regulatory compliance and orbital sustainability, particularly requirements related to controlled deorbiting and space debris mitigation, is further driving the adoption of propulsion systems across satellite classes that previously operated without dedicated propulsion capability.
However, the high development and qualification costs associated with next-generation propulsion technologies for compact satellite platforms, the technical complexity of integrating propulsion systems within stringent volume, mass, and power constraints, and supply chain limitations related to specialty propellants, precision valves, micro-thrusters, and advanced materials restrain market growth.
The increasing transition toward green propulsion systems, replacing conventional hydrazine-based monopropellants with environmentally compliant alternatives such as AF-M315E and LMP-103S, the growing adoption of multi-mode propulsion architectures that combine chemical and electric propulsion for greater mission flexibility, and the expansion of in-orbit servicing, orbital transfer, and active debris removal applications are expected to create significant growth opportunities for market players.
Furthermore, the declining cost of LEO access through rideshare and reusable launch programs, which is enabling larger and more frequent constellation deployments, is a major trend shaping the growth of this market.
Report infographic
Market dynamics
3 factors across 1 forceGreen Propellant Transition Replacing Hydrazine Across Small Satellite Propulsion Systems
The transition from hydrazine-based monopropellant systems to environmentally compliant green propellant alternatives, including AF-M315E (ASCENT) developed by L3Harris Technologies, Inc. / Aerojet Rocketdyne heritage programs, LMP-103S (HPGP) developed by ECAPS (now part of Bradford Space heritage), and nitrous oxide-based formulations, represents one of the most significant technology trends in small satellite chemical propulsion.
While hydrazine has historically offered well-established performance and extensive flight heritage, it poses substantial operational and regulatory challenges due to its toxicity and carcinogenicity, requiring specialized hazardous-material handling infrastructure at launch and integration facilities and facing increasing regulatory scrutiny across multiple jurisdictions. Green propellant systems offer approximately 12–15% higher specific impulse, along with significantly higher volumetric efficiency, while materially reducing ground handling complexity and associated fueling costs.
NASA’s Green Propellant Infusion Mission (GPIM) successfully validated AF-M315E in orbit, establishing its technical and commercial viability for next-generation satellite propulsion applications. In parallel, commercial and government small satellite operators are increasingly evaluating and adopting green propulsion solutions to improve performance, simplify launch-site operations, and align with evolving environmental and safety regulations.
Iodine and Xenon-Alternative Propellants Addressing Electric Propulsion Supply Chain Constraints
The growing adoption of alternative propellants for electric propulsion systems, mainly iodine as a substitute for xenon in Hall-effect and ion thruster applications, is helping address one of the key supply chain constraints in the small satellite propulsion market. Xenon is produced in limited quantities as a byproduct of industrial air-separation processes and remains subject to significant price volatility and potential supply shortages as electric propulsion deployment scales with mega-constellation programs and proliferated LEO architectures.
Iodine-based propulsion has emerged as a commercially viable alternative, offering higher storage density and eliminating the need for high-pressure propellant tanks that typically increase volume, mass, and integration complexity in compact satellite platforms. ThrustMe has successfully demonstrated an iodine-propelled electric thruster in orbit, with the propellant stored in solid form at room temperature, thereby enabling more efficient integration within highly constrained CubeSat and nanosatellite form factors.
In addition, alternative propellant technologies such as ionic liquid electrospray thrusters and krypton-based radio-frequency propulsion systems are further diversifying the propulsion ecosystem. These innovations are expanding electric propulsion accessibility across the full range of small satellite classes while reducing dependence on conventional noble gas supply chains and lowering total propulsion system costs.
End-of-Life Deorbit Regulations Creating Mandatory Propulsion Market Across Previously Unpropelled Satellites
The increasingly stringent global regulatory environment for orbital debris mitigation is creating a substantial new mandatory demand category for small satellite propulsion systems. Satellite classes that historically operated without onboard propulsion, particularly CubeSats and nanosatellites, are now increasingly required to demonstrate end-of-life disposal capability within defined regulatory timelines following mission completion.
A key regulatory milestone is the U.S. Federal Communications Commission’s (FCC) adoption of the five-year post-mission disposal rule for satellites operating in or passing through low Earth orbit (LEO) below 2,000 km, which replaced the earlier 25-year guideline and became effective for applicable missions from 2024 onward. In parallel, global debris mitigation frameworks, including ITU-aligned and national orbital sustainability guidelines, are progressively moving toward shorter post-mission disposal timelines.
These regulatory requirements are driving the addressable propulsion market by effectively converting previously unpropelled satellite segments into mandatory propulsion procurement opportunities. This trend is driving demand for miniaturized cold-gas, electrospray, water-based, and low-power electric propulsion systems designed for CubeSat and nanosatellite platforms.
As a result, regulatory compliance is emerging as a major driver of propulsion system adoption across the small satellite ecosystem.
Table of contents
13 chapters · 143 sections · 247 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Propulsion Type | Electric Propulsion | Hybrid propulsion |
| By Satellite Class | Microsatellites | CubeSats |
| By Orbit Type | Low Earth Orbit | — |
| By Application | Communication | Earth observation and remote sensing |
| By End-user | Commercial | Government and defense |
By Propulsion Type
- The Electric Propulsion Segment to Dominate the Global Small Satellite Propulsion Market
- The electric propulsion segment is expected to account for the largest share of around 55–60% of the global small satellite propulsion market.
- The large share of this segment is attributed to the dominant adoption of Hall‑effect and ion‑thruster systems by commercial LEO constellation operators, for whom electric propulsion’s superior specific impulse of 1,500–3,000 seconds, versus 200–300 seconds for chemical alternatives, translates directly into reduced propellant mass, lower launch cost, extended mission lifetime, and improved orbital‑slot management capability.
- SpaceX’s Starlink V2 satellites, Amazon Kuiper, and OneWeb constellation satellites all use electric propulsion for station‑keeping and collision avoidance, creating massive and sustained procurement volumes.
- However, the hybrid propulsion segment is projected to register the highest CAGR during the forecast period.
- The rapid growth of this segment is driven by the growing adoption of multi‑mode propulsion architectures that combine high‑thrust chemical systems for rapid orbit‑raising following rideshare launches with high‑efficiency electric systems for station‑keeping throughout operational life, enabling satellite operators to optimize both deployment timeline and in‑service propellant efficiency within a single propulsion platform.
By Satellite Class
- The Microsatellites Segment to Hold the Largest Share
- The microsatellites segment is expected to account for the largest share of the global small satellite propulsion market by revenue.
- This is primarily attributed to the significantly higher per-unit value of propulsion systems deployed in microsatellite platforms, which typically include advanced electric propulsion packages, such as Hall-effect thrusters, ion thrusters, and integrated propulsion modules, compared with lower-cost cold-gas and micro-propulsion systems used in CubeSats.
- In addition, microsatellites continue to be the preferred platform for high-capacity LEO communication, Earth observation, and defense constellation nodes, thereby driving substantial propulsion system procurement volumes.
- However, the CubeSats segment is projected to register the highest CAGR during the forecast period.
- The rapid growth of this segment is primarily driven by the sharp increase in CubeSat deployment volumes across commercial, academic, and defense applications, the growing regulatory requirement for end-of-life deorbit capability in previously unpropelled missions, and the continued miniaturization of electrospray, iodine-based ion thrusters, cold-gas systems, and other compact propulsion technologies into 1U- and 3U-compatible form factors.
- These developments are making propulsion systems increasingly commercially accessible to the full spectrum of CubeSat operators, including universities, emerging space startups, and defense technology demonstrator programs.
By Orbit Type
- Low Earth Orbit to Account for the Largest Share
- The LEO segment is expected to account for the largest share of the global small satellite propulsion market, indicating the dominant role of LEO constellation deployments in driving small satellite propulsion procurement volumes.
- LEO satellites experience atmospheric drag that requires continuous station‑keeping thrust, creating ongoing propulsion demand throughout the operational lifetime rather than a one‑time orbit‑raising requirement, and the collision‑avoidance maneuvering requirements of increasingly congested LEO orbital shells represent a growing propulsion duty cycle per satellite.
By Application
- The Communication Segment to Hold the Largest Share
- The communication segment is expected to account for the largest share of the global small satellite propulsion market.
- The leading share of this segment is primarily attributed to the large-scale deployment of LEO broadband communication constellations, including Space Exploration Technologies Corp. Starlink, Amazon Project Kuiper, Eutelsat OneWeb, and Telesat Lightspeed, which continue to represent the primary volume driver for propulsion system procurement.
- These mega-constellation programs collectively comprise thousands of propulsion-equipped satellites and are expected to generate substantial propulsion hardware demand throughout the forecast period.
- However, the earth observation and remote sensing segment is projected to register the highest CAGR during the forecast period.
- The strong growth of this segment is primarily driven by the growing deployment of Earth observation constellations by Planet Labs PBC, ICEYE Oy, Satellogic Inc., BlackSky Technology Inc., and various government-sponsored space programs.
- These deployments require advanced propulsion systems for precise orbit maintenance, orbital plane adjustments, rapid retasking, station-keeping, and collision avoidance in increasingly congested observation orbital shells, thereby driving robust market growth in this segment.
By End-user
- The Commercial Segment to Hold the Largest Share
- The commercial segment is expected to account for the largest share of the global small satellite propulsion market.
- The segment’s leading share is primarily attributed to the dominant role of commercial LEO constellation operators as the largest volume procurers of small satellite propulsion hardware globally.
- This segment includes broadband connectivity operators, Earth observation and geospatial data companies, maritime and aviation tracking service providers, and IoT connectivity platform providers, all of which are deploying propulsion-equipped small satellites at unprecedented commercial scale.
- However, the government and defense segment is projected to register the highest CAGR during the forecast period.
- The robust growth of this segment is driven by accelerating national investments in proliferated LEO satellite architectures for defense surveillance, secure strategic communications, missile warning, and space situational awareness applications, all of which require highly maneuverable, propulsion-equipped small satellites to support responsive space operations.
- In addition, increasing investments in in-orbit servicing, orbital transfer, and active debris removal missions are expected to further drive demand for advanced small satellite propulsion systems in this segment.
Geographic analysis
North America
Largest shareIn 2026, North America is expected to account for the largest share of the global small satellite propulsion market. The region’s dominant position is primarily supported by the high concentration of small satellite operators, constellation developers, and launch-service providers, including Space Exploration Technologies Corp., Amazon, Planet Labs PBC, and a large ecosystem of emerging commercial space companies. In addition, the presence of leading propulsion technology providers, such as L3Harris Technologies, Inc. / Aerojet Rocketdyne heritage programs, Moog Inc., Busek Co. Inc., and Phase Four, Inc., combined with strong procurement from NASA, the U.S. Space Force, DARPA, and the National Reconnaissance Office, continues to support regional market leadership. Furthermore, the U.S. FCC’s five-year post-mission disposal mandate is driving additional regulatory-led propulsion demand across the domestic commercial satellite ecosystem, sustaining North America’s leading share through the forecast period.
Asia-Pacific
Fastest growthHowever, the Asia Pacific small satellite propulsion market is projected to register the highest CAGR during the forecast period. The strong growth of this region is primarily driven by China’s accelerated domestic small satellite constellation buildout, including the Guowang and other national broadband and Earth observation programs, India’s liberalized space policy framework that is enabling rapid private-sector participation, and Japan and South Korea’s expanding investments in national and commercial LEO satellite initiatives. In addition, the emergence of indigenous propulsion technology companies, such as Bellatrix Aerospace in India, is strengthening regional manufacturing capabilities and reducing reliance on foreign supply chains. These concurrent national and commercial initiatives are expected to drive the fastest regional growth in the Asia Pacific small satellite propulsion market between 2026 and 2036.
Competitive landscape
- ThrustMe SAS · France
- Phase Four, Inc. (U.S.)
- ENPULSION GmbH · Austria
- Inc.’s Sinclair Interplanetary heritage
Frequently asked questions
The global small satellite propulsion market is expected to reach USD 14.70 billion by 2036 from an estimated USD 1.86 billion in 2026, at a CAGR of 23.0% during the forecast period 2026–2036.
Cite this report
Meticulous Research. (2026). Small Satellite Propulsion Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MR-1872). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/small-satellite-propulsion-market-6555