Radiation Dose Management Market (2022-2029)
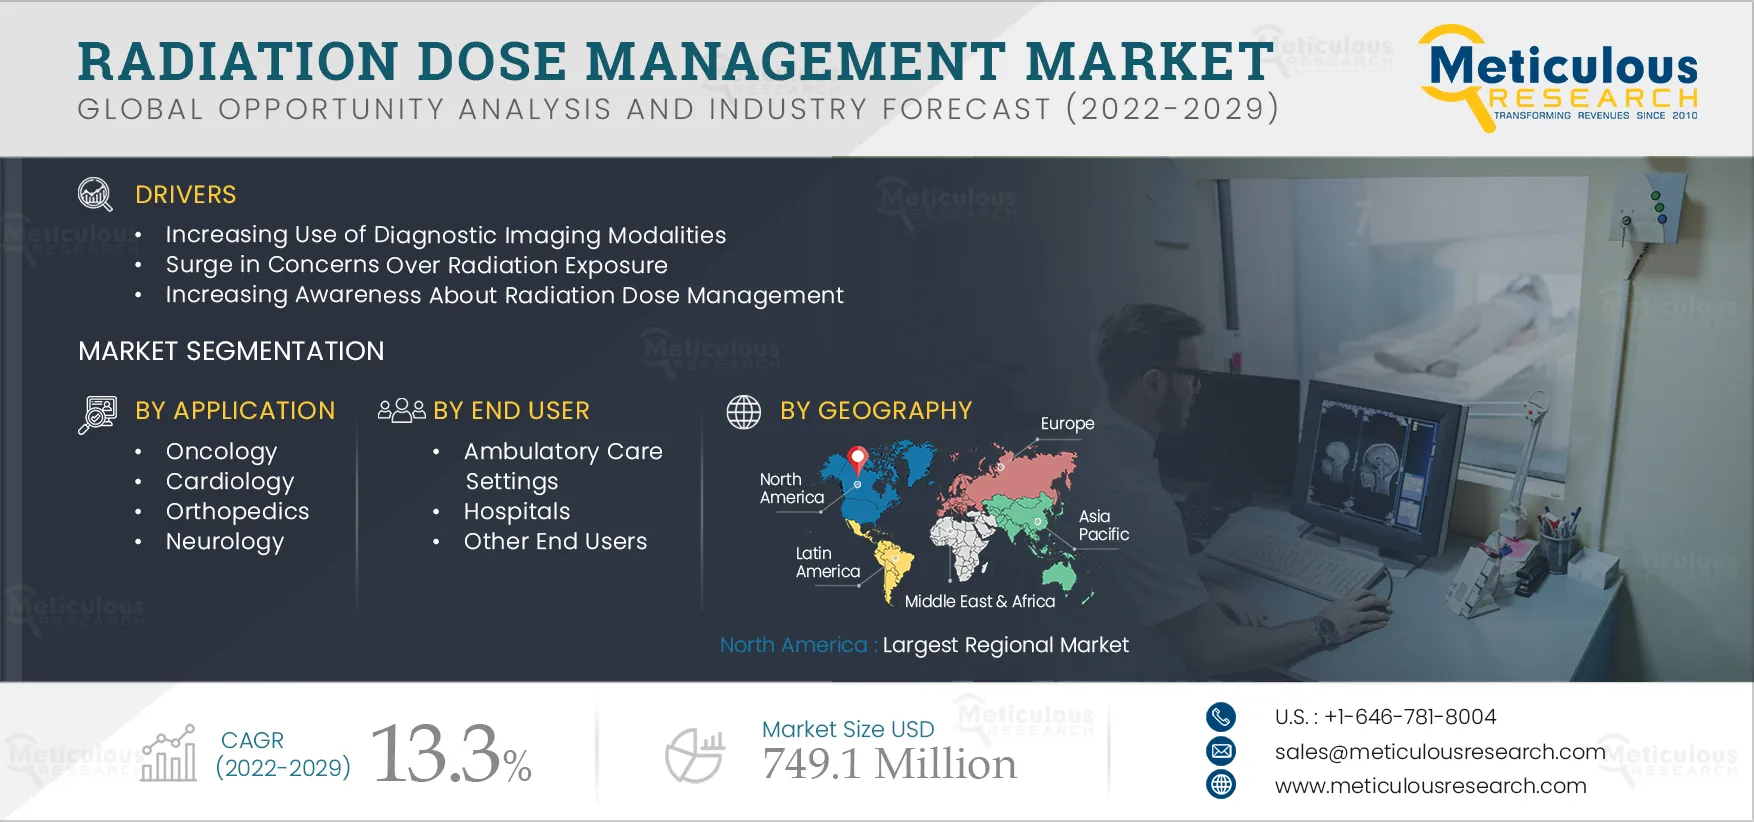
The Radiation Dose Management Market is projected to reach $749.1 million by 2029, at a CAGR of 13.3% from 2022 to 2029.
- Published
- Nov 2022
- Pages
- 190
- Format
- PDF + Excel
- Report ID
- MR-710
- Base year
- 2021
- 2029 · FORECAST
- $749.1M
- 2029
- $749.1M
- CAGR 2022–2029
- 13.3%
2021 baseline · 2022–2029 forecast at 13.3% CAGR · hover a bar for the value
Key highlights
Based on Offering, in 2022, the Solutions Segment is Expected to Account for the Largest Share of the Market
Based on Modality, in 2022, the Computed Topography Segment is Expected to Account for the Largest Share of the Market
Based on Application, in 2022, the Oncology Segment is Expected to Account for the Largest Share of the Market
Based on End user, in 2022, the Hospitals Segment is Expected to Account for the Largest Share of the Market
Report summary
| Particulars | Details |
|---|---|
| Base Year | 2021 |
| Estimated Year | 2022 |
| Forecast Period | 2022–2029 |
| Market Size (2029) | USD 749.1 million |
| CAGR (2022–2029) | 13.3% |
| Format | PDF, Excel & Cloud Portal · 190 pages |
| Segments Covered | By Offering: Solutions, Services · By Modality: Computed Tomography, Fluoroscopy and Interventional Imaging, Nuclear Medicine, Radiography and Mammography · By Application: Oncology, Cardiology, Orthopedics, Neurology · By End User: Ambulatory Care Settings, Hospitals · By Solution & Service |
| Countries Covered | Europe (RoE), Asia-Pacific (RoAPAC), Latin America (RoLATAM) |
| Key Companies | Bayer AG, Siemens Healthineers GmbH, Novarad Corporation, PACSHealth, LLC, Koninklijke Philips N.V., Qaelum N.V., Sectra AB, Canon Inc., Volpara Health Limited |
Report overview
Segments covered: offering, modality, application, end user, solution & service. Regions: Europe, Asia-Pacific, Latin America.
Dose management systems are used for monitoring patient exposure to ionization emission, optimization, compliance with diagnostic reference levels, and quality assurance. Dose management systems support the tasks and duties of radiation protection in accordance with local and national requirements. They support radiographers, medical practitioners, medical physics experts (MPE) and other health professionals involved in imaging.
During the initial phase of the pandemic, several countries postponed non-urgent diagnostic imaging surgeries. Considering the contagious nature of the disease, the usage of imaging equipment on COVID-19 patients posed a serious hazard for other patients and healthcare providers. There was an abrupt decline in demand for imaging services. Additionally, in the U.S., the Centers for Disease Control and Prevention and the American College of Radiology recommend using alternative techniques to diagnose COVID-19 rather than the routine use of chest radiographs or CT scans. This temporarily negatively impacted the market.
However, there was a surge in diagnostic imaging after the first phase of the lockdown. For example, in Australia, there was a significant decrease in total imaging services performed from March to May 2020. Later, a significant increase was observed in nuclear medicine and CT services post-June 2020. Thus, radiology volumes were dependent on the stage/period of lockdown, location, and imaging modality. The market is recovering from the negative impact of COVID-19, and the demand for medical imaging is further expected to rise.
Market dynamics
2 factors across 2 forcesIncreasing Use of Diagnostic Imaging Modalities is Driving the Market Growth
Physicians are using diagnostic medical modalities to diagnose and treat diseases. They rely on these modalities for various reasons, such as increased patient inflow and advancements in diagnostic imaging. Also, there has been a surge in the burden of chronic diseases. The prevalence of cancer, cardiac, and orthopedic diseases is increasing due to various factors which require imaging modalities for diagnosis. For example, according to International Agency for Research on Cancer (IARC), in 2020, there were 2.3 million women diagnosed with breast cancer, with 685,000 deaths globally. Between 2015 and 2020, there were 7.8 million women diagnosed with breast cancer. The incidence of breast cancer is estimated to reach 2.74 million cases by 2030.
Table of contents
12 chapters · 89 sections · 190 pages · click to expandSegmental analysis
| Segment | Largest share (2022) | Fastest growth (2022–2029) |
|---|---|---|
| By Offering | Solutions | — |
| By Modality | Computed Topography | — |
| By Application | Oncology | — |
| By End User | Hospitals | — |
By Offering
- The Solutions Segment is Expected to Account for the Largest Share of the Market
- Increased awareness and regulations for ionizing radiation contributed to the large market share of the solutions segment.
- The U.S. Joint Commission, which accredits and certifies more than 22,000 hospitals and healthcare organizations in the country , has introduced new standards effective from July 2022.
- As per the new regulations, hospitals are required to establish stricter radiation dose management processes.
- Furthermore, with the approval of the National Electrical Manufacturers Association's Medical Imaging & Technology Alliance (MITA) Smart Dose, MITA has continued its efforts on dose reduction.
- MITA Smart Dose is a standard that offers healthcare providers an additional tool to optimize and manage doses in CT scanning.
By Modality
- The Computed Topography Segment is Expected to Account for the Largest Share of the Market
- The computed tomography segment is expected to account for the largest share of the radiation dose management market.
- The large market share of this segment is attributed to the increased early disease diagnosis, a rise in the prevalence of targeted diseases, and the preference for non-invasive diagnostic procedures owing to a surge in computed tomography examinations.
By Application
- The oncology segment is expected to account for the largest share of the market.
- The large market share of this segment is attributed to the increasing burden of cancer and increased usage of imaging modalities in oncology.
- As per the American Cancer Society, in 2021, 1.9 million new cancer cases and 608,570 deaths due to cancer were recorded in the U.S. Furthermore, according to the International Agency for Research on Cancer (IARC), in 2018, globally, there were 18.1 million cancer cases compared to 19.3 million in 2020.
- In March 2021, the World Health Organization (WHO) introduced a Global Breast Cancer Initiative which aims to reduce global breast mortality by 2.5% by 2040.
- The initiative aims to reduce 2.5 million deaths globally, especially in low-income countries where more efforts are needed to tackle the disease.
- In October 2021, The Breast Cancer Research Foundation (BCRF) announced funding of USD 47.5 million in breast cancer research.
- This funding will support 250 scientists at leading academic and medical institutions across 14 countries worldwide.
- The funding will be used to study the entire cancer spectrum, from the basic biology of a cancer cell to developing innovative treatments and improving quality of life.
By End User
- The Hospitals Segment is Expected to Account for the Largest Share of the Market
- The large market share of the hospitals segment is attributed to the rising prevalence of chronic diseases, the increasing patient population, increased awareness about early diagnosis, and technological advancements in imaging modalities.
- The prevalence of chronic diseases has substantially increased over the period.
- Hospitals are the most preferred healthcare settings for diagnosis and therapy, which supports the large market share of this segment.
Geographic analysis
North America
Largest shareThe large share of this market is attributed to factors such as advanced healthcare infrastructure, technological advancements, high awareness related to radiation exposure, and strict accreditation & regulatory requirements related to radiation exposure. According to American Cancer Society Recommendations for the Early Detection of Cancer, women between the age of 40-54 should undergo regular screening mammography starting at age 45. Additionally, U.S. healthcare expenditure increased from USD 2,658 Billion in 2009 to USD 3,795 Billion in 2019. These factors have contributed significantly to the large market share of the region. North America: Largest Regional Market
Competitive landscape
- Bayer AG
- Siemens Healthineers GmbH
- Novarad Corporation
- PACSHealth, LLC
- Koninklijke Philips N.V.
- Qaelum N.V.
- Sectra AB
- Canon Inc.
- Volpara Health Limited
Frequently asked questions
This study offers a detailed assessment of the radiation dose management market, including the market size & forecast for various segmentations such as offering, modality, application, and end user. The radiation dose management market studied in this report also consists of the value analysis of various segments and sub-segments of radiation dose management at regional and country levels.
Cite this report
Meticulous Research. (2022). Radiation Dose Management Market - Global Opportunity Analysis and Industry Forecast (2022-2029) (Report No. MR-710). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/reports/radiation-dose-management-market-5394