Pain Management Devices Market (2025-2032)
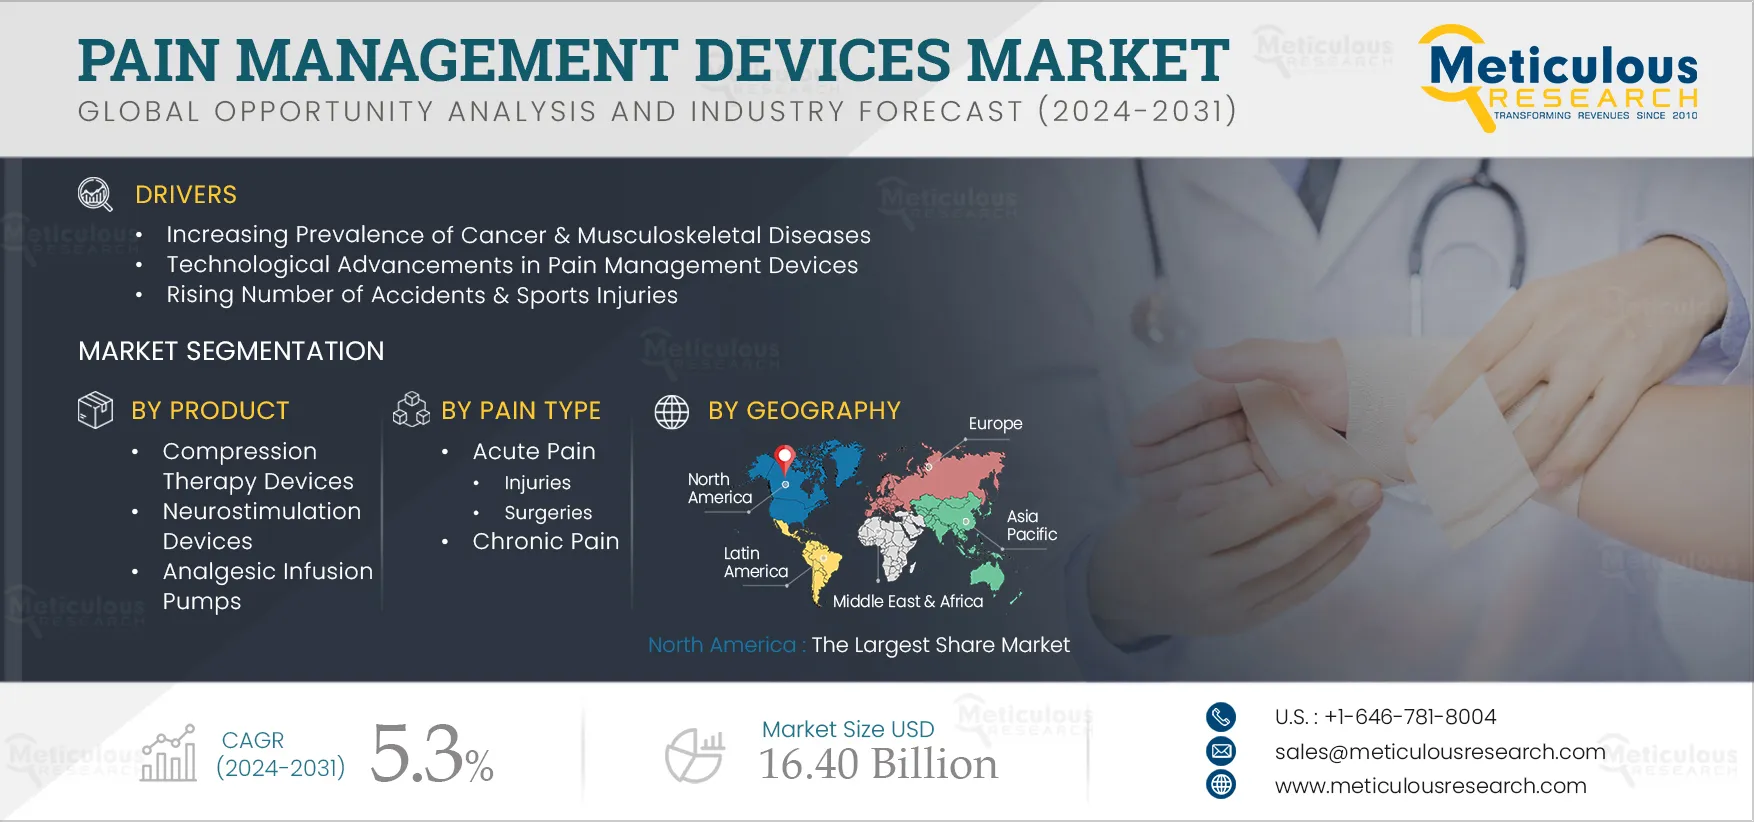
The Pain Management Devices Market is expected to reach $16.40 billion by 2032, at a CAGR of 5.3% from 2025 to 2032.
- Published
- Jun 2024
- Pages
- 280
- Format
- PDF + Excel
- Report ID
- MRHC - 1041238
- Base year
- 2024
- 2032 · FORECAST
- $16.40B
- 2032
- $16.40B
- CAGR 2025–2032
- 5.3%
2024 baseline · 2025–2032 forecast at 5.3% CAGR · hover a bar for the value
Key highlights
By Product: The Compression Therapy Devices Segment to Dominate the Pain Management Devices Market in 2025
By Portability: The Wearable & Implantable Segment to Dominate the Pain Management Devices Market in 2025
By Pain Type: The Chronic Pain Segment to Dominate the Pain Management Devices Market in 2025
By Distribution Channel: The Retail Pharmacies Segment to Dominate the Pain Management Devices Market in 2025
By End User: The Hospitals & Clinics Segment to Dominate the Pain Management Devices Market in 2025
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 280 |
| Format | |
| Forecast Period | 2025–2032 |
| Base Year | 2024 |
| CAGR (Value) | 5.3% |
| Market Size (Value) | $16.40 Billion by 2032 |
| Segments Covered | By Product · Compression Therapy Devices · Bandages · Garments · Stockings · Socks & Sleeves · Wraps & Tapes · Other Garments · Intermittent/Sequential Pneumatic Compression Pumps · Other Pressure Pumps · Neurostimulation Devices · Deep Brain Stimulation (DBS) Systems · Spinal Cord Stimulation Systems · Transcutaneous Electrical Nerve Stimulation (TENS) Systems · Vagus Nerve Stimulation (VNS) Systems · Other Neurostimulation Devices · Analgesic Infusion Pumps · Intrathecal Infusion Pumps · External Infusion Pumps · Electrotherapy Devices · Ablation Devices · Accessories · (Note 1: Other pressure pumps include calibrated, non-calibrated, and portable pressure pumps.) · (Note 2: Other neurostimulation devices include Responsive Neurostimulation Systems (RNS), Sacral Nerve Stimulation (SNS) Systems, and syringe devices.) · (Note 3: Other garments include inflatable devices, liners, bands, belts, braces, and tubes.) · By Portability · Stationary/Benchtop · Wearable & Implantable · By Pain Type · Acute Pain · Injuries · Surgeries · Chronic Pain · Musculoskeletal Pain · Neuropathic Pain · Cancer Pain · Other Chronic Pain Types · (Note: Other chronic pain types include nociceptive pain, migraine, and carpal tunnel syndrome.) · By Distribution Channel · Hospital Pharmacies · Retail Pharmacies · Online/E-commerce Platforms · By End User · Hospitals & Clinics · Ambulatory Surgical Centers · Physiotherapy Centers · Home Care Settings · Other End Users · (Note: Other end users include rehabilitation centers and sports medicine centers.) |
| Countries Covered | North America (U.S. and Canada), Europe (Germany, France, Italy, U.K., Spain, Switzerland, and Rest of Europe), Asia–Pacific (India, China, Japan, Australia, South Korea, and Rest of Asia–Pacific), Latin America (Brazil, Mexico, and Rest of Latin America), and the Middle East & Africa |
| Key Companies Profiled | Abbott Laboratories (U.S.), Becton, Dickinson and Company (U.S.), Boston Scientific Corporation (U.S.), Johnson & Johnson Services, Inc. (U.S.), Baxter International, Inc. (U.S.), VirpaxPharmaceuticals, Inc. (U.S.), B. Braun Melsungen AG (Germany), Medtronic plc (Ireland), Rusan Pharma Ltd (India), Grünenthal GmbH (Germany), OMRON Healthcare, Inc. (U.S.), and Nevro Corp. (U.S.). |
Report overview
Segments covered: product, pain type, distribution, end user. Regions: North America, Europe, Latin America.
The growth of the pain management devices market is primarily driven by the rising number of chronic pain cases associated with the geriatric population, the increasing number of surgical procedures, the increasing prevalence of cancer & musculoskeletal diseases, technological advancements in pain management devices, increasing healthcare expenditures, and the increasing number of sports & accident injuries.
Moreover, partnerships & collaborations by pain management device companies, the integration of digital health technologies into pain management devices, and emerging economies are expected to offer market growth opportunities.
Report infographic
Market dynamics
5 factors across 3 forcesIncreasing Prevalence of Cancer & Musculoskeletal Diseases
The incidence of cancer is rising across the world. According to the World Health Organization (WHO), in 2022, 20 million people were diagnosed with cancer globally. This number is projected to reach 35 million in 2050. Moreover, according to data published by the World Health Organization (WHO) in February 2022, cancer is the most common cause of mortality. In 2020, it accounted for approximately 10 million deaths worldwide. Lung cancer, breast cancer, colon cancer, prostate cancer, and rectum cancer are some of the most common types of cancer.
Furthermore, according to the WHO, in 2022, 1.71 billion people were affected by musculoskeletal conditions, including osteoarthritis, osteoporosis, fragility fractures, and rheumatoid arthritis globally. According to the State of Musculoskeletal Health (MSK), in 2021, 20.3 million individuals in the U.K. (32% of the population) had musculoskeletal conditions such as back pain and arthritis, of which 2.8 million people were aged under 35, 10.2 million people were aged between 35–64, and 7.4 million people were aged 65 or above.
Thus, the increasing prevalence of cancer & musculoskeletal diseases is boosting the demand for pain management devices, driving the growth of this market.
Technological Advancements in Pain Management Devices
Technological advancements in pain management devices have led to their increased adoption among patients. There have been significant advancements in neurostimulation devices, including Peripheral Nerve Stimulators (PNS) and Spinal Cord Stimulators (SCS). These devices send electric impulses to specific nerves that modulate pain signals and provide relief. Recent advancements have led to the introduction of more compact, implantable neurostimulation devices with increased programming possibilities that are also comfortable for patients.
Furthermore, technological advances have enhanced medicine delivery techniques for pain relief and management. Implantable drug delivery systems, such as intrathecal pumps, can quickly deliver pain drugs to the spinal cord and other specific locations, improving pain management and reducing the need for systemic opioids. These systems have longer battery life, provide better flexibility, come in smaller sizes, and offer more security features. These benefits support their adoption, driving the growth of the pain management devices market.
Table of contents
13 chapters · 131 sections · 280 pages · click to expandSegmental analysis
| Segment | Largest share (2025) | Fastest growth (2025–2032) |
|---|---|---|
| By Product | Compression Therapy Devices | — |
| By Portability | Wearable & Implantable | — |
| By Pain Type | Chronic Pain | — |
| By Distribution Channel | Retail Pharmacies | — |
| By End User | Hospitals & Clinics | Home care settings |
By Product
- The compression therapy devices segment is expected to account for the largest share of 28.1% of the pain management devices market.
- The compression therapy devices segment is further segmented into bandages, garments, intermittent/sequential pneumatic compression pumps, and other pressure pumps.
- The large market share of this segment can be attributed to the increasing number of orthopedic procedures and the rising global geriatric population, which is highly susceptible to improper blood flow, edema, and vein problems like varicose veins, spider veins, and leg ulcers.
- Additionally, the increased demand for compression therapy garments among healthcare professionals and the general population for long-term treatment options contributes to the segment’s large market share.
- Owing to the rising demand for compression therapy devices, companies operating in this market are focusing on the introduction of innovative offerings.
- For instance, in September 2024, AIROS Medical, Inc. (U.S.) launched the AIROS 6P sequential compression device and pants-like compression garments to treat abdominal, pelvic, and leg swelling.
By Portability
- The wearable & implantable segment is expected to account for the larger share of the pain management devices market.
- The large market share of this segment can be attributed to technological advancements in wearable & implantable pain management devices and the benefits offered by these devices, such as the ability to track muscle activity, provide real-time feedback, monitor changes, and register pain and stress signals.
By Pain Type
- The Chronic Pain Segment to Dominate the Pain Management Devices Market in 2025
- The chronic pain segment is expected to account for the larger share of the pain management devices market.
- The large market share of this segment can be attributed to the increasing cases of musculoskeletal diseases.
- For instance, according to the Australian Institute of Health and Welfare (AIHW), chronic musculoskeletal disorders affect nearly one-third of all Australians.
- Nearly 3.1 million people in Australia had arthritis, 6.9 million had back problems, and 889,000 had osteoporosis.
By Distribution Channel
- The retail pharmacies segment is expected to account for the largest share of the pain management devices market.
- The large market share of this segment can be attributed to the availability of a diverse selection of pain management devices, such as compression therapy devices, including bandages, garments, and intermittent/sequential pneumatic compression pumps at retail pharmacies, which enables patients to select the best pain management options depending on their specific preferences, needs, and healthcare expert recommendations.
By End User
- The hospitals & clinics segment is expected to account for the largest share of 39.0% of the pain management devices market.
- The large market share of this segment can be attributed to the growing number of patient visits to hospitals & clinics for pain management and surgical procedures, the presence of highly skilled healthcare professionals, ease of access, increasing healthcare expenditures, improving hospital infrastructure in emerging economies, and the increasing adoption of pain management devices among hospitals & clinics.
- However, the home care settings segment is expected to register the highest CAGR of 6.3% during the forecast period.
- The growth of this segment is driven by the rising demand for pain management devices in home care settings due to the growing global geriatric population with musculoskeletal and neuropathic pain.
Geographic analysis
North America
Largest shareIn 2025, North America is expected to account for the largest share of 30.7% of the pain management devices market, followed by Europe and Asia-Pacific. North America’s significant market share can be attributed to the presence of major pain management device manufacturers such as Becton, Dickinson and Company (U.S.) and Boston Scientific Corporation (U.S.), increasing healthcare expenditure, the growing prevalence of cancer & musculoskeletal diseases and technological advancements in pain management devices.
Asia-Pacific
Fastest growthHowever, Asia-Pacific is slated to register the highest growth rate of 6.7% during the forecast period. The growth of this regional market is driven by the rising awareness regarding pain management in countries such as China and India, increasing healthcare spending, and the growing number of accidents and sports injuries.
Competitive landscape
- April 2025
Medtronic plc (U.S.) received the U.S. Food and Drug Administration (FDA) approval for its Inceptiv closed-loop rechargeable Spinal Cord Stimulator (SCS) for the treatment of chronic pain.
- April 2025
AtriCure, Inc. (U.S.) launched the cryoSPHERE+ Probe for post-operative pain management.
- December 2022
Abbott Laboratories (U.S.) received the U.S. Food and Drug Administration (FDA) approval for the Eterna Spinal Cord Stimulation (SCS) system for the treatment of chronic pain.
- Abbott Laboratories (U.S.)
- Becton
- Dickinson and Company (U.S.)
- Boston Scientific Corporation (U.S.)
- Johnson & Johnson Services, Inc. (U.S.)
- Baxter International, Inc. (U.S.)
- VirpaxPharmaceuticals, Inc. (U.S.)
- B. Braun Melsungen AG · Germany
- Medtronic plc · Ireland
- Rusan Pharma Ltd · India
- Grünenthal GmbH · Germany
- OMRON Healthcare, Inc. (U.S.)
- Nevro Corp. (U.S.)
Frequently asked questions
The Pain Management Devices Market offers various devices to alleviate pain from chronic conditions, surgeries, and injuries through technological innovations and therapies.
Cite this report
Meticulous Research. (2024). Pain Management Devices Market - Global Opportunity Analysis and Industry Forecast (2025-2032) (Report No. MRHC - 1041238). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/pain-management-devices-market-5921