Mental Health Apps Market (2025-2032)
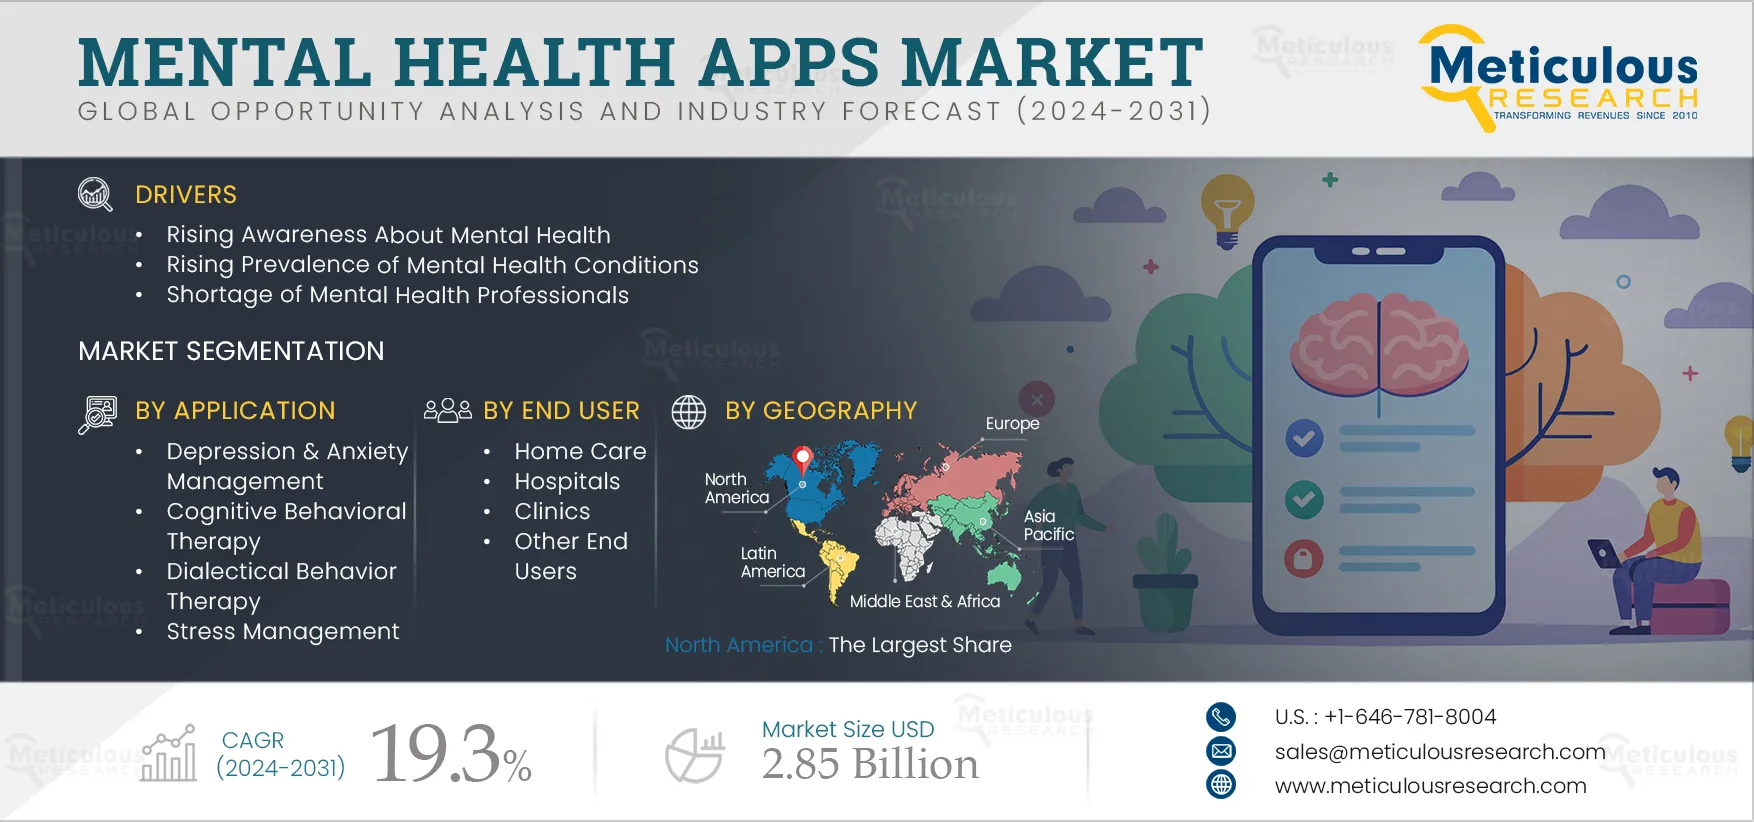
The Mental Health Apps Market was valued at $0.7 billion in 2024. This market is expected to reach $2.85 billion by 2032, from an estimated $0.83 billion in 2025, at a CAGR of 19.3% during the forecast period 2025-2032. Mental Health Apps Market Size & Forecast The growth of this market is driven
- Published
- May 2024
- Pages
- 260
- Format
- PDF + Excel
- Report ID
- MR-1170
- Base year
- 2024
- 2024 · BASELINE
- $700.0M
- 2032
- $2.85B
- CAGR 2025–2032
- 19.3%
2024 baseline · 2025–2032 forecast at 19.3% CAGR · hover a bar for the value
Key highlights
By Platform: In 2025, the Android Segment to Dominate the Mental Health Apps Market
By Application: In 2025, the Depression & Anxiety Management Segment to Dominate the Mental health Apps Market
By Patient Type: In 2025, the Adults Segment to Dominate the Mental Health Apps Market
By End User: In 2025, the Home Care Segment to Dominate the Mental Health Apps Market
Report summary
| Particulars | Details |
|---|---|
| Page No | 260 |
| Format | |
| Forecast Period | 2025-2032 |
| Base Year | 2024 |
| CAGR | 19.3% |
| Market Size (Value) | $2.85 billion by 2032 |
| Segments Covered | By Platform · Android · iOS · Other Platforms · (Note: Other Platforms include Windows, Java, Linux, and Symbian) · By Application · Depression & Anxiety Management · Cognitive Behavioral Therapy · Dialectical Behavior Therapy · Meditation Management · Stress Management · Other Applications · (Note: Other Applications include Addiction, OCD, and Panic Attacks) · By Patient Type · Adults · Children · Older Adults · By End User · Home Care · Hospitals · Clinics · Other End Users · (Note: Other End Users include Therapy Centers, Rehabilitation Centers, Government Institutes, Research Centers, and Corporate Offices) |
| Countries Covered | North America (U.S., Canada), Europe (Germany, France, U.K., Spain, Italy, Sweden, Denmark, Belgium, Rest of Europe), Asia-Pacific (China, Japan, India, Australia, New Zealand, Rest of APAC), Latin America (Brazil, Mexico, Rest of Latin America), and the Middle East & Africa |
| Key Companies | Talkspace, Inc. (U.S.), BetterHelp (U.S.), Headspace Inc. (U.S.), Sanvello Health, Inc. (U.S.), ReachOut Australia (Australia), Calm.com, Inc. (U.S.), Twill Inc. (U.S.), Worry Watch (U.S.), Jade Lizard Software LLC (U.S.), Insight Network Inc. (U.S.), Aura Health (U.S.), MoodMission Pty Ltd (Australia), and Youper Inc. (U.S.). |
Report overview
Segments covered: platform. Regions: North America, Europe, Asia-Pacific, Latin America.
The growth of this market is driven by factors such as the increasing prevalence of mental illnesses, rising accessibility to the Internet, the growing number of smartphone users, a shortage of mental health professionals, and the rising awareness about mental health, driven by favorable public & private initiatives. Furthermore, the increasing popularity of digital therapeutics and the high level of personalization offered by mental health apps are expected to create market growth opportunities.
Gamification of Mental Health Apps
Gamification involves integrating game-like elements, mechanics, and design principles into mental health apps to enhance user engagement and motivation. In mental health apps, gamification techniques can include:
Challenges and Goals: Users are presented with challenges or goals related to their mental health, such as completing a certain number of mindfulness exercises or achieving specific mood-tracking targets.
Progress Tracking: Apps may use progress bars, levels, or badges to visually represent users' progress and accomplishments, providing a sense of achievement and motivation to continue engaging with the app.
Rewards and Incentives
Users may earn virtual rewards, points, or virtual currency for completing tasks or reaching milestones within the app. These rewards can be used to unlock additional features, content, or customization options.
By integrating gamification elements, mental health applications aim to make the process of managing mental well-being more enjoyable, engaging, and sustainable for users. Gamification can help increase user retention, adherence to treatment plans, and the overall effectiveness of mental health interventions.
Market dynamics
4 factors across 3 forcesIncreasing Prevalence of Mental Illnesses
According to the World Health Organization, mental health illnesses are on the rise globally, with common conditions including anxiety, clinical depression, and bipolar disorder. These issues can stem from various factors, including individual, family, community, and structural influences. Risk factors may include adverse childhood experiences, biological predispositions, stressful life events, and the presence of long-term physical conditions.
Moreover, the COVID-19 pandemic has exacerbated the prevalence of mental illness. Measures such as social distancing, isolation, and disruptions to daily life, including school and workplace closures, have led to feelings of purposelessness and heightened anxiety about the state of the world. Many individuals, even those with previously robust mental health, have experienced challenges such as depression, stress, and anxiety during the pandemic, with lingering effects continuing to affect individuals today.
According to the WHO, approximately 1 billion people globally are living with mental, neurological, and substance use disorders. Additionally, in 2022, 23.1% of people in the U.S. experienced a mental health condition (Source: Substance Abuse and Mental Health Services Administration, U.S.). Furthermore, in India, an estimated 60-70 million people suffer from common and severe mental disorders (source: WHO).
Furthermore, a study published in The Lancet Psychiatry suggests that nearly half of the world's population may develop at least one type of mental disorder by the age of 75. This growing prevalence of mental disorders, coupled with increasing awareness of treatment and management options, is expected to drive the adoption of mental health apps for treatment and management purposes.
Rising Awareness About Mental Health, Driven by Favorable Public & Private Initiatives
Global initiatives are underway to raise awareness of mental health issues and improve access to mental health care and treatment. Governments and public organizations around the world are implementing various efforts to enhance access to mental health services. Some of these initiatives include:
-
In October 2022, the government of India Launched the National Tele Mental Health Programme to improve access to quality mental health counseling and care services in the country.
- In 2019, the WHO Mental Health Action Plan 2013-2020 was extended to the year 2032 by the Seventy-second World Health Assembly. The aim of this action plan is mental health and well-being for all, to prevent mental health conditions for those at risk, and to achieve universal coverage for mental health services.
Such initiatives are expected to raise awareness and access to mental health care. This growing awareness is expected to ultimately drive the growth of the mental health apps market.
Table of contents
12 chapters · 106 sections · 260 pages · click to expandSegmental analysis
| Segment | Largest share (2025) | Fastest growth (2025–2032) |
|---|---|---|
| By Platform | Android | IOS |
| By Application | Depression & Anxiety Management | Meditation management |
| By Patient Type | Adults | Adults |
| By End User | Home Care | Home care |
By Platform
- The Android Segment to Dominate the Mental Health Apps Market
- The Android segment is expected to account for the largest share of 64.0% of the mental health apps market.
- This segment’s large market share can be attributed to the significantly larger number of Android users globally compared to iOS users.
- Additionally, the faster approval process of apps on Google Play Store compared to Apple’s App Store and the comparatively lower subscription rates for Android apps contribute to the growth of this segment.
- However, the iOS segment is projected to witness the highest growth rate of 22.6% during the forecast period of 2025–2032.
- The growth of this segment is driven by the increasing number of iPhone users worldwide.
- For instance, in the first quarter of 2025, Apple Inc. (U.S.) reported a revenue increase from iPhone sales, reaching USD 69.7 billion, compared to USD 61.57 billion in the first quarter of 2018 (Source: Business of Apps).
By Application
- The depression & anxiety management segment is expected to account for the largest share of 44.7% of the mental health apps market.
- This segment's large market share is attributed to the high prevalence of depression and anxiety worldwide.
- There has been an increase in depression and anxiety, with approximately 280 million people affected globally (Source: WHO).
- This rise can be attributed to various factors, including social, psychological, and biological influences.
- However, the meditation management segment is projected to register the highest CAGR of 20.4% during the forecast period of 2025-2032.
- This growth can be attributed to the increasing popularity of meditation apps, driven by the growing need to prevent and manage mental illnesses at early stages.
- Moreover, the rising scientific research conducted to support the importance of meditation for mental well-being is expected to further propel the growth of this segment.
By Patient Type
- The Adults Segment to Dominate the Mental Health Apps Market
- The adults segment is expected to account for the largest share of the mental health apps market.
- This segment’s large market share can be attributed to the high incidence of mental illness in adults, which can stem from various factors, including social, psychological, and biological influences.
- Furthermore, the increasing awareness of mental health issues and the decreasing stigma surrounding mental health in developed countries contribute to the large market share of this segment.
- Moreover, the adults segment is projected to register the highest CAGR during the forecast period.
By End User
- The Home Care Segment to Dominate the Mental Health Apps Market
- The home care segment is expected to account for the largest share of the market.
- This segment’s large market share can be attributed to the growing awareness of mental health issues and the benefits offered by mental health apps.
- These apps offer therapeutic tasks and therapies that can be completed at home, providing comfort and familiarity to individuals with mental illnesses.
- Moreover, the home care segment is projected to register the highest CAGR during the forecast period.
- The growth of this segment can be attributed to the confidentiality provided by health apps and the sense of safety and security provided by home environments in managing mental illness.
Geographic analysis
North America
Largest shareIn 2025, North America is expected to account for the largest share of 37.2% of the mental health apps market. Moreover, in 2025, the U.S. is expected to account for the larger share of the mental health apps market in North America. This significant market share can be attributed to the widespread adoption of mental health apps in the U.S., driven by the high prevalence of mental health issues, high awareness regarding mental health conditions, and the increased adoption of digital health technologies.
Asia-Pacific
Fastest growthHowever, the market in Asia-Pacific is projected to register the highest CAGR of 20.5% during the forecast period. The growth of this regional market can be attributed to supportive government initiatives aimed at promoting mental well-being, a gradual increase in awareness of mental health issues, and rising disposable incomes in the region. Several mental health apps are being launched in Asia-Pacific countries. For instance, in 2022, the Maharashtra University of Health Sciences (India) launched the Mental Health and Normalcy Augmentation System (MANAS) app for its medical students across 469 colleges. Despite these developments, the stigma surrounding mental disorders remains a challenge to market growth in Asia-Pacific.
Competitive landscape
- 2024
Big Health Inc. (U.S.), a digital therapeutics company that offers apps for mental health, acquired Limbix (U.S.), a creator of evidence-based digital therapeutic (apps) for teens and young adults with symptoms of depression.
- 2021
Cognitive Apps Software (U.S.), a subsidiary of Life Clips, Inc. (U.S.), launched the Yuru 3-in-1 tool. This solution is designed to aid users in understanding and managing mental health.
- 2021
Headspace, a meditation app, announced a merger with Ginger (U.S.), a mental health service provider.
- Talkspace, Inc. (U.S.)
- BetterHelp (U.S.)
- Headspace Inc. (U.S.)
- Sanvello Health, Inc. (U.S.)
- ReachOut Australia · Australia
- Calm.com, Inc. (U.S.)
- Twill Inc. (U.S.)
- Worry Watch (U.S.)
- Jade Lizard Software LLC (U.S.)
- Insight Network Inc. (U.S.)
- Aura Health (U.S.)
- MoodMission Pty Ltd · Australia
- Youper Inc. (U.S.)
Frequently asked questions
The mental health apps market covers the market sizes & forecasts of the mental health apps market based on platform, application, patient type, and end user. This report also offers the value analysis of various segments and sub-segments of the mental health apps market at the regional and country levels.
Cite this report
Meticulous Research. (2024). Mental Health Apps Market - Global Opportunity Analysis and Industry Forecast (2025-2032) (Report No. MR-1170). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/reports/mental-health-apps-market-5853