HVAC Plastic Fans and Blowers Market (2026-2036)
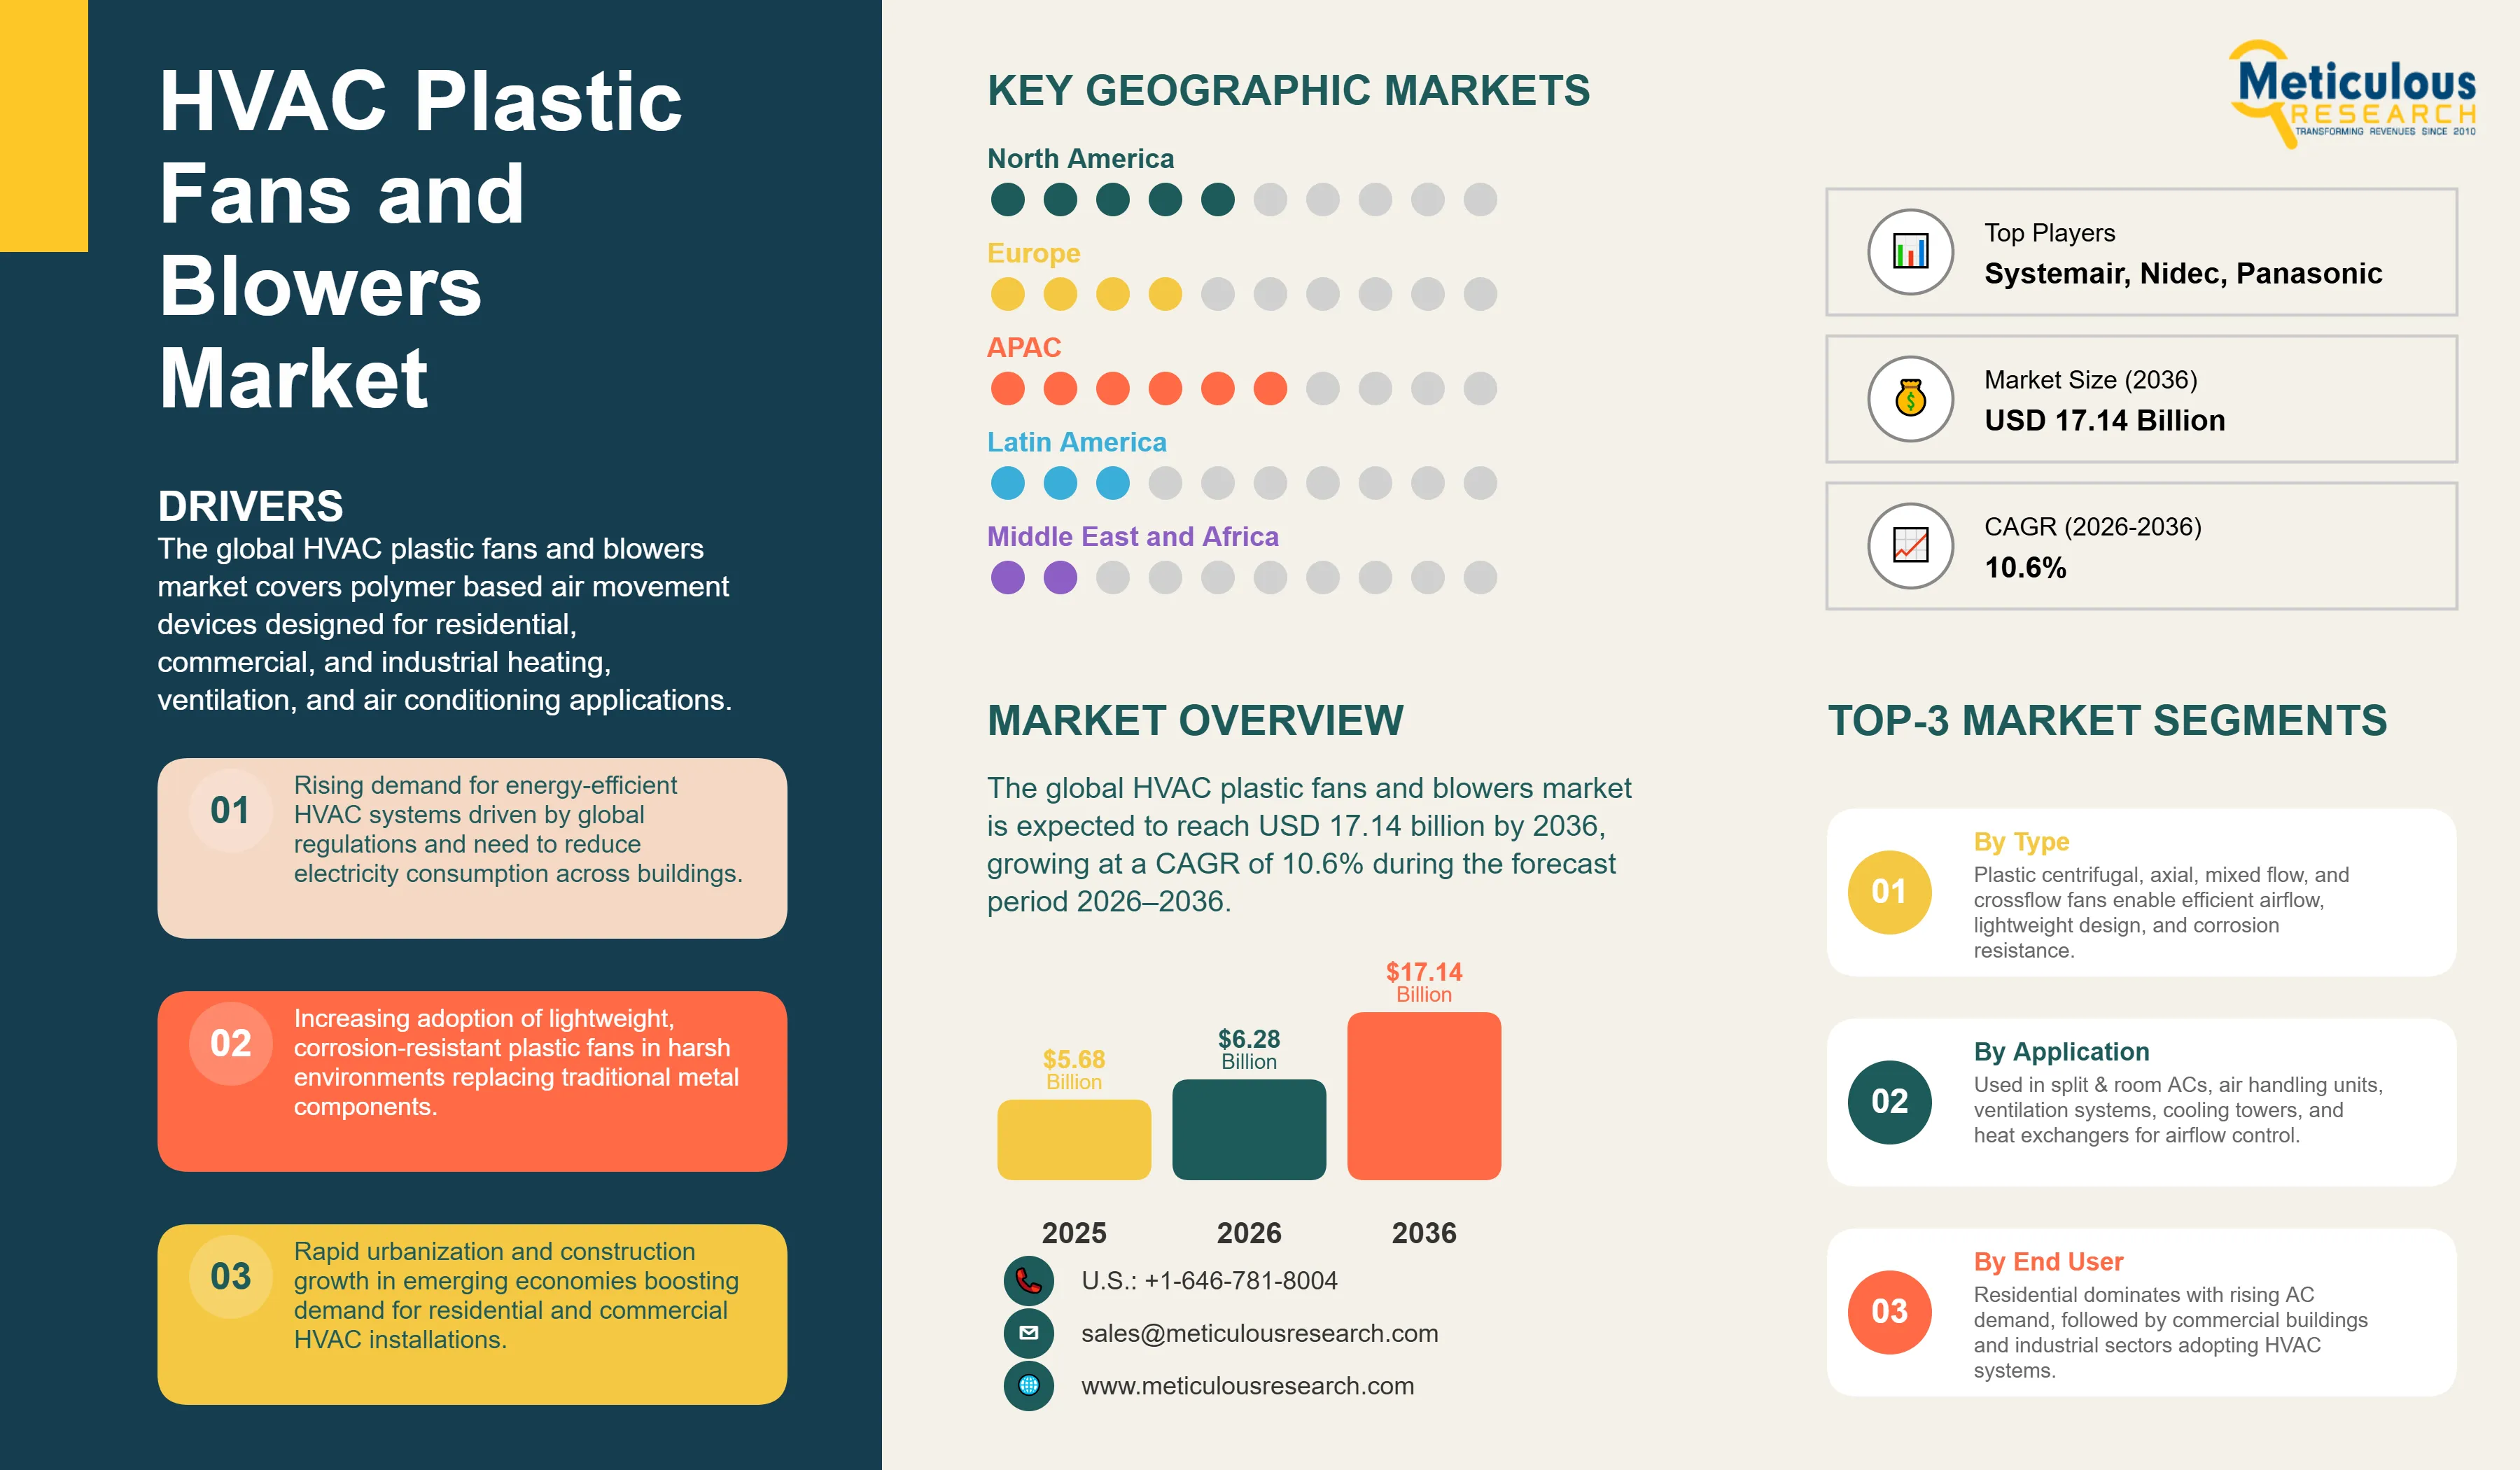
The global HVAC plastic fans and blowers market is estimated at USD 6.28 billion in 2026. This market is expected to reach USD 17.14 billion by 2036, growing at a CAGR of 10.6% during the forecast period 2026–2036.
- Published
- Apr 2026
- Pages
- 200
- Format
- PDF + Excel
- Report ID
- MREP - 1041917
- Base year
- 2025
- 2026 · ESTIMATED
- $6.28B
- 2036
- $17.14B
- CAGR 2026–2036
- 10.6%
2025 baseline · 2026–2036 forecast at 10.6% CAGR · hover a bar for the value
Key highlights
The global HVAC plastic fans and blowers market is projected to reach USD 17.14 billion by 2036.
The market is expected to grow at a CAGR of 10.6% during the forecast period 2026–2036.
The global HVAC plastic fans and blowers market is estimated at USD 6.28 billion in 2026.
Asia Pacific is expected to dominate the global HVAC plastic fans and blowers market with the largest share in 2026, driven by the region's established position as the primary manufacturing hub for residential air conditioning equipment, the massive scale of split and room air conditioner production across China, India, Japan, and Thailand, and rapidly expanding urbanization creating sustained demand for residential cooling solutions.
North America is expected to hold a significant share in 2026, driven by building retrofitting initiatives, high adoption of energy efficient mechanical systems, and compliance with ASHRAE Standard 90.1 mandates requiring fan energy performance improvements.
By product type, the plastic centrifugal fans segment is expected to hold the largest share in 2026, driven by the broad deployment of backward curved centrifugal configurations across commercial air handling units, cooling tower systems, and industrial ventilation applications.
By product type, the plastic mixed flow fans segment is projected to register the highest growth during the forecast period, driven by growing demand for compact and energy efficient inline duct ventilation systems and the widespread integration of these fans into energy recovery ventilation equipment.
By technology, the AC motor fans segment is expected to account for the largest share of the global HVAC plastic fans and blowers market in 2026, attributable to the established manufacturing base, competitive cost structures, and widespread use in fixed speed residential ventilation systems.
By technology, the EC motor fans segment is projected to register the highest CAGR during the forecast period, driven by superior energy savings of 30 to 50% compared to conventional AC motor systems and growing alignment with global building energy efficiency regulations.
By application, the split and room AC segment is expected to account for the largest share in 2026, driven by accelerating residential cooling adoption across emerging markets in Asia Pacific, the Middle East, and Latin America.
By end use, the residential segment is expected to dominate the market in 2026, while also registering among the highest growth rates throughout the forecast period.
By geography, Asia Pacific is expected to dominate the market in 2026 and also witness the fastest growth during the forecast period.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 17.14 Billion |
| Market Size in 2026 | USD 6.28 Billion |
| Revenue Growth Rate (2026–2036) | CAGR of 10.6% |
| Format | PDF, Excel & Cloud Portal · 200 pages |
| Dominating Product Type | Plastic Centrifugal Fans |
| Fastest Growing Product Type | Plastic Mixed Flow Fans |
| Dominating Technology | AC Motor Fans |
| Fastest Growing Technology | EC Motor Fans |
| Dominating Pressure Range | Low Pressure |
| Dominating Application | Split & Room AC |
| Dominating End Use | Residential |
| Dominating Geography | Asia Pacific |
| Fastest Growing Geography | Asia Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
Report overview
Segments covered: product, technology, pressure range, application, end use.
The global HVAC plastic fans and blowers market covers polymer based air movement devices designed for residential, commercial, and industrial heating, ventilation, and air conditioning applications. These include plastic centrifugal fans, plastic axial fans, plastic mixed flow fans, plastic crossflow fans, and plastic centrifugal blowers manufactured from engineering grade thermoplastics and fiber reinforced composite materials, deployed across a broad range of HVAC configurations including split and room air conditioning systems, air handling units, energy recovery ventilation equipment, cooling towers, and industrial ventilation systems.
HVAC plastic fans and blowers use high performance polymers like glass fiber reinforced polyamide, flame retardant polypropylene, and advanced composites to offer benefits over traditional metal designs, including corrosion resistance, lighter weight, and improved aerodynamics through precise molding. These fans come in a variety of designs, from backward and forward curved centrifugal fans to tube and vane axial fans, crossflow units for compact residential air conditioners, and mixed flow fans for energy recovery and inline duct systems. The category is integrated with electronically commutated motors and variable frequency drives to meet energy efficiency and demand controlled ventilation standards set by regulations such as ASHRAE Standard 90.1, the EU Ecodesign Directive (Lot 30), and the U.S. DOE Fan Energy Index.
The growth of the overall HVAC plastic fans and blowers market is primarily driven by growing adoption of energy efficient ventilation systems authorised by regulatory frameworks that favor lightweight, aerodynamically optimized impeller geometries achievable through polymer molding processes. Rising utilization of corrosion resistant fan components in demanding operating environments such as coastal buildings, healthcare facilities, swimming pools, and industrial applications is also contributing to market expansion, as moisture and chemical exposure accelerate degradation of metal alternatives. Expanding construction activities across emerging economies indicate another key growth driver, with Asia expected to accommodate nearly 50% of global urban population growth by 2050 according to the United Nations Department of Economic and Social Affairs. Furthermore, fan systems account for approximately 9% of commercial building electricity consumption globally according to the International Energy Agency, and plastic impellers enabling 30 to 50% fan energy savings through variable speed operation are increasingly favored by facility managers targeting lifecycle energy cost reductions. The rapid growth of data center infrastructure further supports market demand, with global data center electricity consumption projected to nearly double from 415 TWh in 2024 to 945 TWh by 2030 amid accelerating AI infrastructure expansion.
However, the growth of this market is restrained by temperature limitations of engineering thermoplastics, with maximum continuous operating temperatures between 80°C and 120°C restricting suitability for high temperature industrial exhaust applications. Fire performance requirements imposed by stringent codes including UL 723 and EN 13501 can further restrict plastic fan use in certain occupancy spaces without specialized flame retardant formulations. Additionally, perception challenges regarding structural durability compared with metal alternatives and volatility in specialty polymer resin pricing pose further challenges for market stakeholders.
On the other hand, the development of smart and IoT enabled fan systems integrated with EC motors and digital control interfaces enabling remote monitoring, predictive maintenance, and demand responsive operation represents a significant growth opportunity, with IoT control alone estimated to achieve 15 to 30% energy savings. Rising demand for noise reduced and aerodynamically optimized designs enabled by advanced computational fluid dynamics tools offers additional market development potential. The ongoing expansion of data center cooling infrastructure and integration of HVAC systems with renewable energy platforms are further expected to generate new avenues for market participants throughout the forecast period.
Report infographic
Market dynamics
3 factors across 1 forceEC Motor Integration Reshaping the Energy Efficiency Landscape in HVAC Fan Systems
The growing adoption of electronically commutated (EC) motors in plastic fan assemblies is one of the most significant near term trends in the HVAC fan and blower market. EC motors use electronic circuitry to drive brushless permanent magnets, offering energy savings of 30–50% compared with traditional AC motors. The light weight of plastic impellers lowers rotational inertia, making them ideal for EC motors and enabling precise, variable speed operation across the full airflow range, from 20% to 100% of capacity.
This combination is becoming popular in high performance commercial HVAC systems, where building owners and operators focus on reducing energy use over the system’s lifetime to meet sustainability goals and manage rising electricity costs. Pre engineered fan and motor assemblies that work with building automation protocols like BACnet and Modbus, along with advanced control interfaces, make EC motor plastic fans a top choice for projects aiming for LEED, BREEAM, or other green building certifications. Regulatory support is also driving adoption, as standards like ASHRAE 90.1 and the EU Ecodesign Directive are steering procurement toward electronically commutated, variable speed fan technologies in commercial and industrial settings.
Expanding Deployment of Energy Recovery Ventilation Driving Demand for Mixed Flow Plastic Fans
The growing regulatory emphasis on controlled mechanical ventilation and energy efficiency in residential and light commercial buildings is creating a sustained demand wave for plastic mixed flow fans integrated into energy recovery ventilation and heat recovery ventilation equipment. Mixed flow fans, combining the high volume airflow characteristics of axial designs with the pressure generation of centrifugal configurations, are widely deployed in inline duct ventilation systems and compact air handling units where moderate static pressure capability and high volume delivery are simultaneously required.
Energy recovery ventilation systems, which can capture 70–85% of thermal energy from exhaust air to boost heating and cooling efficiency, are increasingly being specified in residential and commercial projects across North America, Europe, and parts of Asia Pacific. Standards like ASHRAE 62.2 for residential ventilation feature the importance of controlled mechanical ventilation, creating a steady demand for mixed flow plastic fan assemblies. This trend is further strengthened by variable speed EC motor technology, which allows precise, demand based ventilation control, while the combination of aerodynamic efficiency and lightweight plastic construction meets the performance and cost requirements for high volume residential and light commercial applications.
IoT Enabled Smart Fan Systems Transitioning from Premium Specification to Mainstream Adoption
The digitalization of HVAC fan systems through IoT connectivity, smart sensor integration, and cloud based monitoring platforms is transitioning from a premium differentiating feature toward a mainstream product capability, driven by the growing demand for predictive maintenance, remote diagnostics, and demand responsive building operations. IoT enabled plastic fan assemblies providing real time performance data, fault detection, and automated alerting allow facility operators to reduce unplanned downtime and optimize maintenance schedules across large commercial and industrial installations.
The integration of smart control platforms compatible with BACnet, Modbus, and emerging open building automation standards enables HVAC fan systems to respond dynamically to real time occupancy patterns, indoor air quality measurements, and utility pricing signals, delivering the 15 to 30% energy savings attributed specifically to intelligent demand controlled ventilation strategies. Leading manufacturers including ebm papst Group and Delta Electronics are advancing integrated motor and fan platforms with embedded intelligence and digital communication capabilities, positioning IoT connectivity as a core design requirement rather than an optional feature for next generation HVAC plastic fan products targeting commercial, healthcare, and data center end use segments.
Table of contents
13 chapters · 166 sections · 200 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Product Type | Plastic Centrifugal Fans | Plastic mixed flow fans |
| By Technology | AC Motor Fans | EC motor fans |
| By Application | Split & Room AC | — |
By Product Type
- The Plastic Centrifugal Fans Segment to Dominate the Global HVAC Plastic Fans and Blowers Market
- The large share of this segment is attributed to the widespread deployment of backward curved centrifugal designs across commercial building air handling units, cooling tower applications, and industrial ventilation systems, driven by their ability to deliver high static pressure with improved aerodynamic performance and reduced motor power consumption.
- Building owners and facility managers increasingly emphasize minimizing lifecycle energy consumption to meet sustainability targets and mitigate rising electricity costs, driving adoption of optimized centrifugal fan technologies across commercial and industrial infrastructure.
- However, the plastic mixed flow fans segment is projected to register the highest growth during the forecast period.
- The high growth of this segment is driven by increasing demand for compact and energy efficient ventilation systems across residential and commercial buildings, the widespread integration of mixed flow fans into energy recovery ventilation equipment recovering 70 to 85% of thermal energy from exhaust air streams, and the strong alignment of this product category with ASHRAE 62.2 residential ventilation mandates requiring controlled mechanical ventilation.
- Integration with variable speed EC motor technologies enables improved system efficiency and demand based ventilation control, allowing HVAC systems to adjust airflow from 20 to 100% capacity based on real time occupancy and ventilation requirements.
By Technology
- The AC Motor Fans Segment to Hold the Largest Share
- The large share of this segment is attributed to widespread deployment across residential split air conditioning systems, compact ventilation units, and cost sensitive commercial HVAC equipment where simplicity and price competitiveness remain primary selection criteria.
- AC motor driven plastic fans dominate the residential crossflow fan market used in wall mounted indoor units, representing the majority of global room air conditioner installations.
- However, the EC motor fans segment is projected to register the highest growth during the forecast period, driven by superior energy efficiency, precise speed control capabilities, and alignment with global building performance regulations.
- EC motors integrate electronic commutation circuitry that enables brushless permanent magnet operation, delivering 30 to 50% energy savings compared to traditional AC motor platforms.
- The lightweight nature of plastic impellers reduces rotational inertia, making them well suited for variable speed operation with EC motor controls, while pre engineered motor and fan assemblies compatible with BACnet and Modbus protocols position EC motor plastic fans as the technology of choice for high performance commercial HVAC systems.
By Application
- The Split & Room AC Segment to Hold the Largest Share
- The dominant share of this segment reflects the accelerating adoption of residential cooling systems across emerging markets in Asia Pacific, the Middle East, and Latin America experiencing sustained temperature increases, rising household incomes, and rapid urbanization.
- The International Energy Agency projects global installed air conditioning units to grow from approximately 2.5 billion in 2025 to more than 6 billion units by 2050, with nearly 70% of this increase driven by developing economies.
- Plastic crossflow fans enabling ultra compact indoor unit designs with 15 to 25% weight reduction dominate this application, while outdoor condensing units increasingly utilize plastic axial propeller fans for heat rejection.
Geographic analysis
Asia-Pacific
Largest shareChina alone represents the world's largest market for residential air conditioning with annual production exceeding 130 million room air conditioner units. The region benefits from large scale OEM concentration, cost competitive manufacturing infrastructure, and strong domestic demand driven by rapid urbanization and rising disposable incomes. Asia Pacific is also expected to witness the fastest growth during the forecast period, driven by accelerating air conditioner penetration in emerging economies across India and Southeast Asia that remain significantly underpenetrated in terms of residential cooling, and by government regulations promoting energy efficiency and EC motor integration encouraging technological upgrades in fan systems.
North America
North America is expected to maintain a significant market share in 2026, driven by building retrofitting initiatives, high performance mechanical system adoption, and compliance requirements established by ASHRAE Standard 90.1.
Europe
Europe accounts for 19.5% of the market in 2026, supported by the stringent requirements of the EU Ecodesign Directive and the widespread deployment of energy recovery ventilation systems across cold climate regions.
Competitive landscape
- Ziehl Abegg SE · Germany
- Nidec Corporation · Japan
- Delta Electronics Inc. · Taiwan
- Systemair AB · Sweden
- FläktGroup Holding GmbH · Germany
- Zhejiang Yilida Ventilator Co. Ltd. · China
- Nisshinbo Holdings Inc. · Japan
- Carrier Global Corporation (U.S.)
- Johnson Controls International plc · Ireland
- Panasonic Corporation · Japan
- Daikin Industries Ltd. · Japan
- Greenheck Fan Corporation (U.S.)
- Nortek Global HVAC (U.S.)
- Regal Rexnord Corporation (U.S.)
- Midea Group · China
- Gree Electric Appliances Inc. · China
- Haier Group Corporation · China
- LG Electronics Inc. · South Korea
Frequently asked questions
The global HVAC plastic fans and blowers market is estimated at USD 6.28 billion in 2026 and is expected to reach USD 17.14 billion by 2036, at a CAGR of 10.6% during the forecast period 2026–2036.
Cite this report
Meticulous Research. (2026). HVAC Plastic Fans and Blowers Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MREP - 1041917). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/hvac-plastic-fans-and-blowers-market-6600