High Voltage Direct Current (HVDC) Transmission Systems Market (2026-2036)
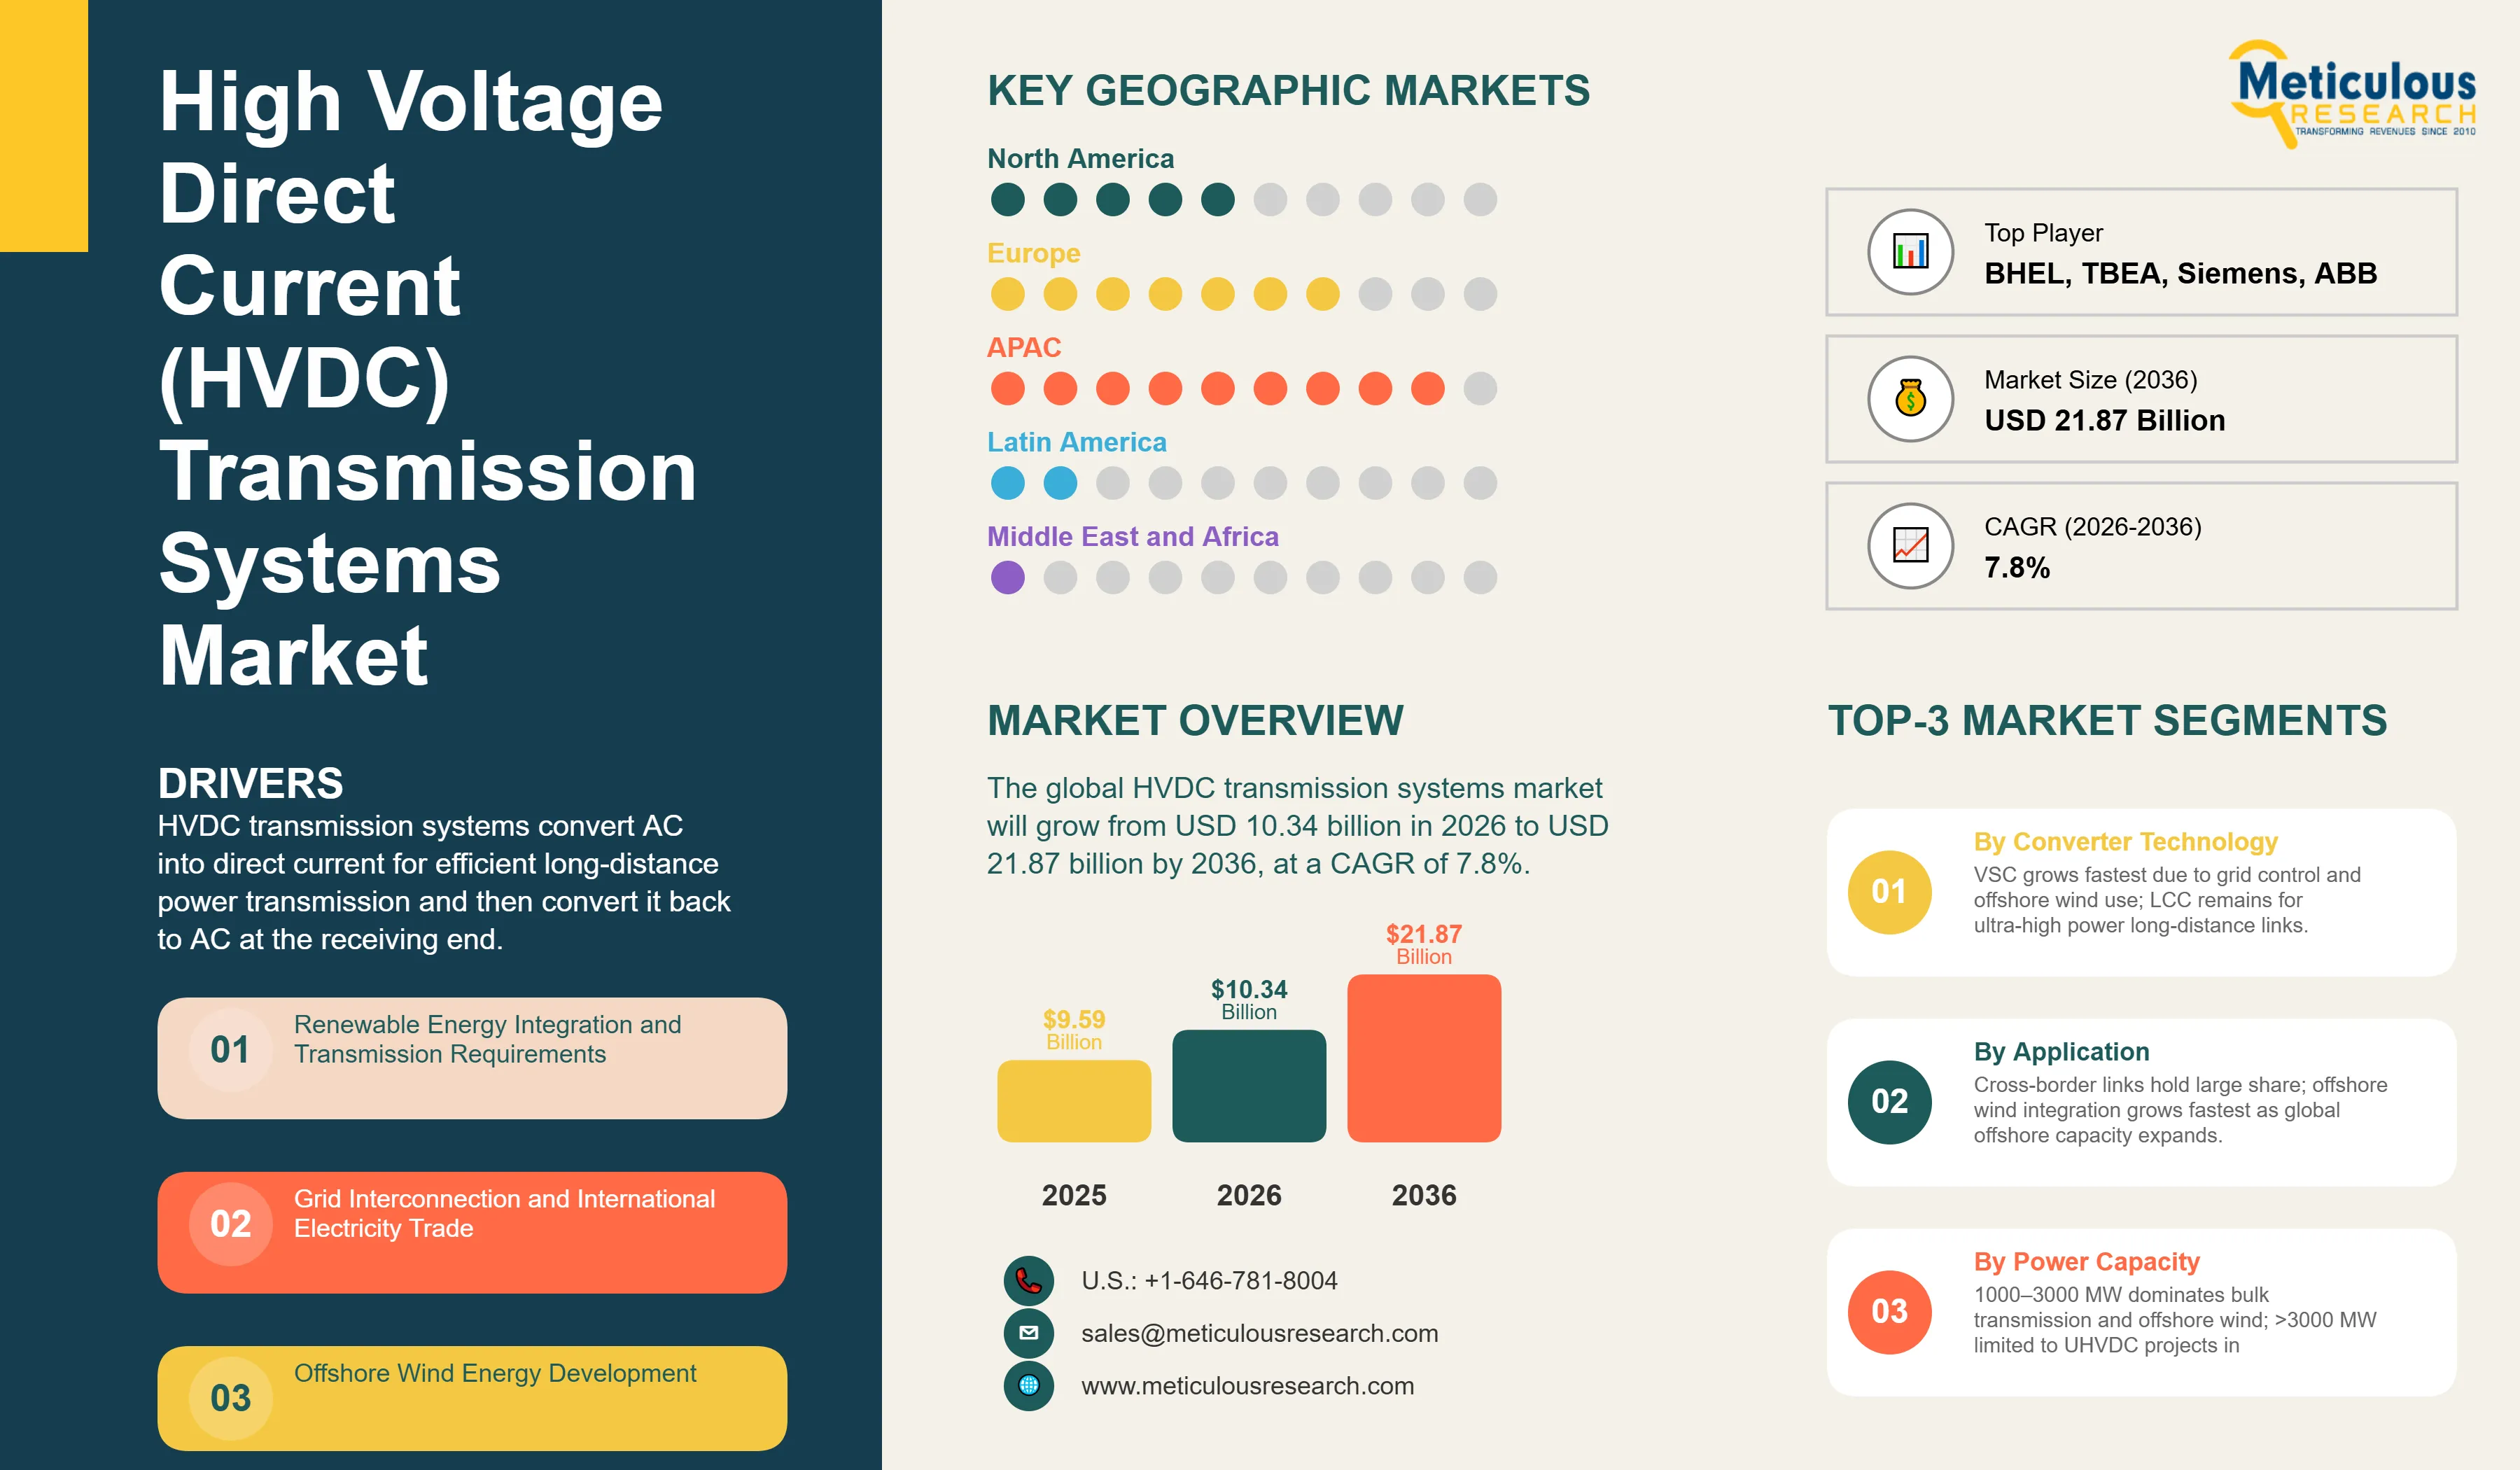
The global high voltage direct current (HVDC) transmission systems market is expected to reach USD 21.87 billion by 2036 from USD 10.34 billion in 2026, at a CAGR of 7.8% from 2026 to 2036.
- Published
- Jan 2026
- Pages
- 288
- Format
- PDF + Excel
- Report ID
- MR-1680
- Base year
- 2025
- 2026 · ESTIMATED
- $10.34B
- 2036
- $21.87B
- CAGR 2026–2036
- 7.8%
2025 baseline · 2026–2036 forecast at 7.8% CAGR · hover a bar for the value
Key highlights
In 2026, Asia-Pacific accounts for the largest share of the global HVDC transmission systems market, driven by massive investments in long-distance power transmission in China and India, renewable energy integration requirements, cross-border interconnections, and presence of major HVDC technology suppliers.
Europe is projected to register the highest CAGR during the forecast period, fueled by aggressive offshore wind development, European Green Deal targets, cross-border grid interconnections, and replacement of aging transmission infrastructure with advanced HVDC systems.
Based on converter technology, the voltage source converter (VSC) segment is expected to witness the highest growth during the forecast period, driven by superior performance for offshore wind integration, black start capability, independent reactive power control, and suitability for multi-terminal HVDC networks.
Based on voltage rating, the ±320 kV to ±500 kV segment holds significant market share in 2026, representing the optimal balance between transmission capacity and technical complexity for majority of long-distance and offshore wind applications.
Based on power capacity, the 1000-3000 MW segment dominates the market in 2026, serving the largest portion of bulk power transmission projects including major interconnections and large offshore wind farm connections.
Based on application, the cross-border and regional interconnections segment accounts for substantial market share in 2026, driven by international electricity trade, grid reliability enhancement, and renewable energy sharing across borders.
The offshore wind integration segment is expected to grow at the highest CAGR during the forecast period, driven by explosive growth of offshore wind capacity, technical advantages of HVDC for long-distance submarine transmission, and government renewable energy targets.
The U.S. HVDC transmission systems market is projected to grow at a CAGR of around 6% during the forecast period 2026 to 2036, driven by renewable energy zone connection, aging grid infrastructure replacement, and interstate transmission expansion.
China is expected to lead the Asia-Pacific HVDC transmission systems market, driven by the world's most extensive HVDC network connecting remote renewable resources to load centers, ultra-high voltage DC (UHVDC) technology leadership, and continued grid expansion investments.
In 2026, Germany is projected to account for significant share of the European HVDC transmission systems market, driven by offshore wind integration requirements, role as European electricity transit hub, and Energiewende energy transition investments.
Report summary
| Particulars | Details |
|---|---|
| Market Size Value in 2026 | USD 10.34 Billion |
| Revenue Forecast in 2036 | USD 21.87 Billion |
| Growth Rate | CAGR of 7.8% from 2026 to 2036 |
| Format | PDF, Excel & Cloud Portal · 288 pages |
| Base Year for Estimation | 2025 |
| Historical Data | 2021–2025 |
| Forecast Period | 2026–2036 |
| Quantitative Units | Revenue in USD Billion and CAGR from 2026 to 2036 |
| Report Coverage | Revenue forecast, company ranking, competitive landscape, growth factors, and trends |
| Segments Covered | Converter Technology, Voltage Rating, Power Capacity, Application, Configuration, Region |
| Regional Scope | North America, Europe, Asia-Pacific, Latin America, Middle East & Africa |
| Countries Covered | U.S., Canada, Germany, U.K., France, Netherlands, Belgium, Denmark, Norway, China, India, Japan, South Korea, Australia, Brazil, Chile, Saudi Arabia, UAE |
| Key Companies Profiled | ABB Ltd., Siemens Energy AG, Hitachi Energy Ltd. (formerly ABB Power Grids), General Electric Company, Mitsubishi Electric Corporation, Toshiba Corporation, BHEL (Bharat Heavy Electricals Limited), Prysmian Group, NKT A/S, NR Electric Co. Ltd., XJ Group Corporation, Hyosung Heavy Industries, LS Electric Co. Ltd., Nexans S.A., Sumitomo Electric Industries Ltd., C-EPRI Electric Power Engineering Co. Ltd., TBEA Co. Ltd., China XD Electric Co. Ltd., Alstom SA (Grid business now part of GE), Schweitzer Engineering Laboratories |
Report overview
Segments covered: converter technology, voltage rating, power capacity, application.
High Voltage Direct Current (HVDC) transmission systems are modern technologies that convert alternating current (AC) to direct current (DC) for long-distance power transmission and then switch back to AC at the receiving end. These systems include power electronic converter stations that use thyristor or insulated-gate bipolar transistor (IGBT) technology, high-voltage DC cables or overhead transmission lines rated from ±100 kV to ±800 kV or higher, control systems that manage power flow and grid stability, and protection schemes that ensure reliability. By using direct current instead of conventional alternating current, HVDC systems offer important benefits. They can transmit large amounts of power over distances greater than 600-800 km with lower losses than AC systems. They also allow for the interconnection of AC grids that operate at different frequencies, connect remote renewable energy sources like offshore wind farms to mainland grids, and facilitate submarine and underground cable transmission, which avoids the limitations of overhead lines. Additionally, HVDC systems provide precise control of power flow, independent of grid resistance. These features make HVDC technology crucial for modern power grids that integrate renewable energy, support international electricity trading, and transmit power across difficult geographical areas such as oceans, mountains, and busy urban areas.
High Voltage Direct Current transmission systems are a game-changing technology that tackle key issues in modern power systems. They offer efficient long-distance power transmission, help integrate remote renewable energy sources, and connect incompatible AC grids. These advanced systems act like electrical superhighways, allowing gigawatts of power to travel thousands of kilometers with much lower losses than traditional AC transmission. They also provide precise control and unique benefits that AC systems cannot match. The basic principles of DC transmission, like no reactive power, no skin effect, and being independent of system frequency, enable HVDC to overcome the limitations of AC systems, especially over long distances or specific uses, like underwater cables.
Several key trends are transforming the HVDC market. The rapid growth of offshore wind energy is creating a need for long-distance underwater transmission. Developments in voltage source converter (VSC) technology are allowing for multi-terminal HVDC networks and offering grid services. Ultra-high voltage DC (UHVDC) systems, operating at ±800 kV and higher, are making long-distance power transmission possible. More cross-border connections are emerging, facilitating international electricity trade and sharing of renewable energy. HVDC is now being combined with energy storage and grid flexibility solutions to support a high level of renewable energy use. The rise of renewable energy, the need for updated grids, climate change measures, and advancements in HVDC technology have made HVDC a crucial infrastructure component in the global energy transition.
Report infographic
Market dynamics
7 factors across 3 forcesRenewable Energy Integration and Transmission Requirements
The global growth of renewable energy, especially wind and solar power, is the main factor driving HVDC market growth. Renewable sources are often far from where energy is consumed, like offshore wind in deep ocean waters, onshore wind in remote areas, and solar in deserts. This creates a need for long-distance transmission systems. The International Energy Agency states that renewable electricity generation capacity must triple by 2030 to meet climate goals, which will require significant investments in transmission infrastructure. HVDC technology is vital for integrating renewable energy by enabling cost-effective transmission over long distances, where AC is inefficient (usually beyond 600-800 km overhead or 60-80 km underwater). It allows for the connection of large offshore wind farms, which would be too costly or impossible with AC underwater cables, and helps link remote renewable areas like Mongolian wind, Chilean solar, and Australian solar to major demand centers. It also enables energy sharing between regions with different frequencies (50 Hz and 60 Hz grids). China is a prime example of HVDC deployment driven by renewables, with over 30 UHVDC lines transmitting hydropower from the southwest, wind from the northwest and north, and solar from the west to eastern demand centers. Europe’s goals for offshore wind—potentially reaching 300 GW by 2050—will require extensive HVDC underwater networks. India’s green energy corridor, which connects solar and wind resources to the national grid, heavily relies on HVDC. The mismatch between where renewable resources are and where electricity is needed makes HVDC transmission vital for the global energy transition.
Grid Interconnection and International Electricity Trade
The increasing need for grid interconnection, driven by reliability, cost-effectiveness, and renewable energy integration, is boosting HVDC demand for cross-border and regional links. HVDC allows the connection of asynchronous AC grids that operate at different frequencies (50 Hz and 60 Hz) or cannot be synchronized due to technical or political issues. This supports electricity trading and improves grid reliability without synchronization risks that could cause failures across borders. Key interconnection projects propelling HVDC growth include the integration of Europe’s energy market with multiple cross-border HVDC links connecting Scandinavian hydropower to Continental Europe, the UK to Continental Europe, and Mediterranean solar to Northern Europe. Asian interconnections also include concepts for a Northeast Asian supergrid linking the grids of Russia, Mongolia, China, Korea, and Japan. In South America, interconnections connect a variety of resources across countries. The Gulf Cooperation Council (GCC) is also working on power grid interconnections in the Middle East. These projects aim to improve economic efficiency by sharing diverse generation resources and demand profiles, helping integrate renewable energy to balance the variability of wind and solar power. They also enhance grid reliability through mutual support during emergencies and promote geopolitical cooperation through energy infrastructure as a way to foster broader collaboration. The European Union's Projects of Common Interest (PCI) framework highlights priority cross-border infrastructure, including several HVDC projects. China's Belt and Road Initiative also includes cross-border electricity links to neighboring countries. These policies create ongoing demand for HVDC interconnection systems.
Table of contents
15 chapters · 197 sections · 288 pages · click to expandGeographic analysis
Asia-Pacific
Largest shareIn 2026, the Asia-Pacific region holds the largest share of the global HVDC transmission systems market. This leading position comes mainly from China's extensive development of HVDC infrastructure. China has the world's largest HVDC network, with over 30 UHVDC lines either operational or under construction. These lines transmit hundreds of gigawatts from western hydropower and northern renewable resources to eastern coastal load centers. The country is also a technology leader in ±800 kV UHVDC, with more than a decade of operational experience. In addition, China continues to invest in multiple projects that are in planning and execution phases. India is the second largest HVDC market in the region, featuring several long-distance transmission projects that link renewable energy zones, such as solar parks in Rajasthan and Gujarat, to load centers. This includes efforts to strengthen the national grid and enhance regional interconnections. Together, China and India account for over 60% of the global HVDC capacity additions in recent years. Beyond these two countries, the Asia-Pacific region includes emerging offshore wind markets. Taiwan is developing significant offshore wind capacity that will need HVDC connections. Japan is planning to expand its offshore wind capabilities in deeper waters off the Pacific coast, while South Korea has offshore wind targets that require submarine HVDC. The region also has major HVDC equipment suppliers, including Chinese companies like XJ Group, TBEA, China XD Electric, and NR Electric, which advance technology and export globally. Additionally, Japanese companies such as Toshiba, Mitsubishi Electric, and Hitachi Energy hold strong technology positions, while Korean firms like Hyosung and LS Electric are developing their capabilities. Government support, through investments from state-owned utilities like the State Grid Corporation of China and China Southern Power Grid, as well as national energy plans, ensures ongoing HVDC deployment. The European region is set to grow at the highest compound annual growth rate during the forecast period. This growth is driven by aggressive offshore wind development, with European Commission targets potentially reaching 300 GW by 2050. Achieving this will require extensive HVDC submarine networks. The expansion of cross-border interconnections is fueled by the need for a more integrated internal energy market. There is also significant renewable energy transmission, like moving solar power from the Mediterranean to Northern Europe and hydropower from Scandinavia to Continental Europe. Additionally, aging grid infrastructure will need to be replaced with modern HVDC systems to improve capacity and control. Major factors driving this growth include the EU Green Deal and Fit for 55 climate goals, which require substantial renewable integration. The Projects of Common Interest (PCI) framework supports cross-border infrastructure projects, and initiatives like the North Sea Wind Power Hub are planning offshore HVDC networks. National energy transition programs, such as Germany's Energiewende, the Netherlands' climate plans, and the UK's net-zero targets, also play a role.
Europe
Key projects in Europe include multiple offshore wind connections in Germany (Dolwin, Sylwin, Helwin, BorWin clusters), offshore connections in Belgium and the Netherlands, interconnectors between the UK and Continental Europe, Mediterranean interconnections, and links in Scandinavia. The region benefits from leading HVDC technology suppliers like Hitachi Energy (from Switzerland, Sweden, and the UK), Siemens Energy (from Germany), and specialized cable suppliers such as Prysmian, NKT, and Nexans. Strong environmental regulations, public opposition to overhead transmission, and land constraints make HVDC underground and submarine solutions more favorable.
North America
North America is becoming a growing market due to the need for renewable energy integration. This includes connecting remote wind resources in the Great Plains and offshore wind developments on the East Coast, which plan to have over 30 GW of capacity requiring HVDC submarine connections. The region also faces the need to replace aging grid infrastructure that has been in use for over 50 years. Furthermore, inter-regional transmission is expanding capacity between different grid areas, as well as the potential for Canadian hydropower exports to the United States. However, this region has unique challenges. It has a fragmented regulatory environment, with multiple state and federal authorities complicating project development. There are also right-of-way issues for new transmission corridors, and historically, lower HVDC deployment has led to an experience gap compared to Asia and Europe. Despite this, there is a growing acknowledgment of the benefits of HVDC for renewable integration and grid modernization. Key projects include planned enhancements to inter-regional transmission, East Coast offshore wind connections as projects advance, and potential projects similar to Northern Pass that would import Canadian hydropower. Major suppliers in the North American market include GE (U.S.), Hitachi Energy (which has a strong presence in North America), and Siemens Energy.
Competitive landscape
- Siemens Energy AG · Germany
- Hitachi Energy Ltd. · Switzerland/Japan
- General Electric Company (U.S.)
- Mitsubishi Electric Corporation · Japan
- Toshiba Corporation · Japan
- BHEL (Bharat Heavy Electricals Limited) · India
- Prysmian Group · Italy
- NKT A/S · Denmark
- NR Electric Co. Ltd. · China
- XJ Group Corporation · China
- Hyosung Heavy Industries · South Korea
- LS Electric Co. Ltd. · South Korea
- Nexans S.A. · France
- Sumitomo Electric Industries Ltd. · Japan
- C-EPRI Electric Power Engineering Co. Ltd. · China
- TBEA Co. Ltd. · China
- China XD Electric Co. Ltd. · China
- Schweitzer Engineering Laboratories (U.S.)
Frequently asked questions
The HVDC transmission systems market is expected to grow from USD 10.34 billion in 2026 to USD 21.87 billion by 2036.
Cite this report
Meticulous Research. (2026). High Voltage Direct Current (HVDC) Transmission Systems Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MR-1680). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/high-voltage-direct-current-transmission-systems-market-6363