EV Charging Software Market (2026-2036)
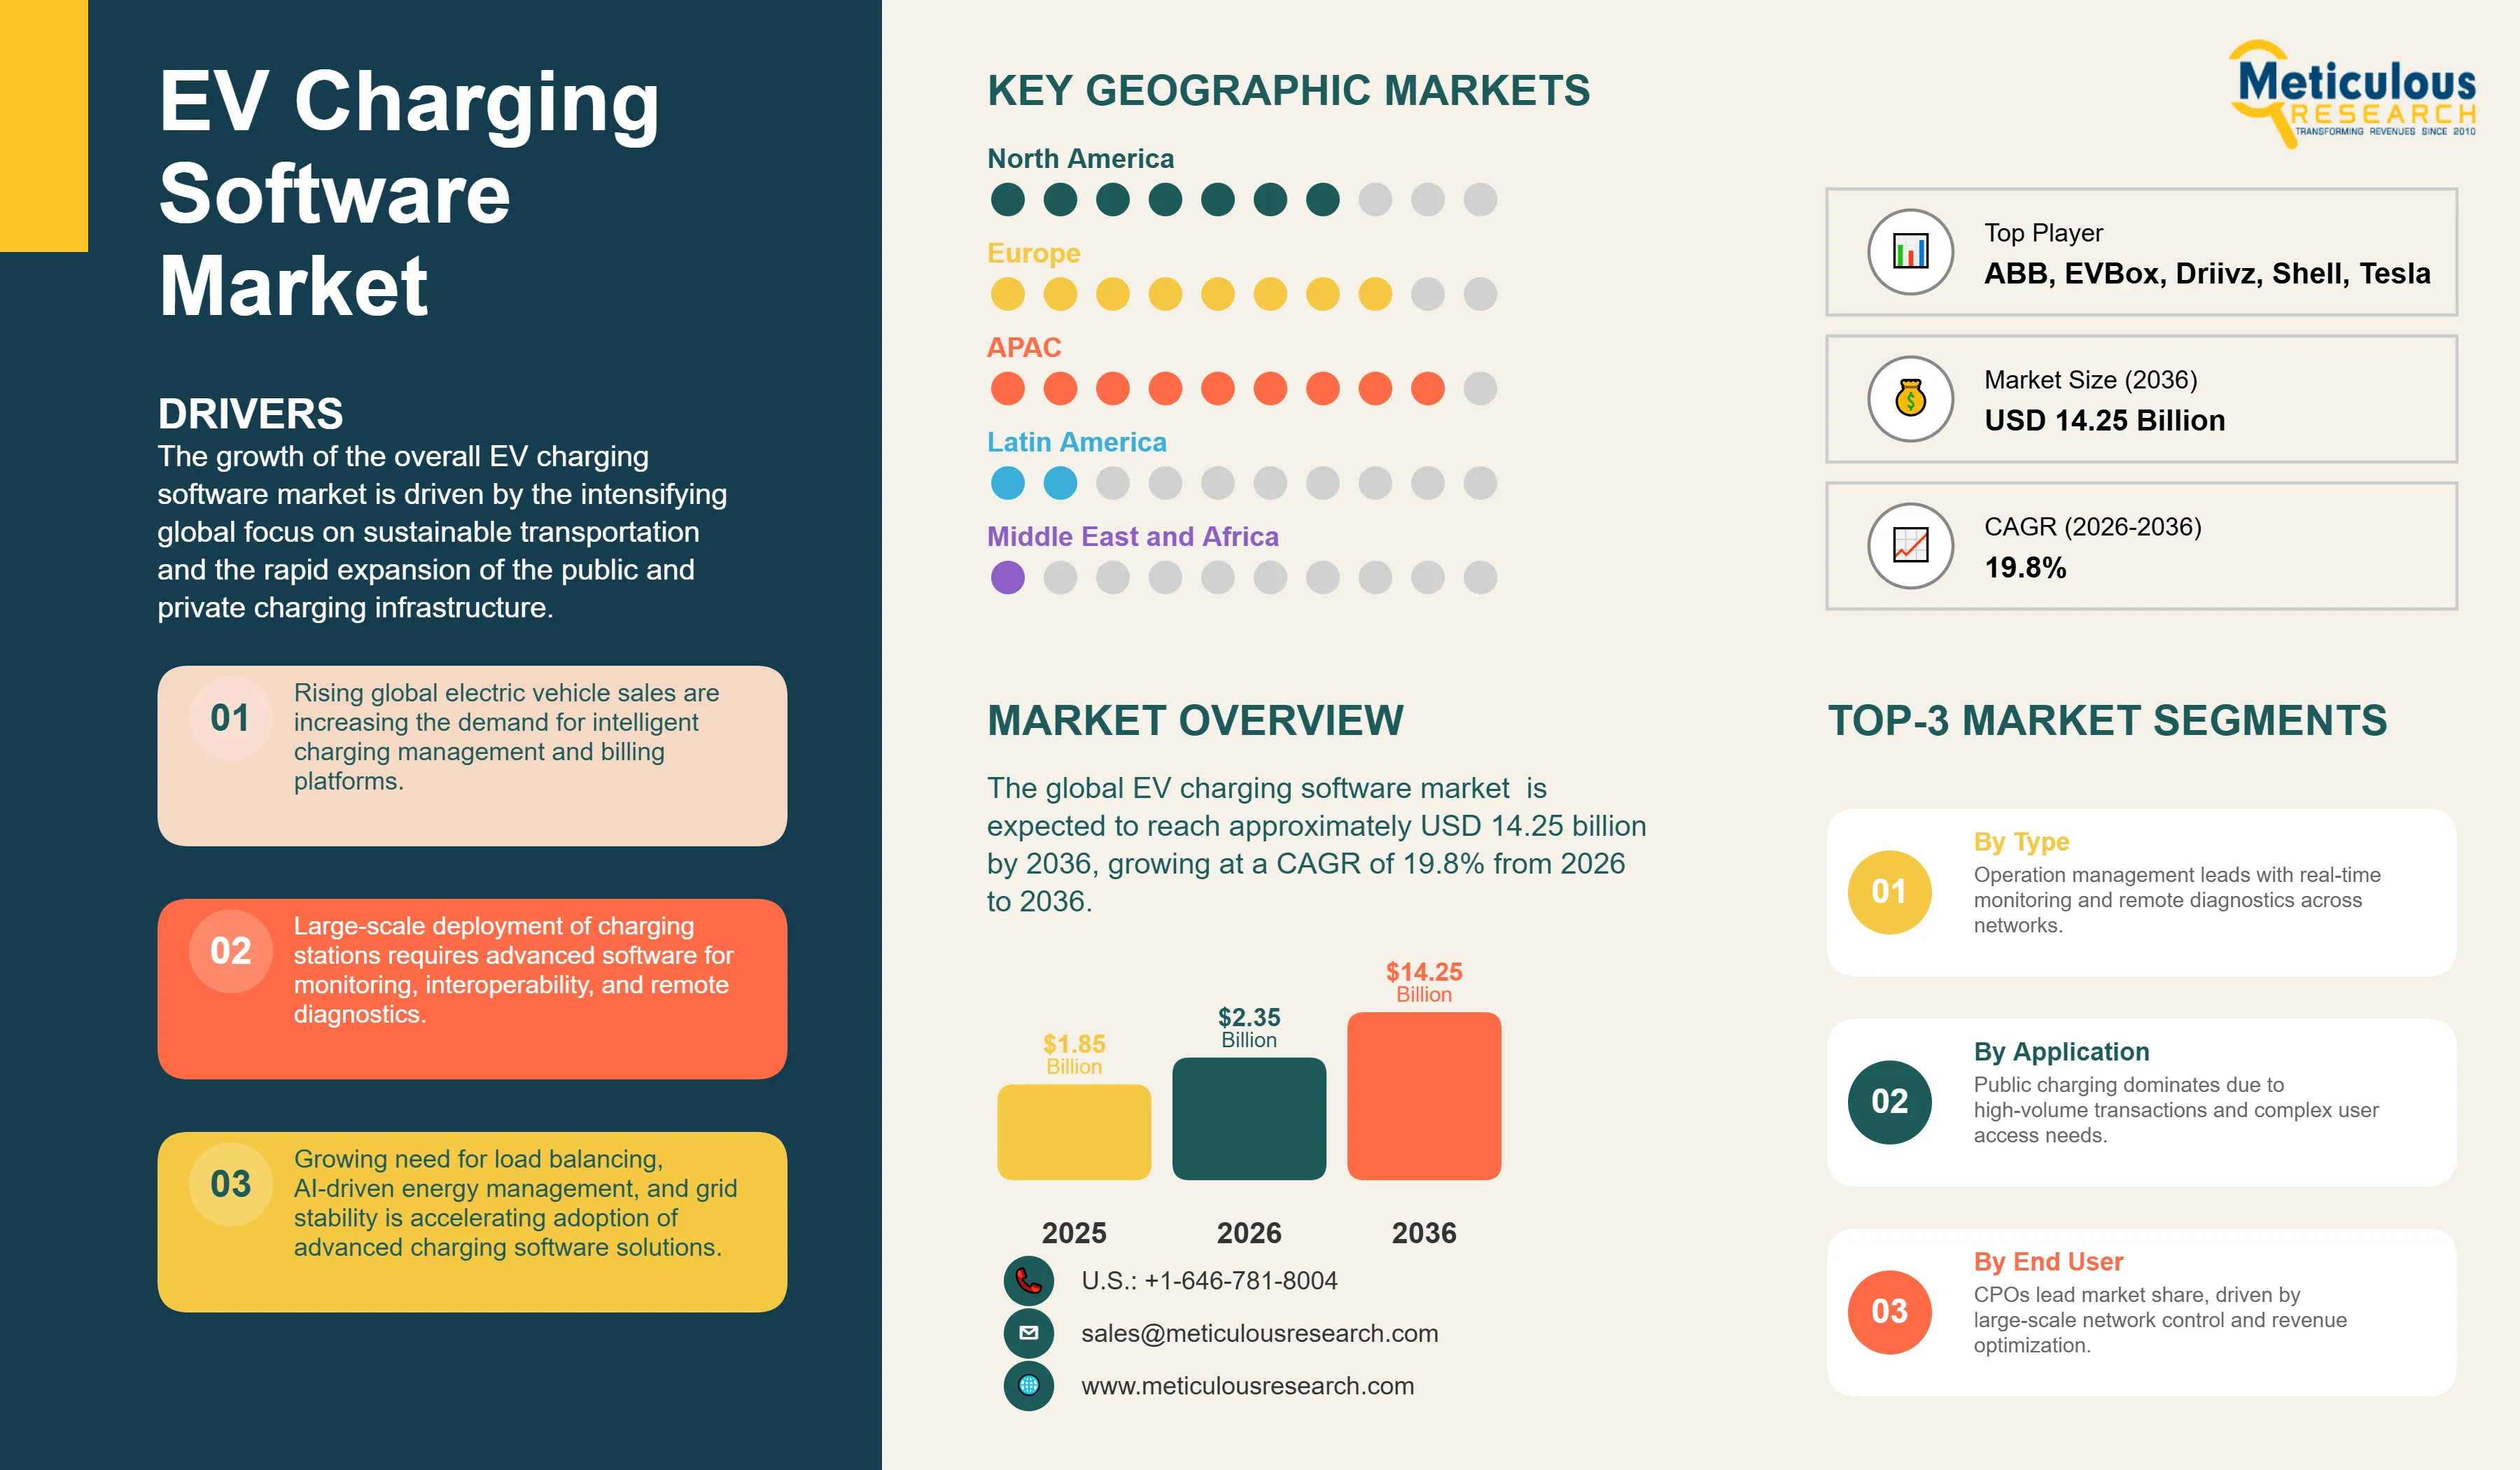
The global EV charging software market was valued at USD 1.85 billion in 2025. The market is expected to reach approximately USD 14.25 billion by 2036 from USD 2.35 billion in 2026, growing at a CAGR of 19.8% from 2026 to 2036.
- Published
- Feb 2026
- Pages
- 267
- Format
- PDF + Excel
- Report ID
- MR-1734
- Base year
- 2025
- 2025 · BASELINE
- $1.85B
- 2036
- $14.25B
- CAGR 2026–2036
- 19.8%
2025 baseline · 2026–2036 forecast at 19.8% CAGR · hover a bar for the value
Key highlights
In terms of revenue, the global EV charging software market is projected to reach USD 14.25 billion by 2036.
The market is expected to grow at a CAGR of 19.8% from 2026 to 2036.
Asia Pacific dominates the global EV charging software market with the largest market share in 2026, driven by massive urbanization and the presence of leading EV manufacturing hubs in China, Japan, and South Korea.
Europe is expected to witness significant growth during the forecast period, supported by aggressive R&D investments and the rapid adoption of advanced interoperability standards.
By module, the operation management segment holds the largest market share in 2026, particularly in supporting real-time monitoring and remote diagnostics in diverse urban environments.
By deployment, the public charging segment holds the largest market share in 2026, due to its proven efficacy in handling high-volume transactions and diverse user requirements.
By end-user, the Charge Point Operators (CPOs) segment holds the largest share of the overall market in 2026.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 14.25 Billion |
| Market Size in 2026 | USD 2.35 Billion |
| Market Size in 2025 | USD 1.85 Billion |
| Market Growth Rate (2026-2036) | CAGR of 19.8% |
| Format | PDF, Excel & Cloud Portal · 267 pages |
| Dominating Region | Asia-Pacific |
| Fastest Growing Region | Europe |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
| Segments Covered | Module, Deployment, End-User, and Region |
| Regions Covered | North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa |
Report overview
Segments covered: module, deployment, end-user.
The growth of the overall EV charging software market is driven by the intensifying global focus on sustainable transportation and the rapid expansion of the public and private charging infrastructure. As manufacturers seek to integrate more intelligence into charging networks and address the increasing demand for seamless user experiences and grid stability, advanced charging management platforms have become essential for maintaining operational efficiency and mechanical durability. The rapid expansion of the smart city infrastructure and the increasing need for high-performance energy management and billing solutions continue to fuel significant growth of this market across all major geographic regions.
EV charging software systems are critical digital frameworks used to provide remote management while allowing for energy optimization and user authentication throughout the charging process. These systems include management platforms, mobile applications, and billing engines, which are designed to withstand high-frequency usage and fit into diverse hardware ecosystems. The market is defined by high-efficiency modules such as load balancing algorithms and OCPP-compliant protocols, which significantly enhance system uptime and signal performance in complex network applications. These systems are indispensable for manufacturers seeking to optimize their internal software architecture and meet aggressive electrification targets.
The market includes a diverse range of solutions, ranging from simple monitoring tools for basic station status to complex multilayer management systems for high-performance fleet operations and grid defense. These systems are increasingly integrated with advanced components such as AI-driven predictive maintenance and ultra-fast payment gateways to provide services such as real-time occupancy tracking and improved revenue stability. The ability to provide stable, high-precision results while minimizing operational downtime has made advanced EV charging software the technology of choice for industries where network reliability and scalability are paramount.
The global mobility sector is pushing hard to modernize infrastructure capabilities, aiming to meet AI-driven routing and hyper-connected charging targets. This drive has increased the adoption of high-density software platforms, with advanced data analytics techniques helping to stabilize network yields for ultra-fine charging architectures. At the same time, the rapid growth in the commercial fleet and professional utility markets is increasing the need for high-reliability, clinically-proven energy management solutions.
Report infographic
Market dynamics
4 factors across 3 forcesEV Adoption and Rise of Smart Infrastructure
A key driver of the EV charging software market is the rapid movement of the global mobility industry toward data-backed, highly functional infrastructure. Global consumer demand for seamless charging, effective network support, and health-monitoring software systems has created significant incentives for the adoption of charging software products. The trend toward “clean” technology and the integration of mobility into daily digital patches drive manufacturers toward scalable solutions that EV charging software can uniquely provide. It is estimated that as consumer adoption of automated routines rises and diagnostic tools become more decentralized through 2036, the need for robust, effective management platforms increases significantly; therefore, operation management and billing modules, with their ability to ensure high-density data delivery, are considered a crucial enabler of modern mobility design strategies.
Table of contents
10 chapters · 105 sections · 267 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Module | Operation Management | — |
| By Deployment | Public Charging | — |
| By End-User | Charge Point Operators (CPOs) | — |
By Module
- The operation management segment accounts for a significant portion of the overall EV charging software market in 2026.
- This is mainly attributed to the versatile use of this technology in supporting real-time monitoring and complex remote diagnostics within extremely diverse environments, such as in urban centers and high-altitude regions.
- These systems offer the most comprehensive way to ensure network integrity across diverse high-frequency applications.
- The public and commercial sectors alone consume a large share of software production, with major projects in Asia Pacific and Europe demonstrating the technology’s capability to handle high-density data requirements.
- However, the energy management segment is expected to grow at a rapid CAGR during the forecast period, driven by the growing need for robust load balancing in smart grids, clinical procedures, and luxury mobility systems.
By Deployment
- The public charging segment holds the largest share of the overall market in 2026.
- This is primarily due to the massive volume of public infrastructure projects and the rigorous performance standards required for modern mobility networks.
- Current large-scale charging hubs are increasingly specifying high-density management platforms to ensure compliance with global performance standards and consumer expectations for faster, visible results.
- The private charging segment is expected to witness steady growth during the forecast period.
- The shift toward home energy management and the complexity of workplace charging suites are pushing the requirement for advanced active systems that can handle varied vehicle types and mechanical stresses while ensuring absolute reliability for safety-critical mobility systems.
By End-User
- The Charge Point Operators (CPOs) segment commands the largest share of the global EV charging software market in 2026.
- This dominance stems from its superior network management capacity, data consistency, and excellent mechanical properties, making it the technology of choice for high-performance charging systems.
- Large-scale operations in public networks, professional mobility, and high-end beauty drive demand, with advanced platforms from suppliers like ChargePoint and EVBox enabling reliable performance in extreme environments.
- However, the fleet operators segment is poised for steady growth through 2036, fueled by expanding applications in commercial logistics and simple delivery formulations.
- Manufacturers face mounting pressure to optimize costs for high-volume, less demanding applications, where standardized software modules provide a cost-effective alternative for basic mobility connectivity.
Geographic analysis
Asia-Pacific
Largest shareAsia Pacific holds the largest share of the global EV charging software market in 2026. The largest share of this region is primarily attributed to the massive urbanization and the presence of the world’s largest EV manufacturing hubs, particularly in China, Japan, and South Korea. China alone accounts for a significant portion of global software production, with its position as a leading exporter of high-end mobility driving sustained growth. The presence of leading manufacturers like TELD and a well-developed mobility supply chain provides a robust market for both standard and high-density software solutions.
North America
Europe and North America together account for a substantial share of the global EV charging software market. The growth of these markets is mainly driven by the need for technological modernization in the professional, luxury, and commercial mobility sectors. The demand for advanced software systems in North America is mainly due to its large-scale R&D projects and the presence of innovators like ChargePoint and EV Connect.
Europe
In Europe, the leadership in interoperability engineering and the push for data safety innovation are driving the adoption of high-reliability mobility products. Countries like Germany, the Netherlands, and the UK are at the forefront, with significant focus on integrating smart software solutions into daily routines and advanced mobility treatments to ensure the highest levels of performance and reliability.
Competitive landscape
- ChargePoint, Inc.
- EVBox (ENGIE)
- Driivz · Vontier
- Shell Recharge Solutions
Frequently asked questions
The global EV charging software market is expected to grow from USD 2.35 billion in 2026 to USD 14.25 billion by 2036.
Cite this report
Meticulous Research. (2026). EV Charging Software Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MR-1734). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/ev-charging-software-market-6417